
Welcome to the second weekly edition of Aftermarket Report, where we wrap up the week in the markets and take you through everything that mattered, both in India and globally.
What data points and transformations do you want to see?
We’re also experimenting with a weekly edition of the Aftermarket Report, and we’d love to know what you’d find useful in it.
Unlike the daily report, the idea here is to step back from individual trading sessions and look at the bigger picture — what changed over the week, where trends are building, how sectors and themes are moving, how positioning has shifted, and what the data tells us when viewed over a longer timeframe.
We’re exploring everything from weekly market breadth, sector and thematic trends, F&O positioning and flows to volatility, commodities, global markets, and more. But we want to know what you would like to track.
What data points, transformations, ratios, comparisons, charts, or indicators would make a weekly market wrap genuinely useful for you?
Tell us what you’d like to see. Your feedback will help us shape the weekly edition of the Aftermarket Report.
Weekly market performance
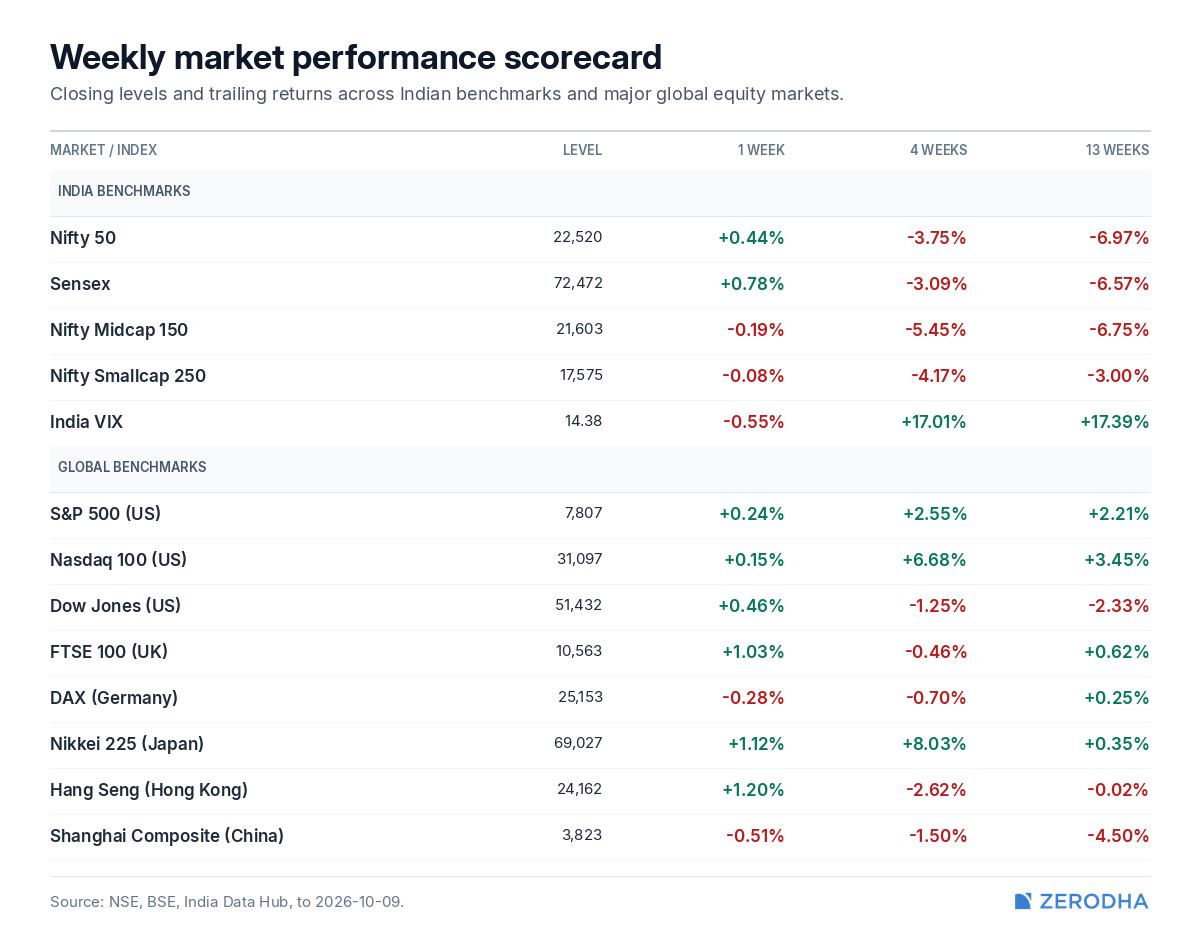
Nifty ended a volatile week with a modest 0.44% gain, closing at 22,520, after swinging through a 544-point range. Despite the positive weekly close, the broader market remains firmly in a downtrend. Nifty is trading 6.5% below its 40-week moving average, a level it has remained below for 26 consecutive weeks.
What is the macro backdrop doing?
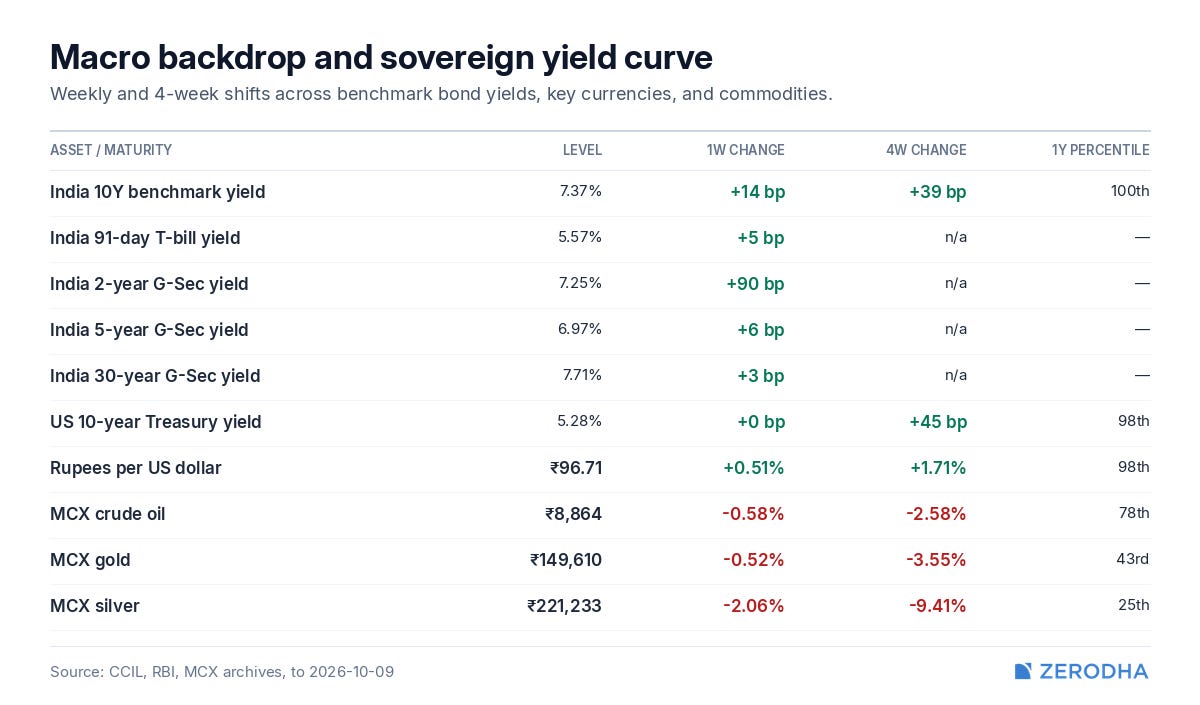
On the macro front, the benchmark 10-year G-Sec yield rose 14 bp over the week (approaching annual highs), while the rupee traded at ₹96.71 per US dollar.
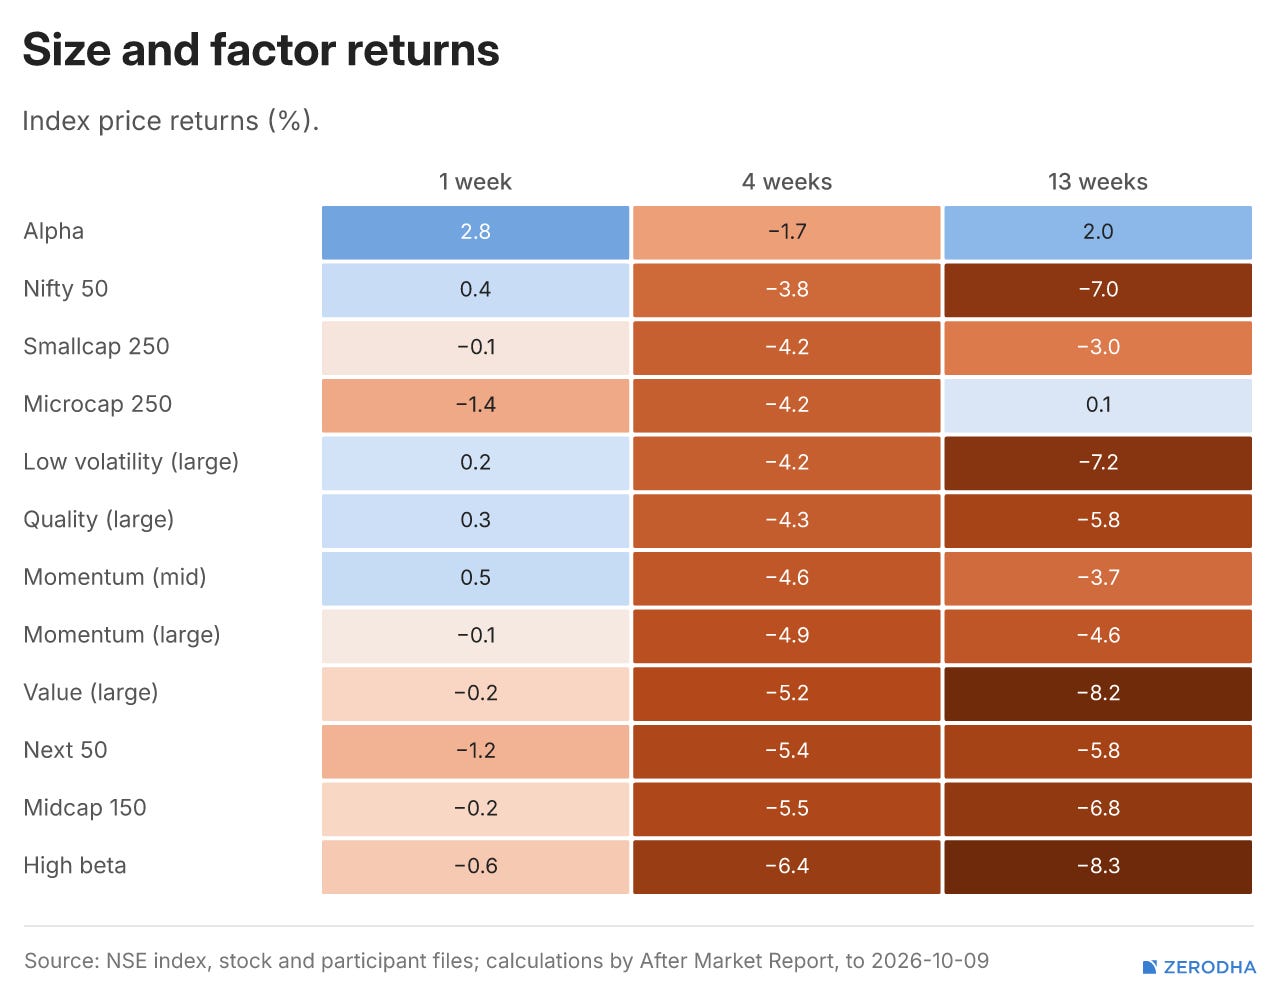
Momentum continued to outperform reversal strategies, winning in 9 of the last 13 weeks. Over four weeks, Nifty 50 outperformed broader indices, while Alpha was the strongest factor and High Beta the weakest.
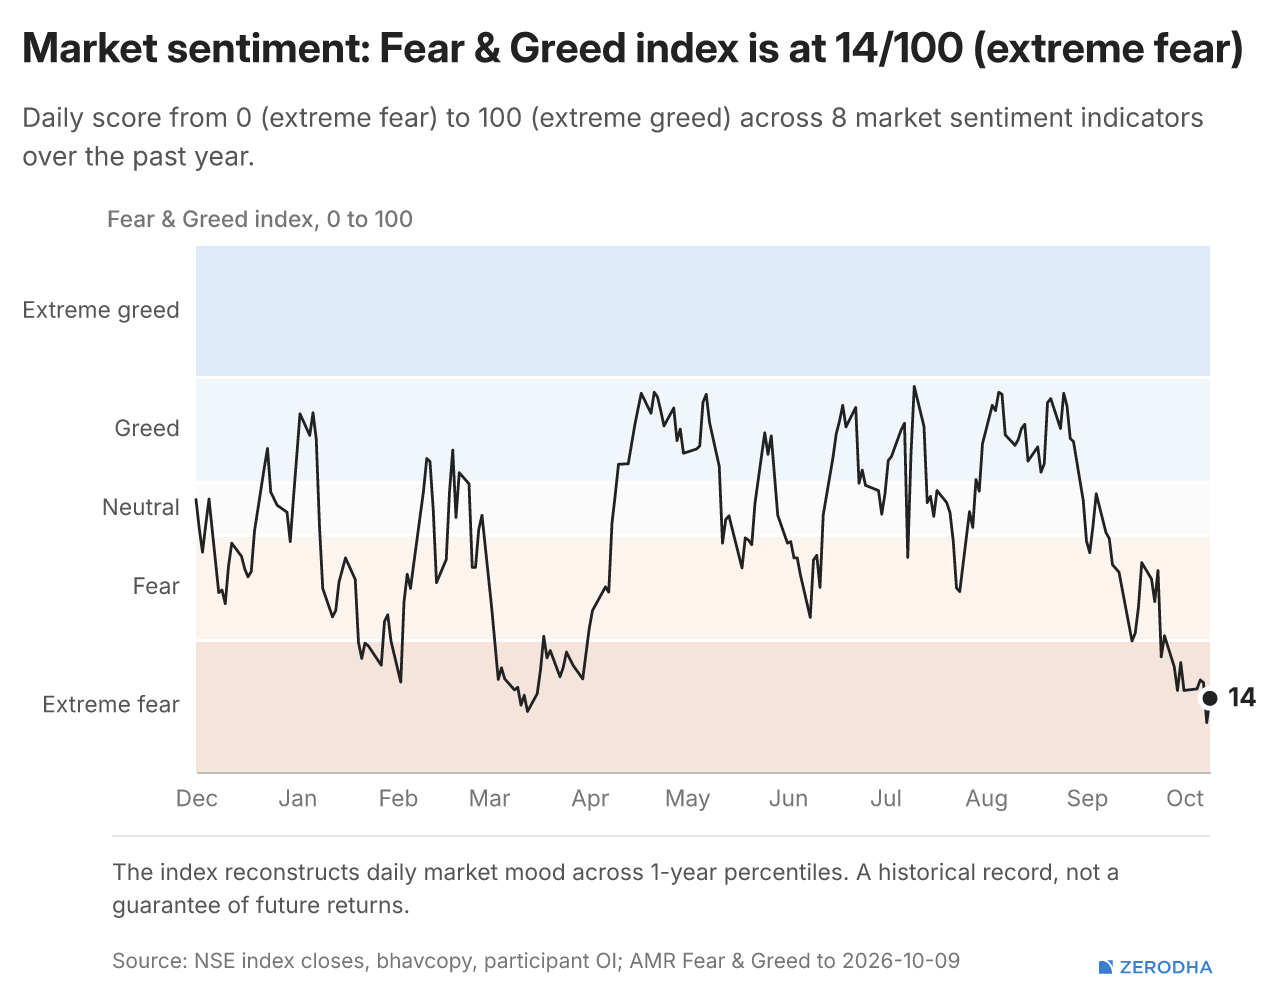
Fear & Greed trend
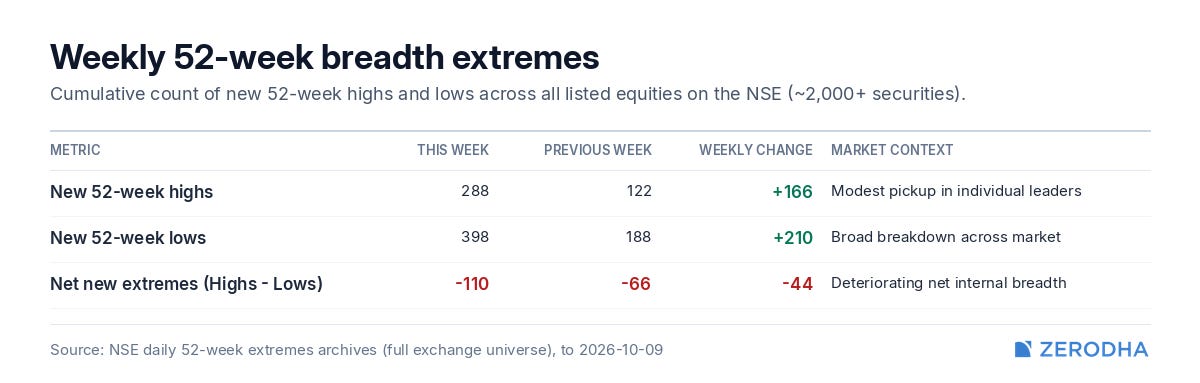
Market Breadth
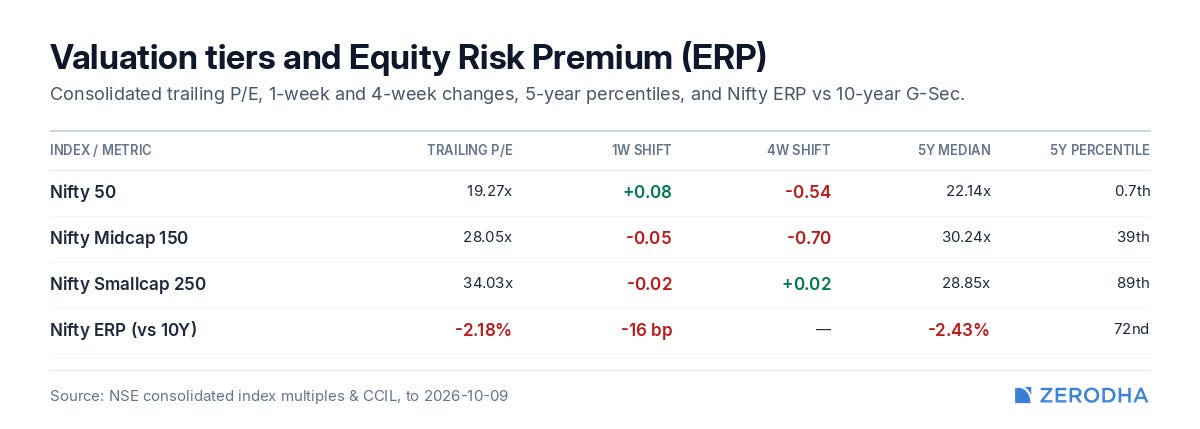
Valuation Check
Nifty trades at 19.27× earnings, near its lowest valuation in five years, while smallcaps remain expensive at 34.03×. The equity risk premium stood at -2.18%, compared with its five-year median of -2.43%.
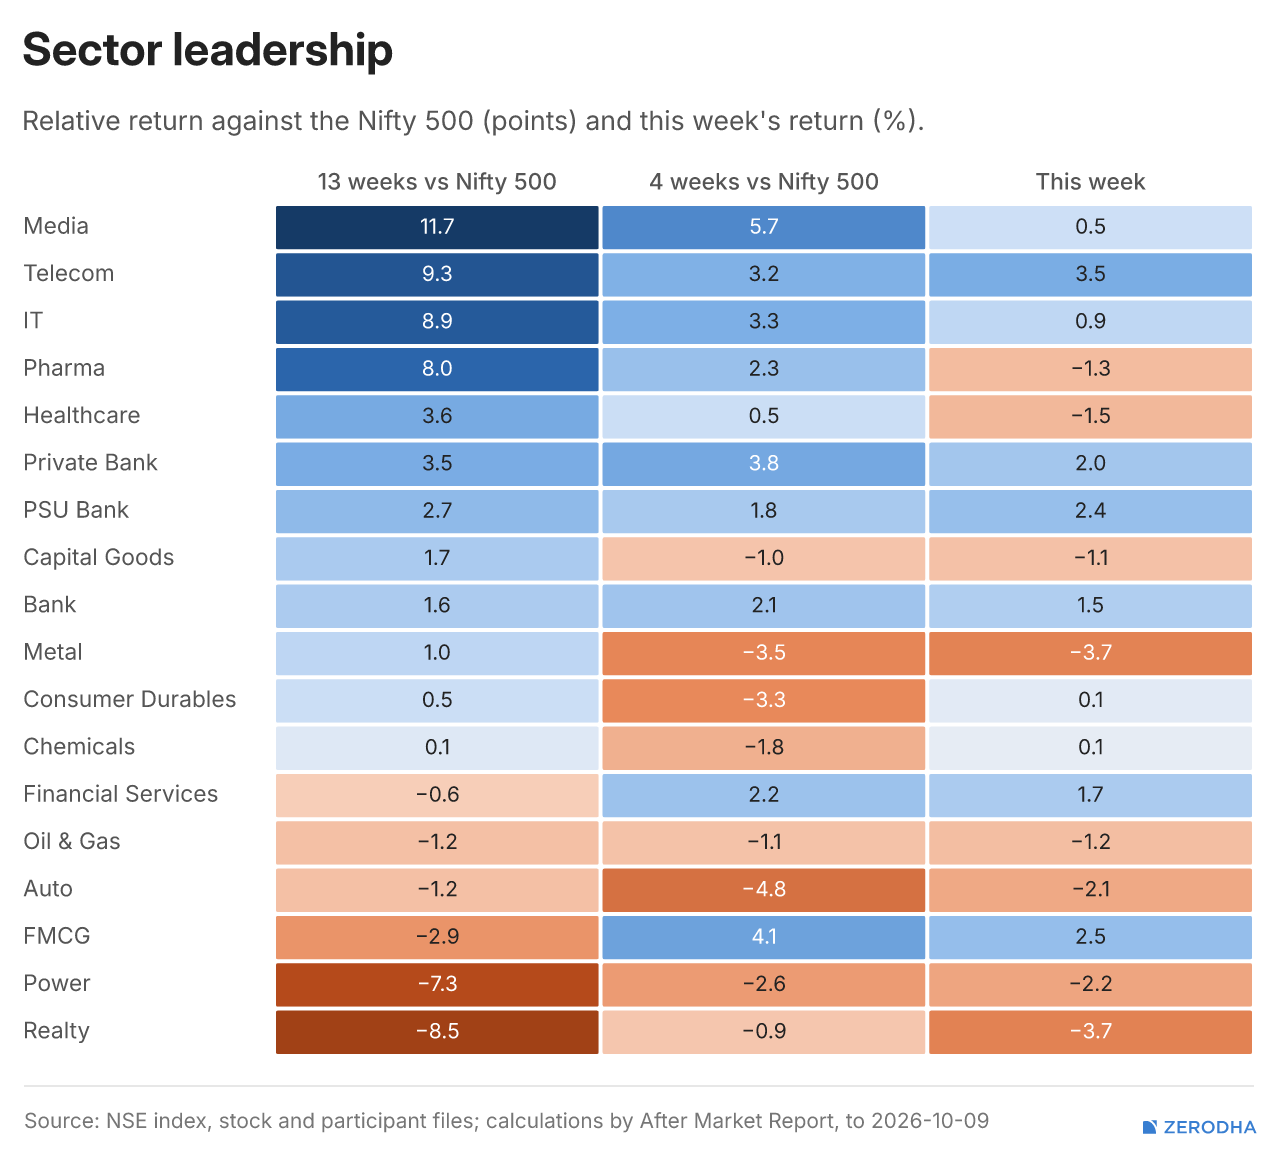
Sectoral summary
Media, Telecom, IT and Pharma remain the strongest sectors relative to Nifty 500 over 13 weeks. Financial Services and FMCG are showing improvement, while Metals, Capital Goods and Consumer Durables are losing momentum.
Selective stock screeners
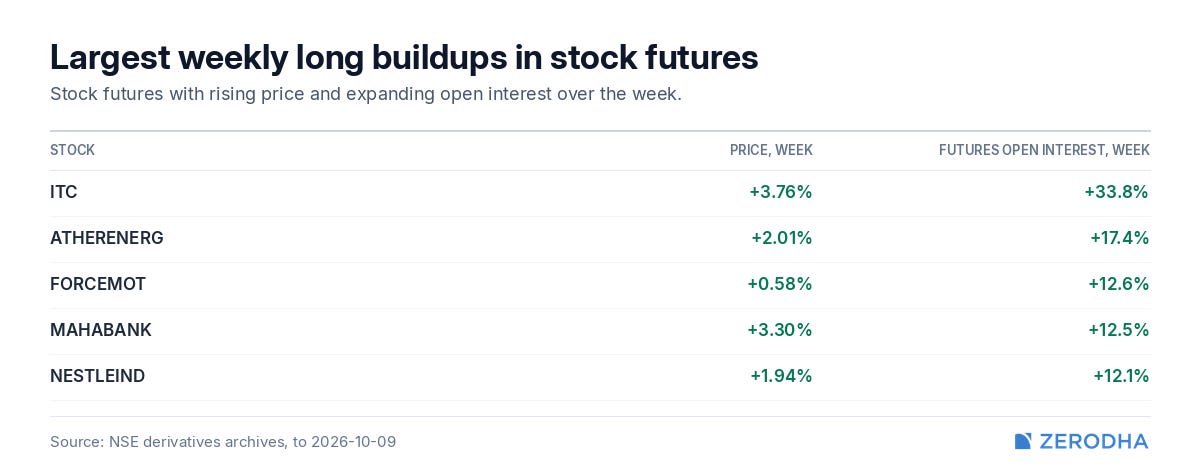
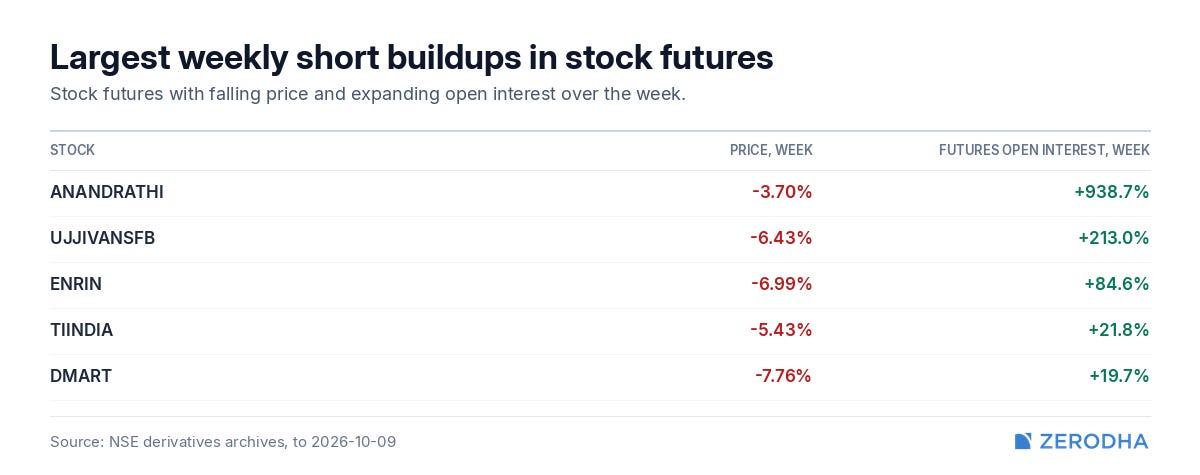
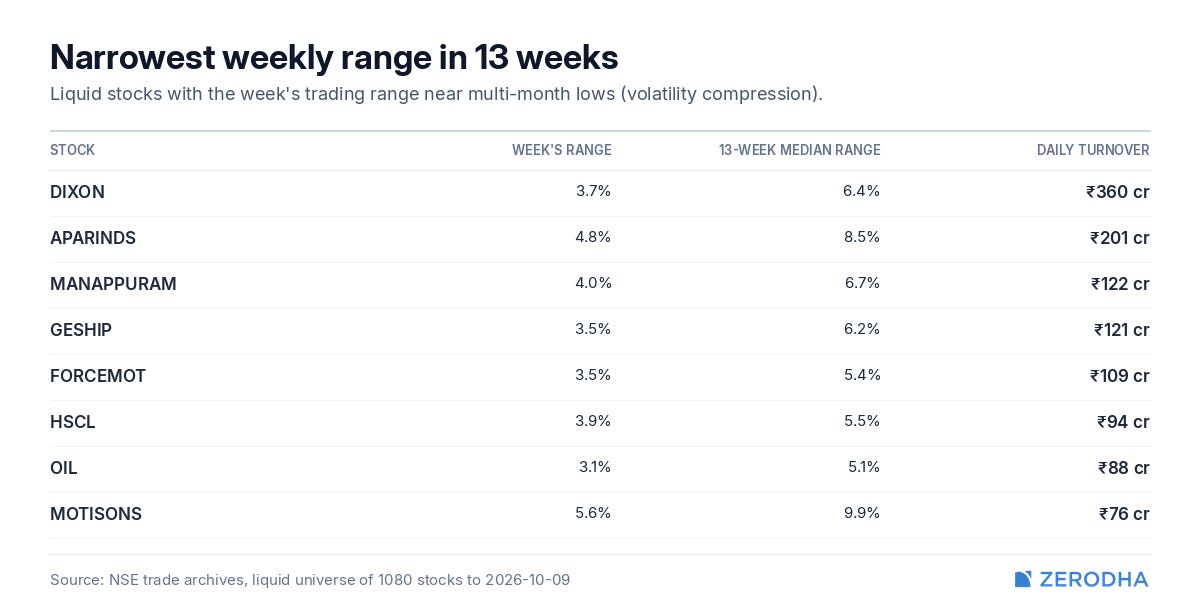
Deals of the week
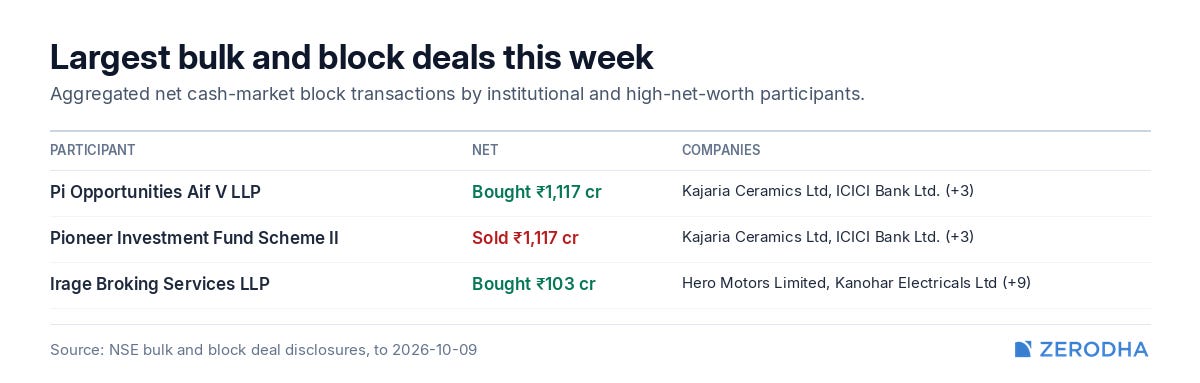
Institutional flows & positioning
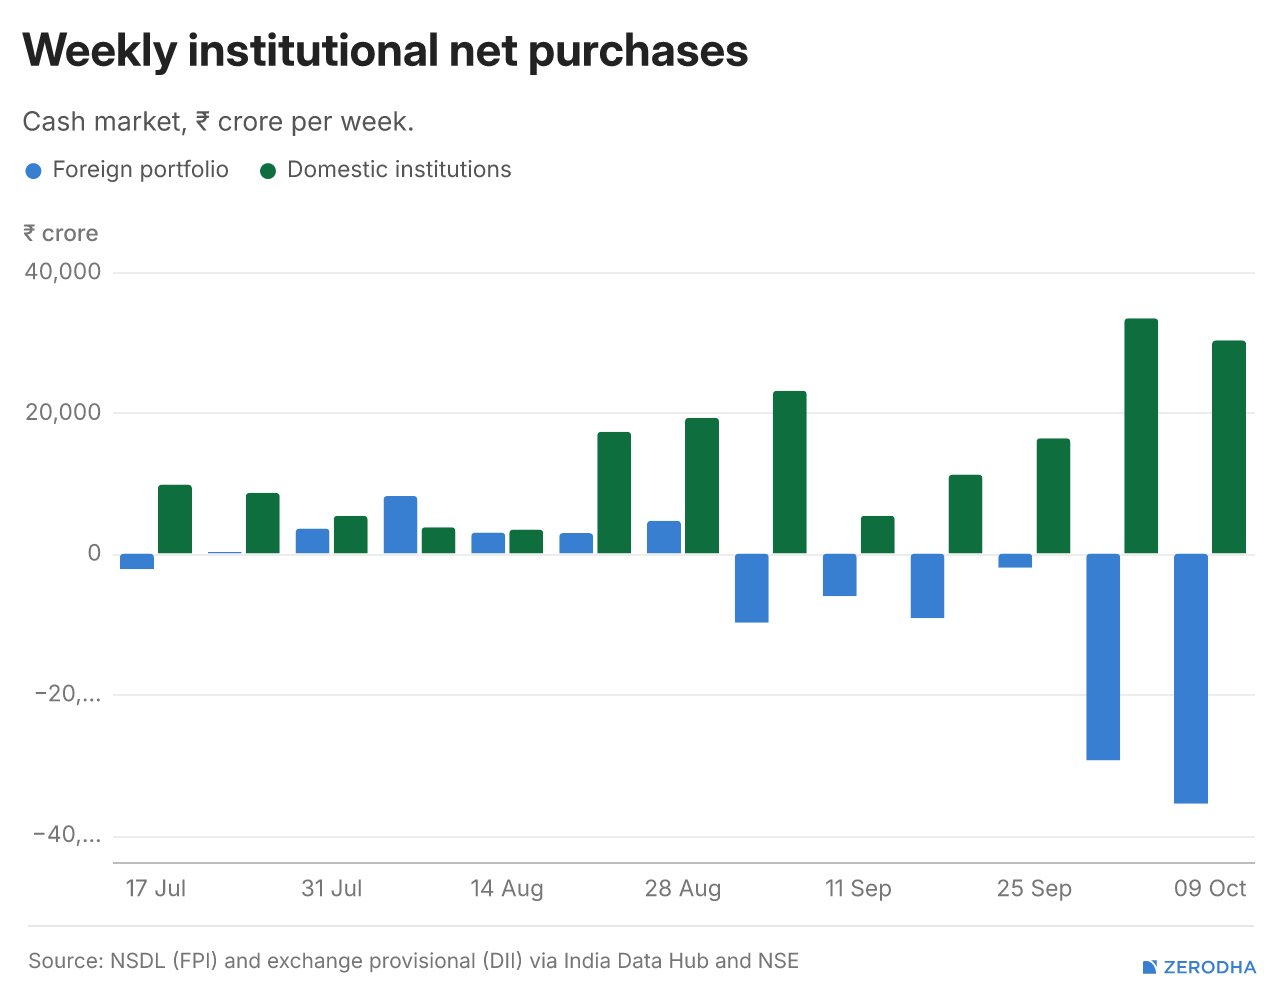
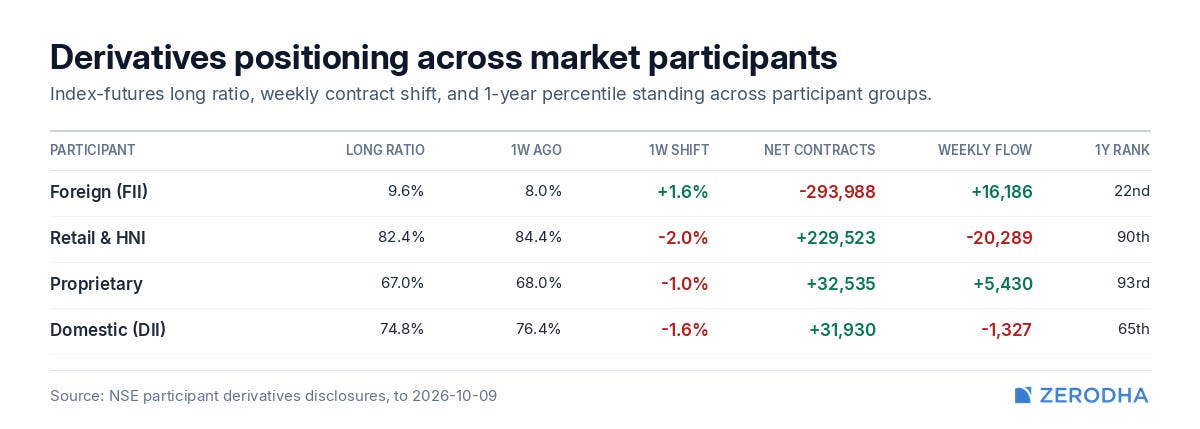
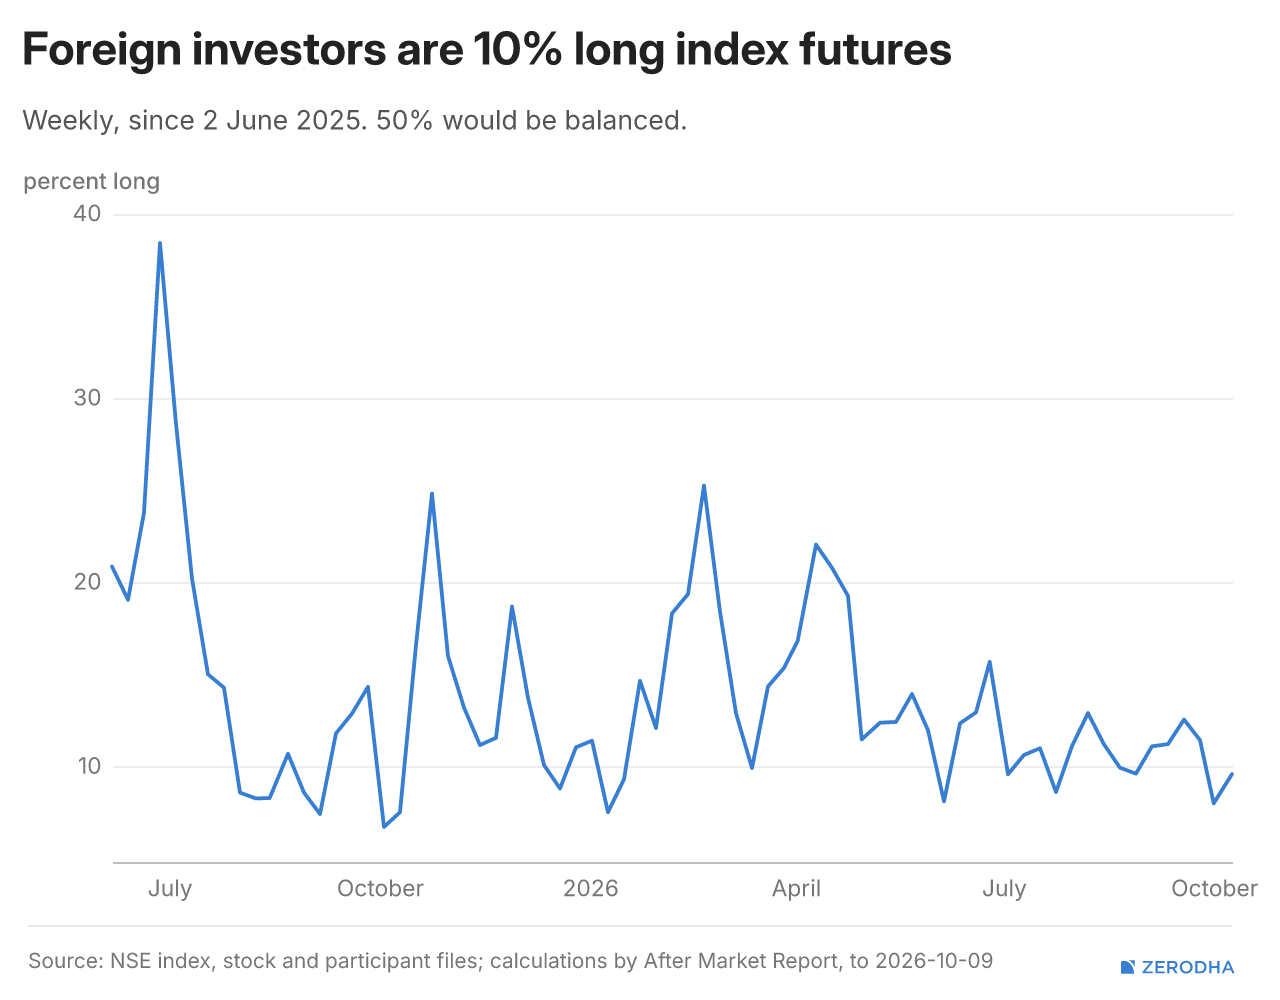
FPIs sold ₹35,556 crore during the week, while DIIs bought ₹30,313 crore, absorbing much of the selling. Over four weeks, foreign outflows totaled ₹76,187 crore, while domestic inflows totaled ₹91,398 crore.
Week ahead
Check out Weekly market metrics
We’re in Week 41 of 2026. After eight straight weeks of losses, NIFTY finally managed a modest recovery, gaining 0.44% to close at 22,520. But with the index still trading below all its key moving averages, elevated volatility, and continued pressure across broader indices, it’s too early to call a trend reversal.
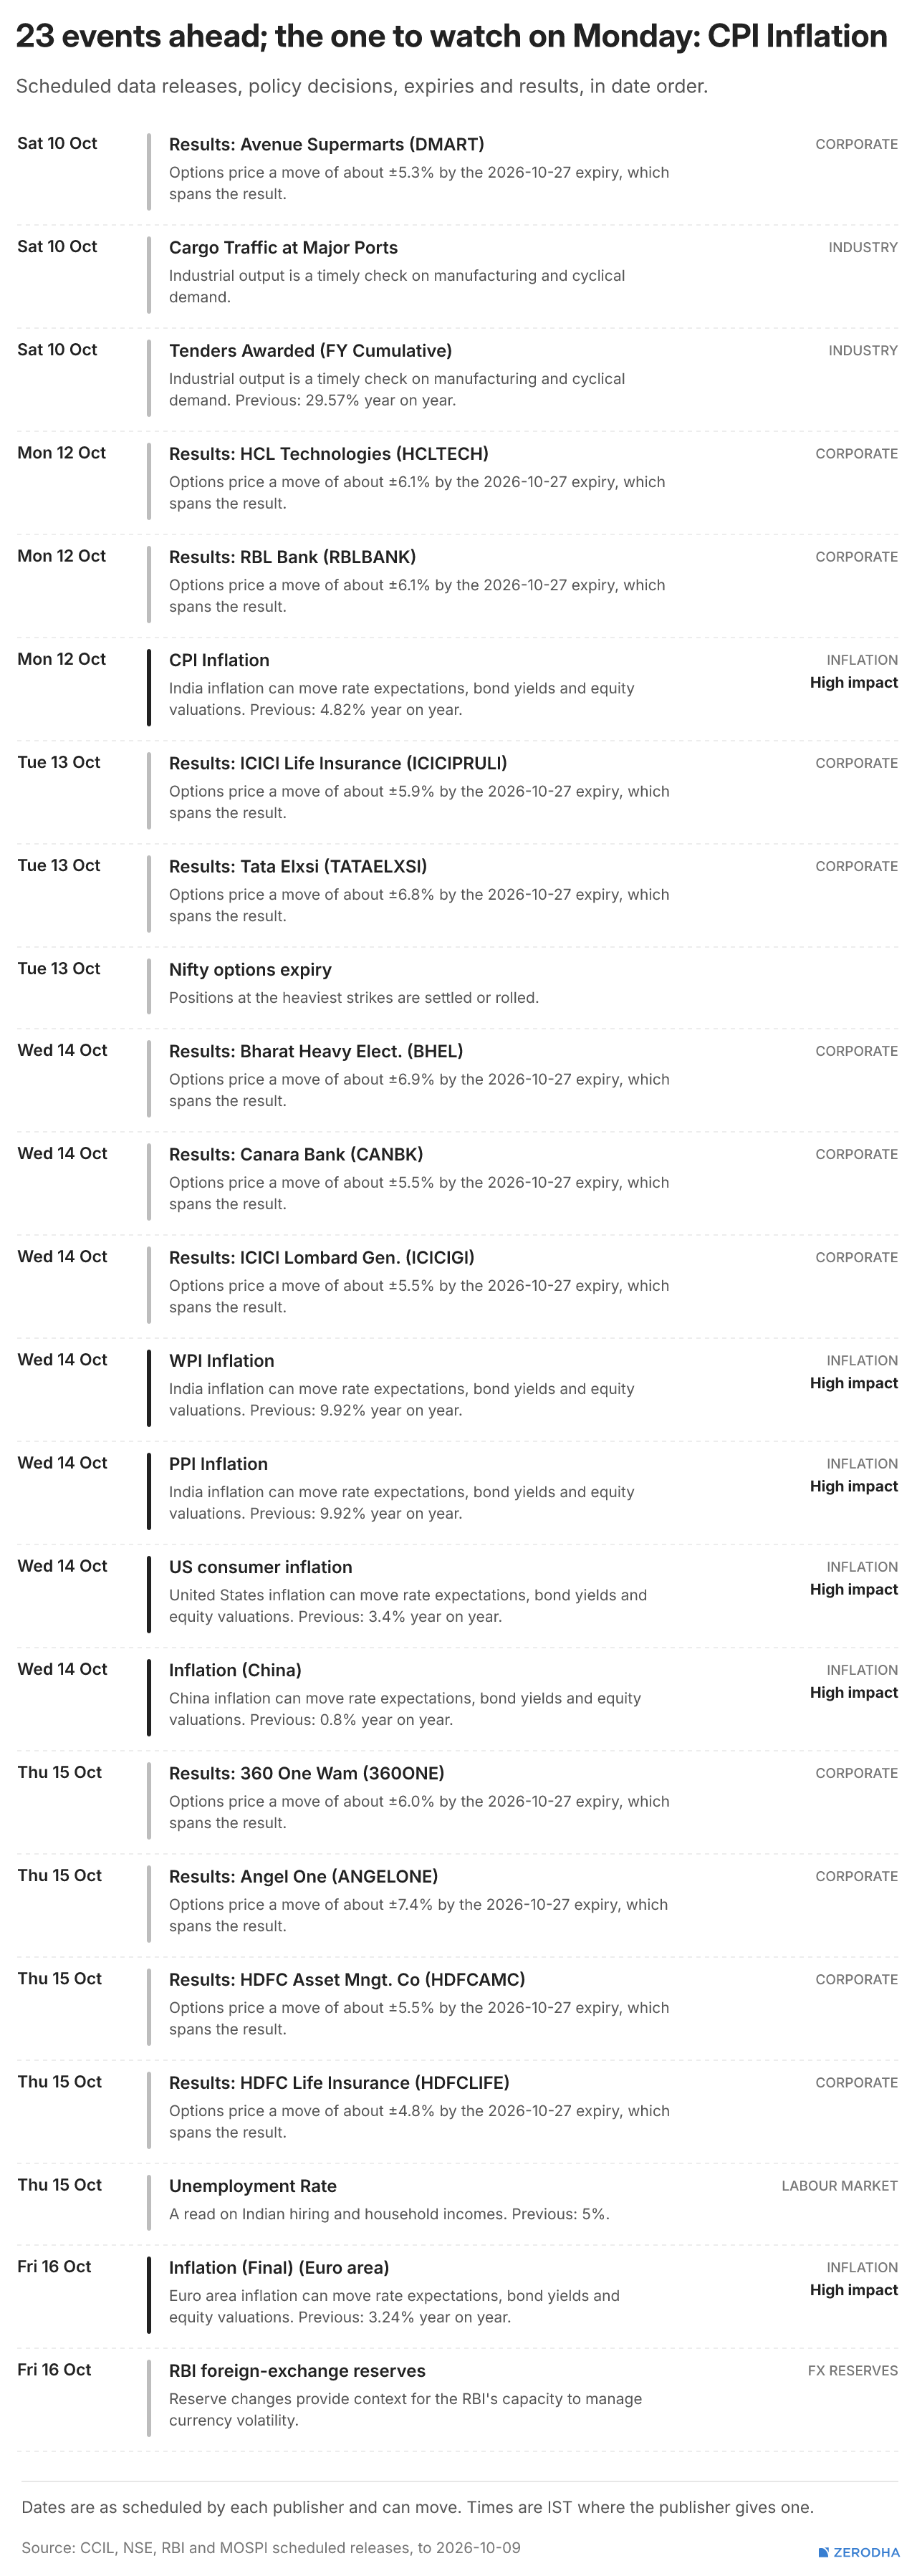
We also look at the RBI’s surprise rate hike, rising inflation concerns, US bond yields, and the key levels and events to watch in the coming week.
That’s it for this edition. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!