
Welcome to the weekly edition of Aftermarket Report, where we wrap up the week in the markets and take you through everything that mattered, both in India and globally.
Weekly market performance
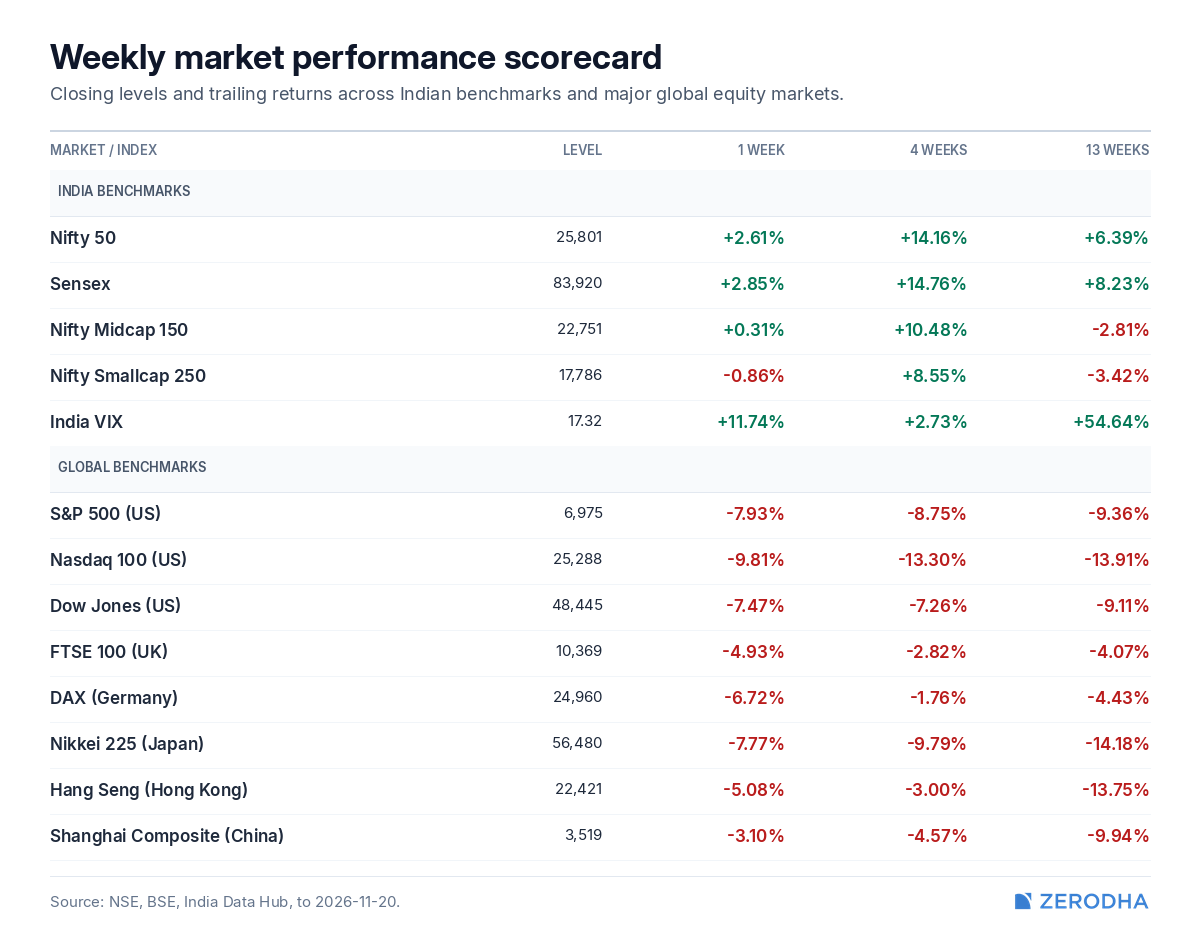
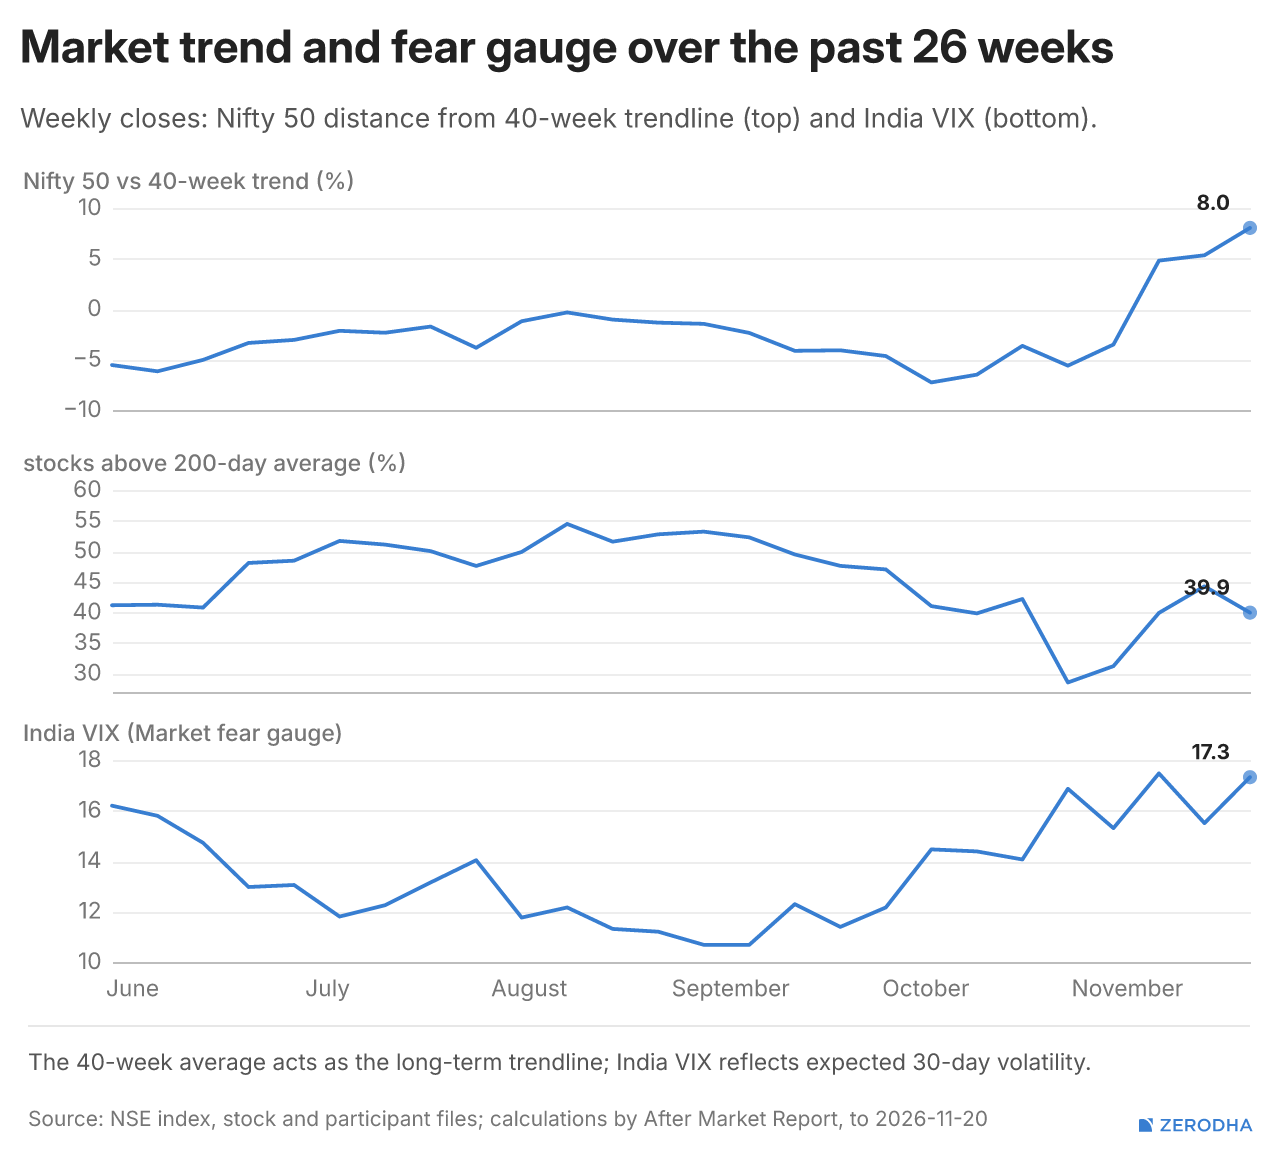
Nifty gained 2.61% for the week to close at 25,800.60, trading 8% above its 40-week moving average for the third consecutive week. However, only 39.9% of NSE stocks remain above their 200-day moving averages, while India VIX climbed to 17.32, suggesting that the broader market recovery remains incomplete.
What is the macro backdrop doing?
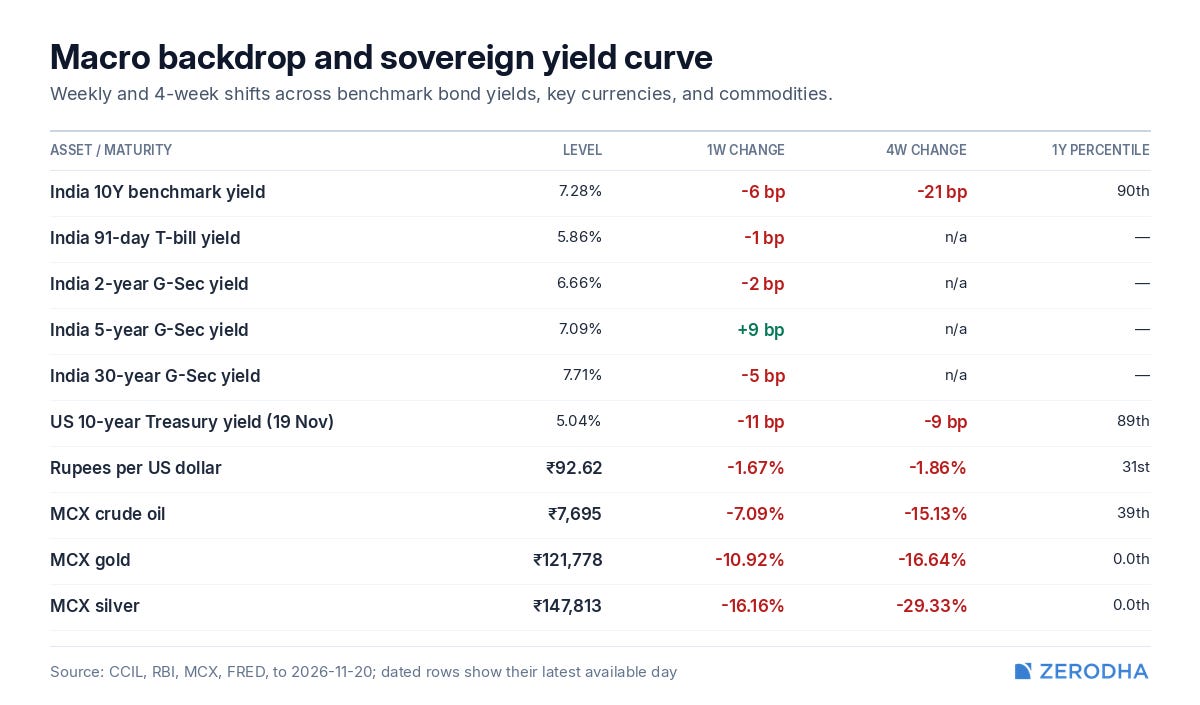
India’s 10-year government bond yield declined 6 basis points to 7.28%, while the rupee strengthened 1.67% against the dollar during the week. Commodities witnessed sharp declines, with MCX crude falling 7.09%, gold plunging 10.92% and silver dropping 16.16%, reflecting significant weakness across commodity markets.
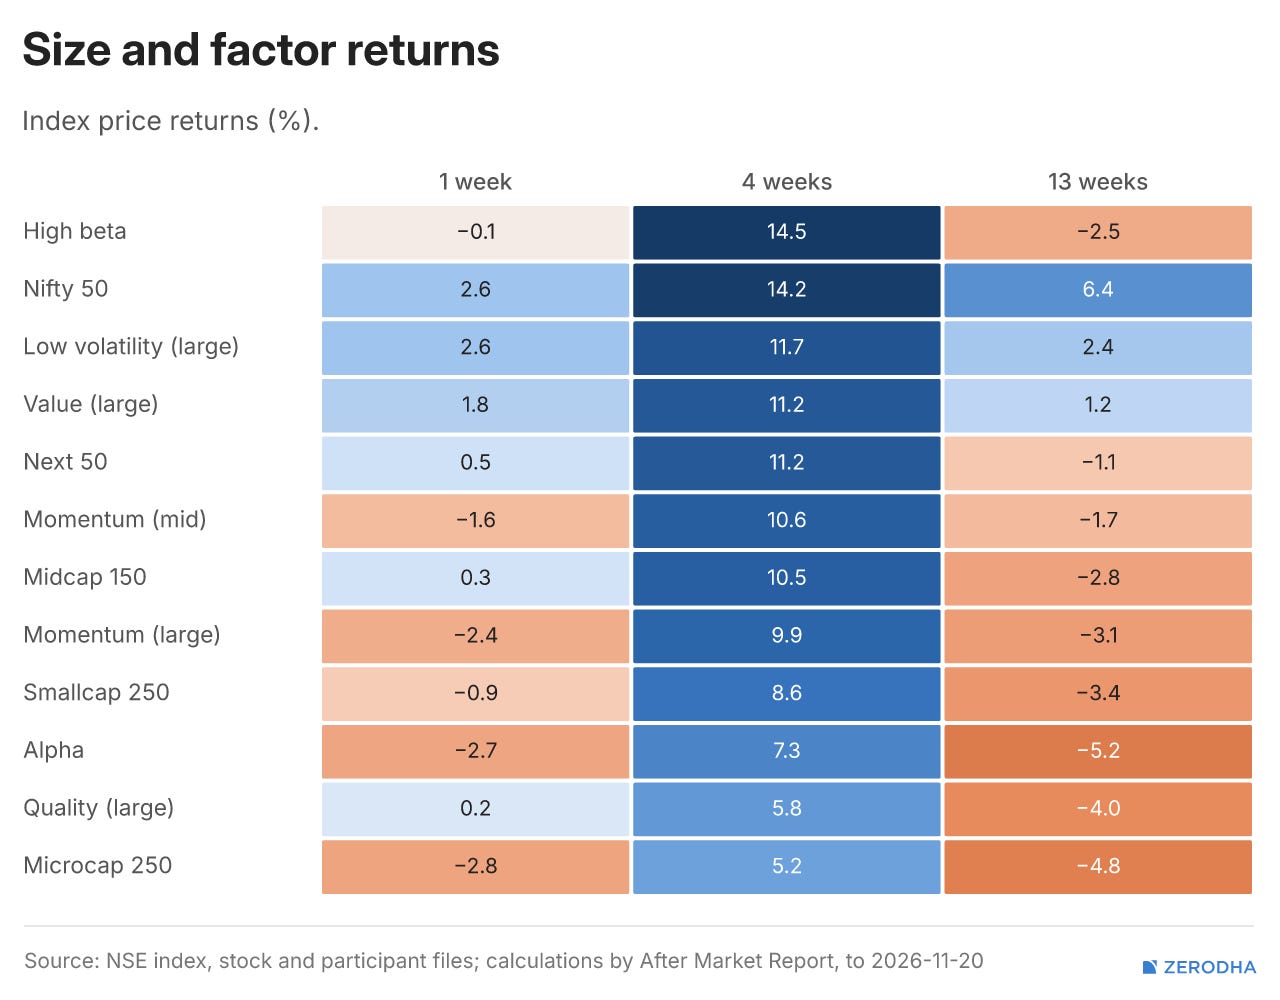
Reversal strategies outperformed momentum, with last week’s worst-performing stocks declining 1.74% compared with a 4.36% fall for the previous week’s winners. Breakouts remained unreliable, with only 29% of recent 52-week breakouts holding, while large-cap stocks continued to outperform smaller companies.
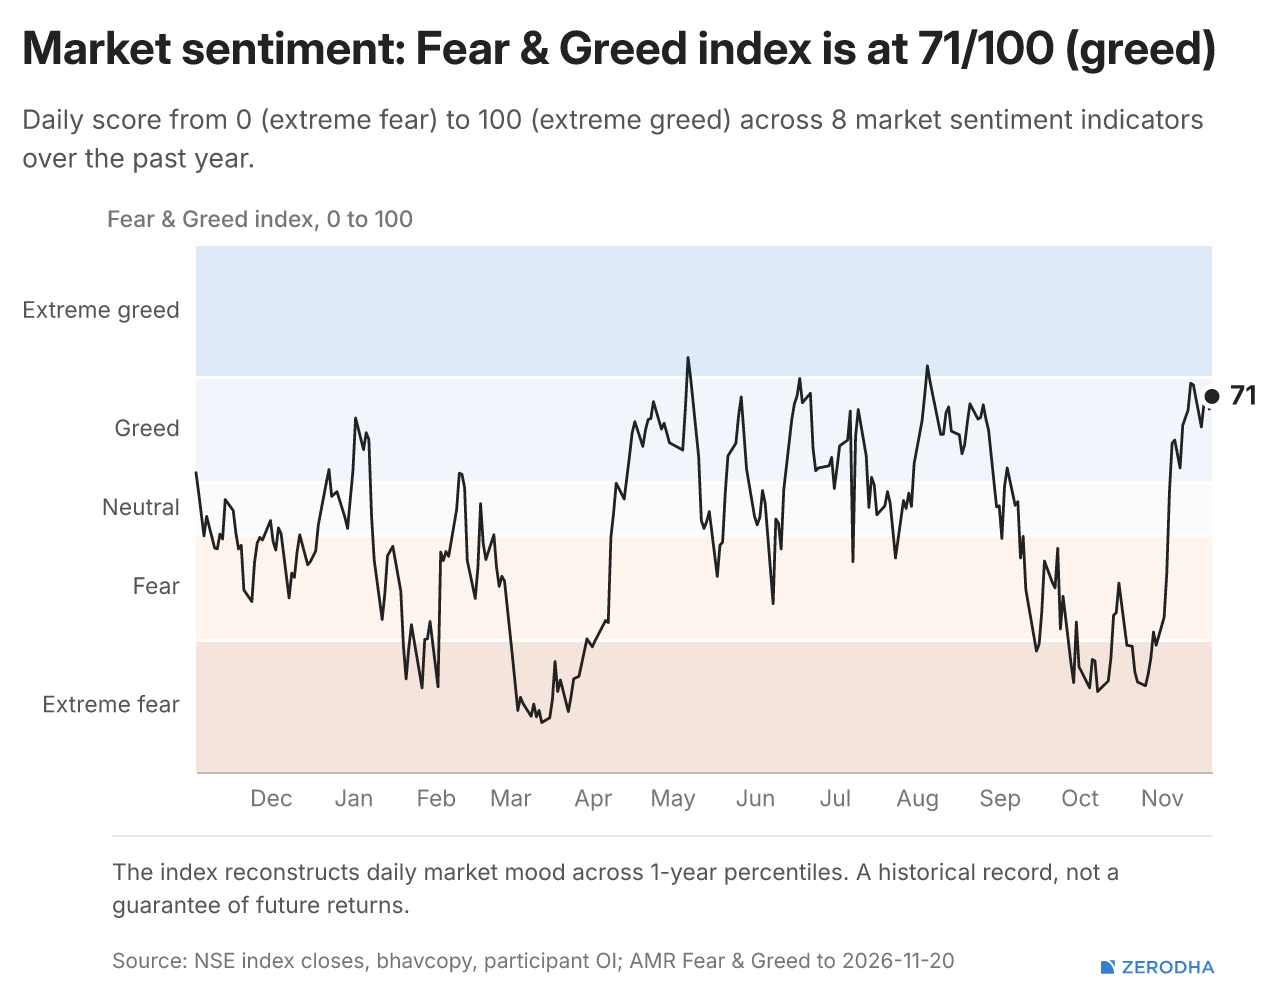
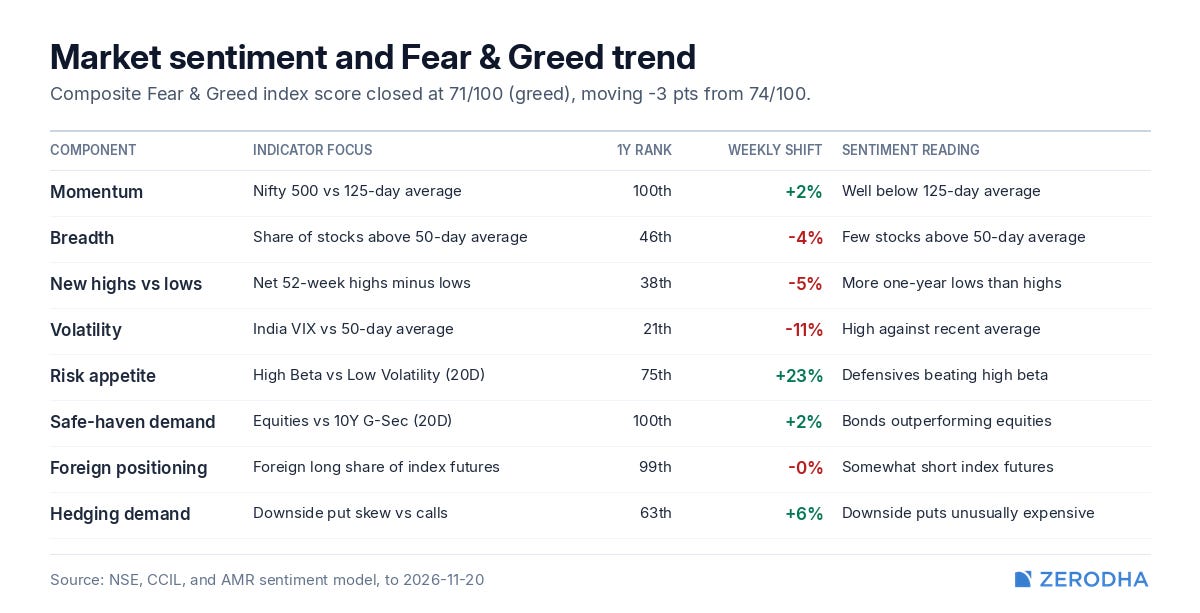
Fear & Greed trend
Market Breadth
Valuation Check
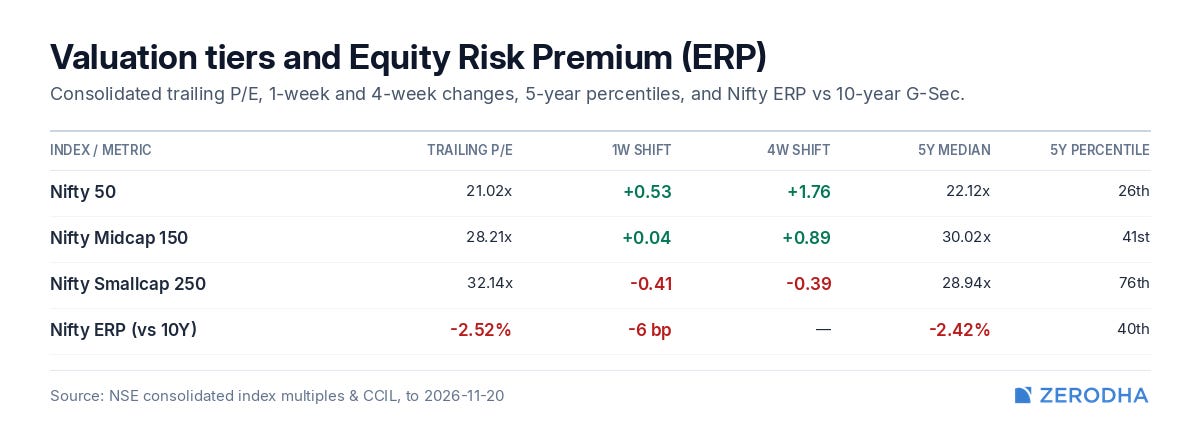
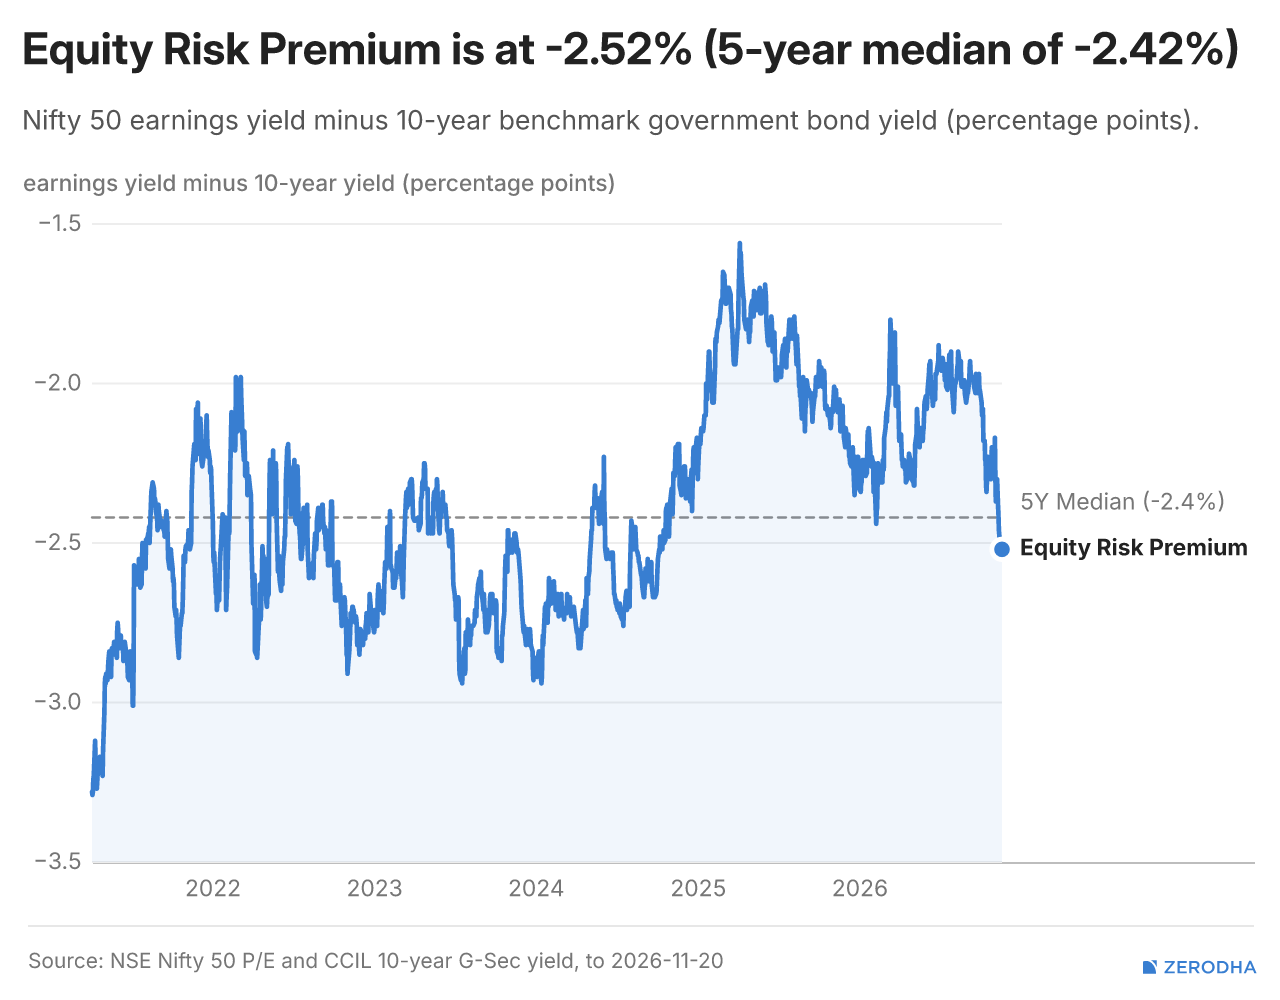
Nifty trades at 21.02× trailing earnings, placing large-cap valuations in the 26th percentile of their five-year history, while smallcaps remain relatively expensive at 32.14×. The equity risk premium stood at -2.52%, close to its five-year median, suggesting that large-cap valuations remain comparatively attractive relative to smaller companies.
Sectoral summary
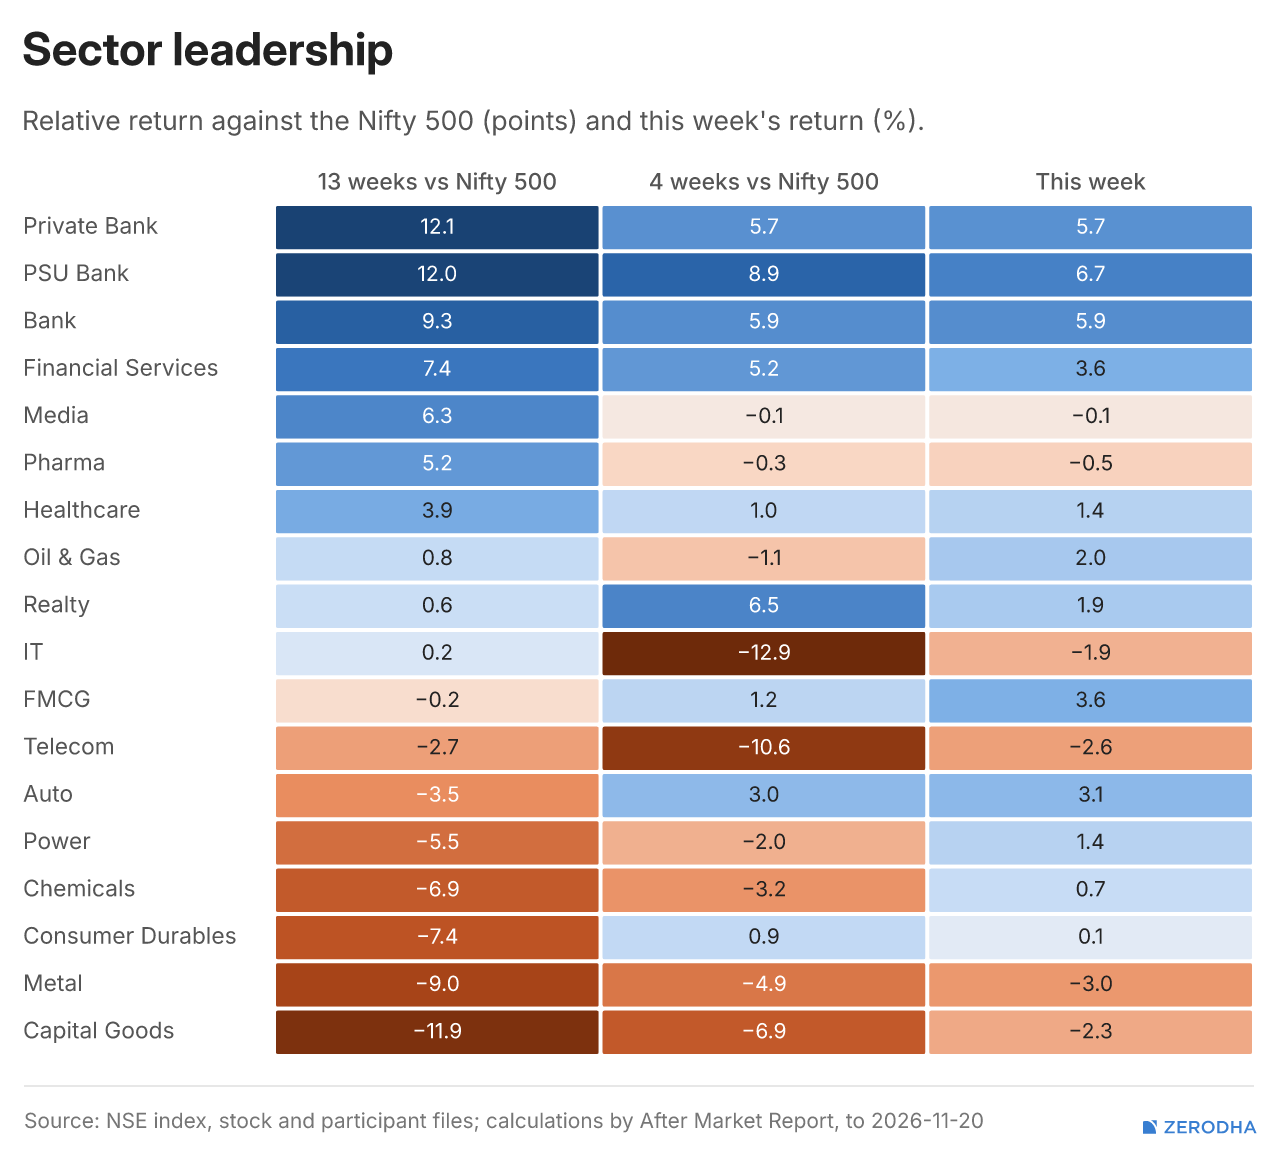
Private Banks and PSU Banks continued to lead, outperforming the Nifty 500 by 12.1 and 12 percentage points, respectively, over 13 weeks. FMCG, Auto and Consumer Durables showed improving momentum, while Media, Pharma, Oil & Gas and IT weakened, highlighting an ongoing rotation in sector leadership.
Selective stock screeners
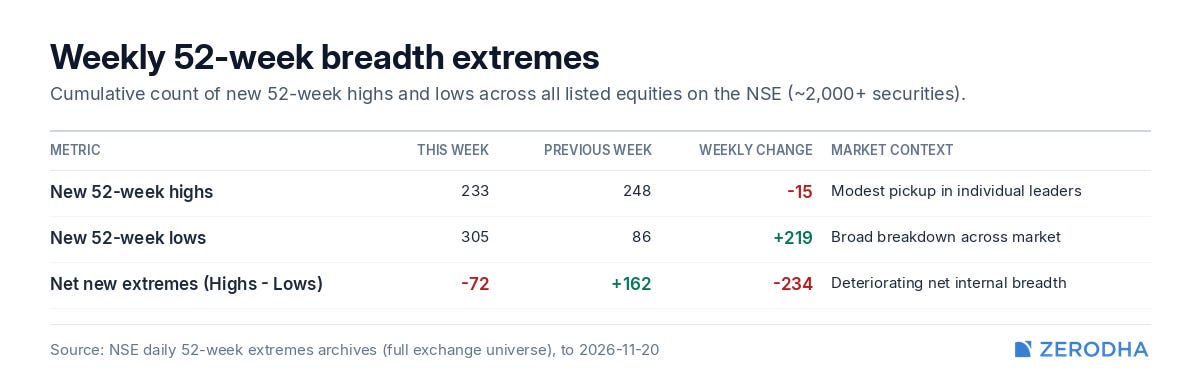
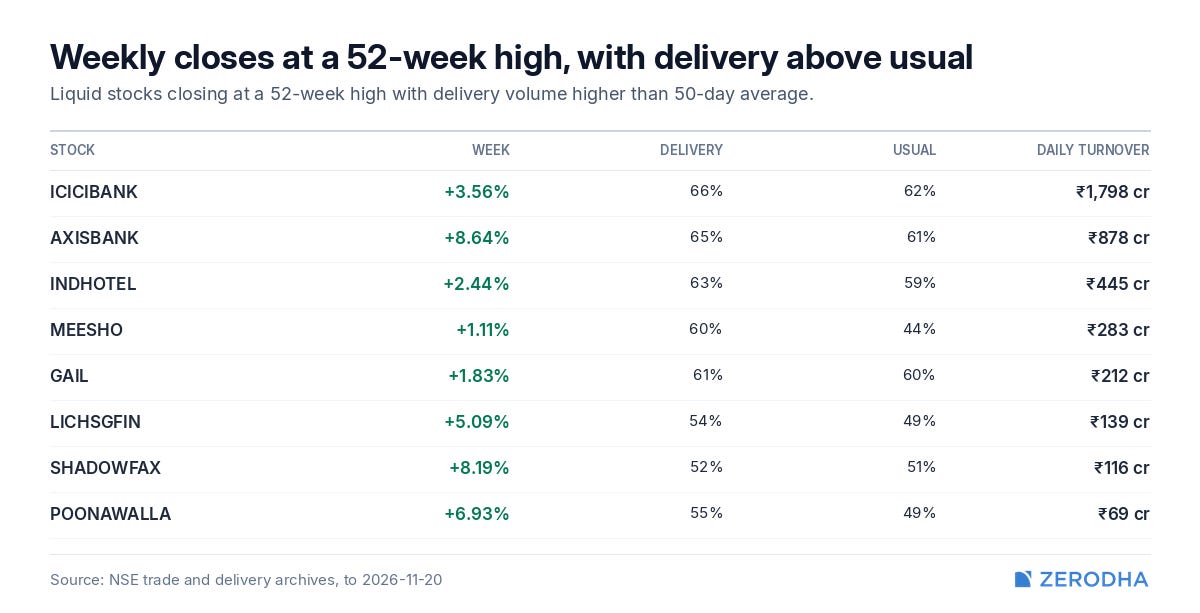
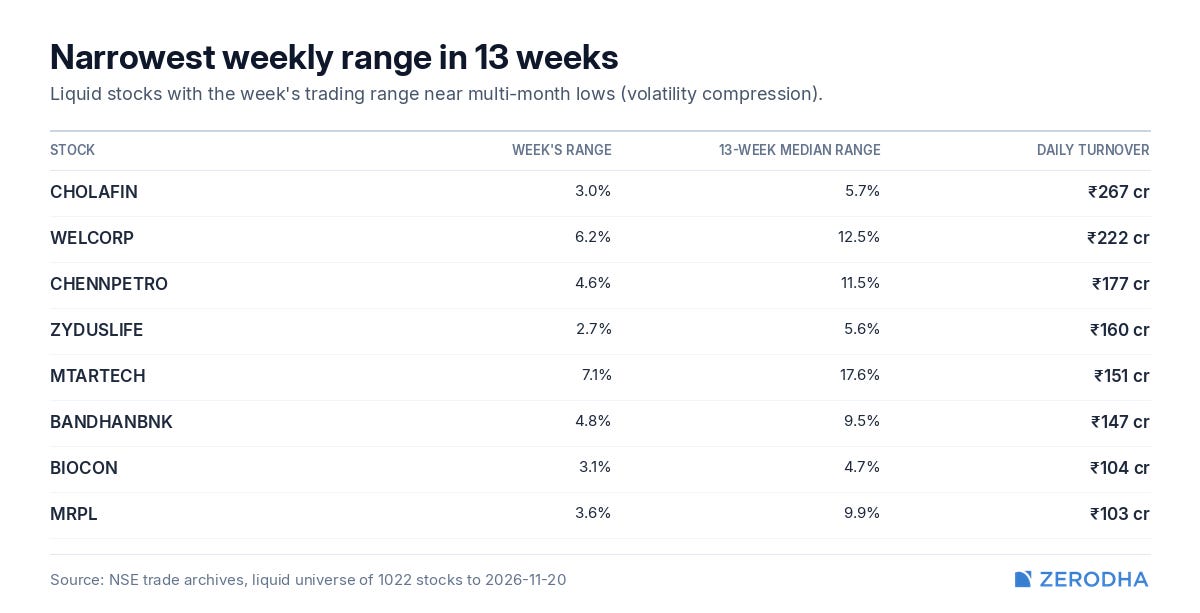
Among 1,022 tracked liquid stocks, 30 ended the week at fresh 52-week closing highs, with eight recording above-average delivery volumes. Another eight stocks registered their narrowest weekly trading ranges in 13 weeks, suggesting potential breakout setups, although the direction remains uncertain.
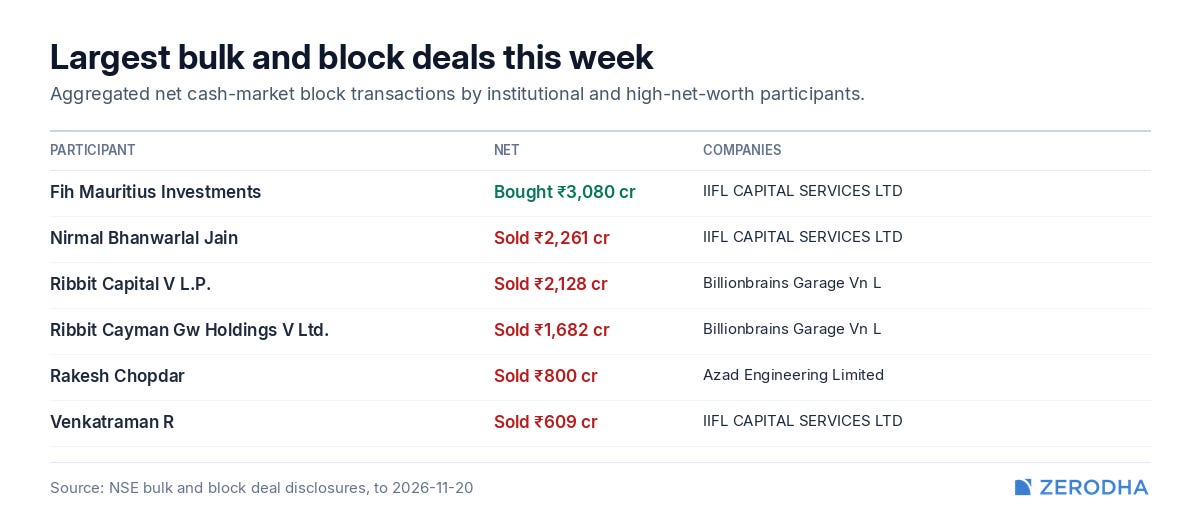
Deals of the week
Institutional flows & positioning
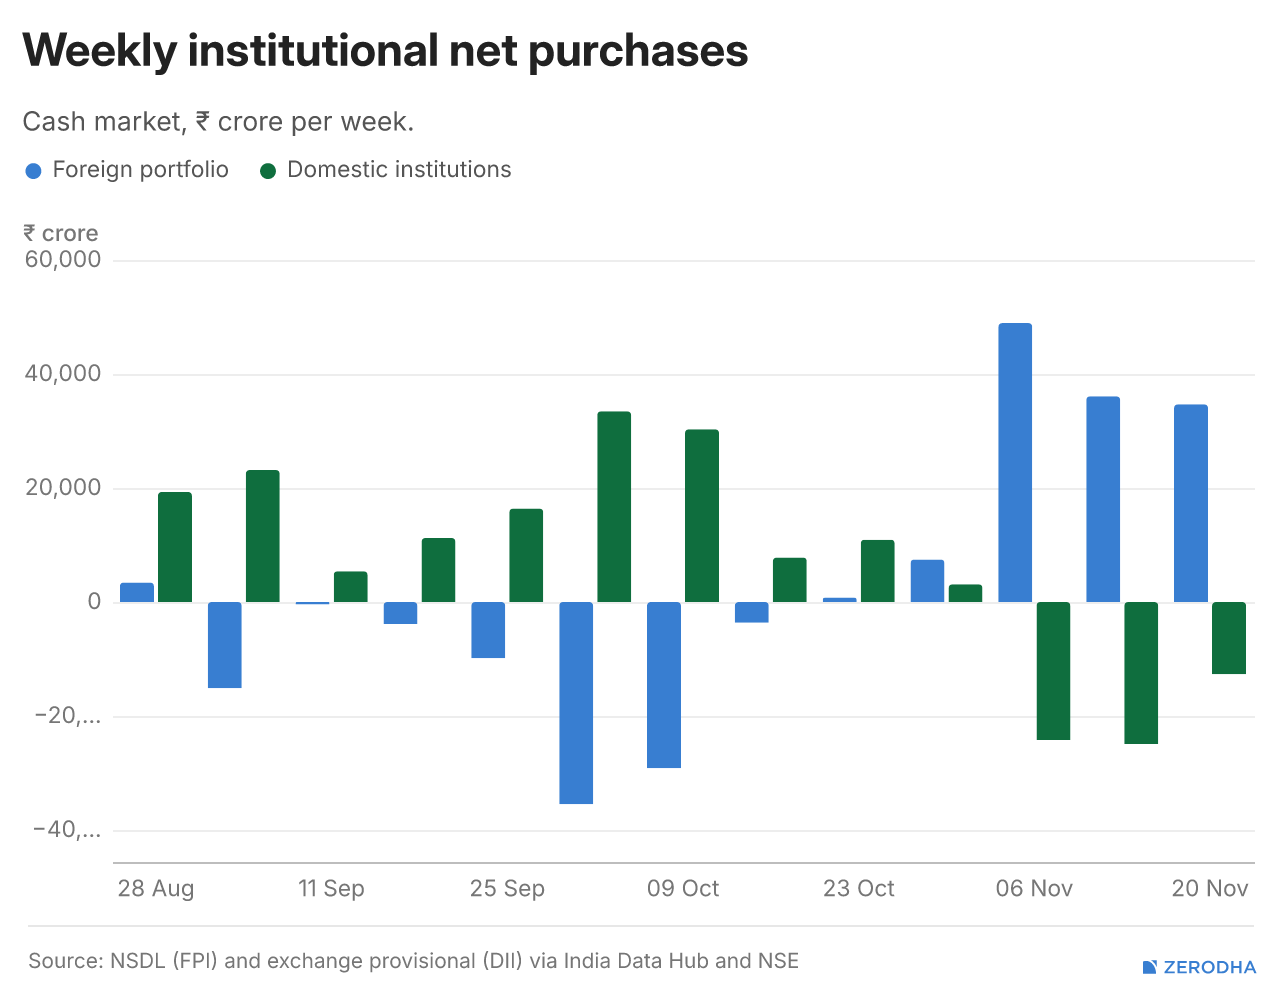
Foreign investors bought ₹34,686 crore worth of Indian equities during the week, while domestic institutions sold ₹12,698 crore. Over the past four weeks, FPIs have invested ₹1.27 lakh crore, against DII selling of ₹58,677 crore, indicating a significant shift in institutional flows.
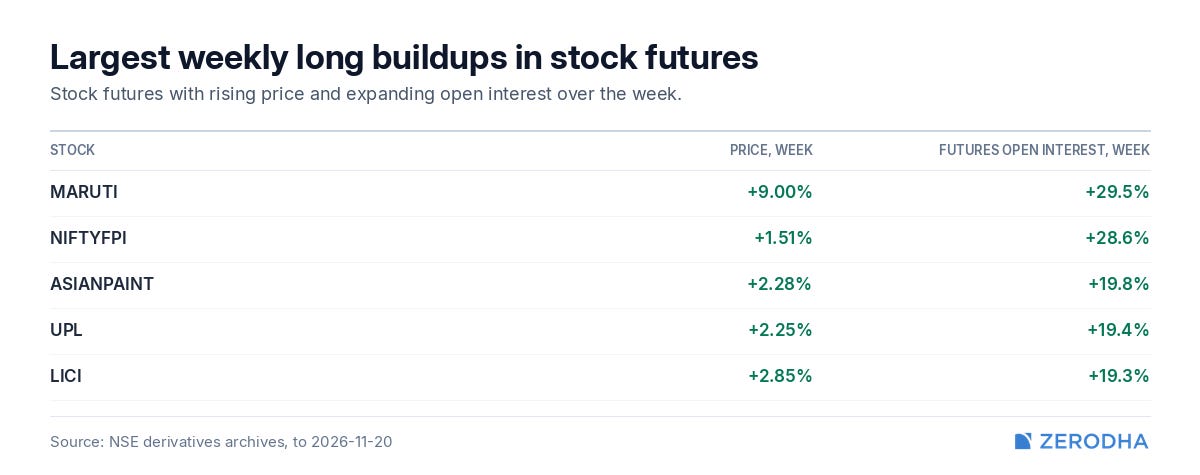
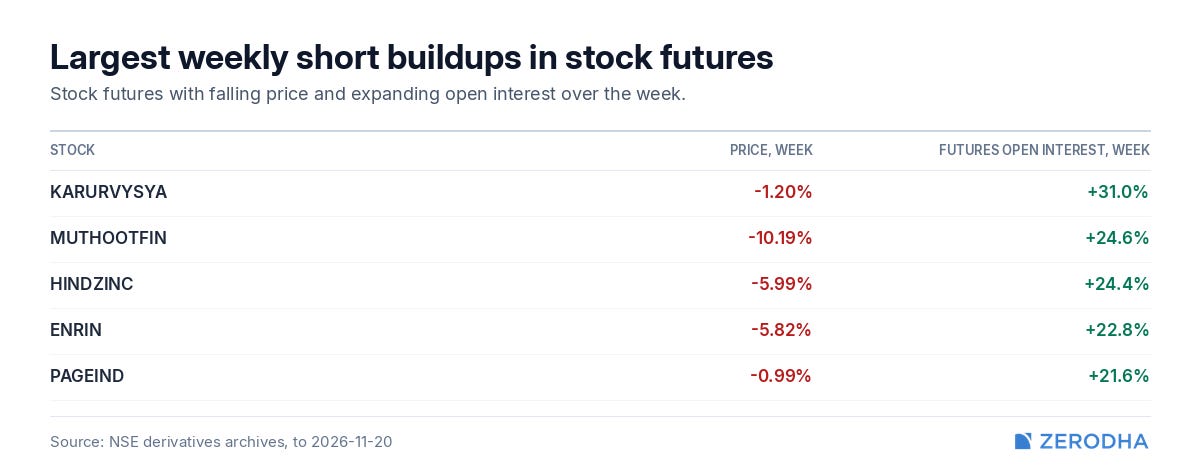
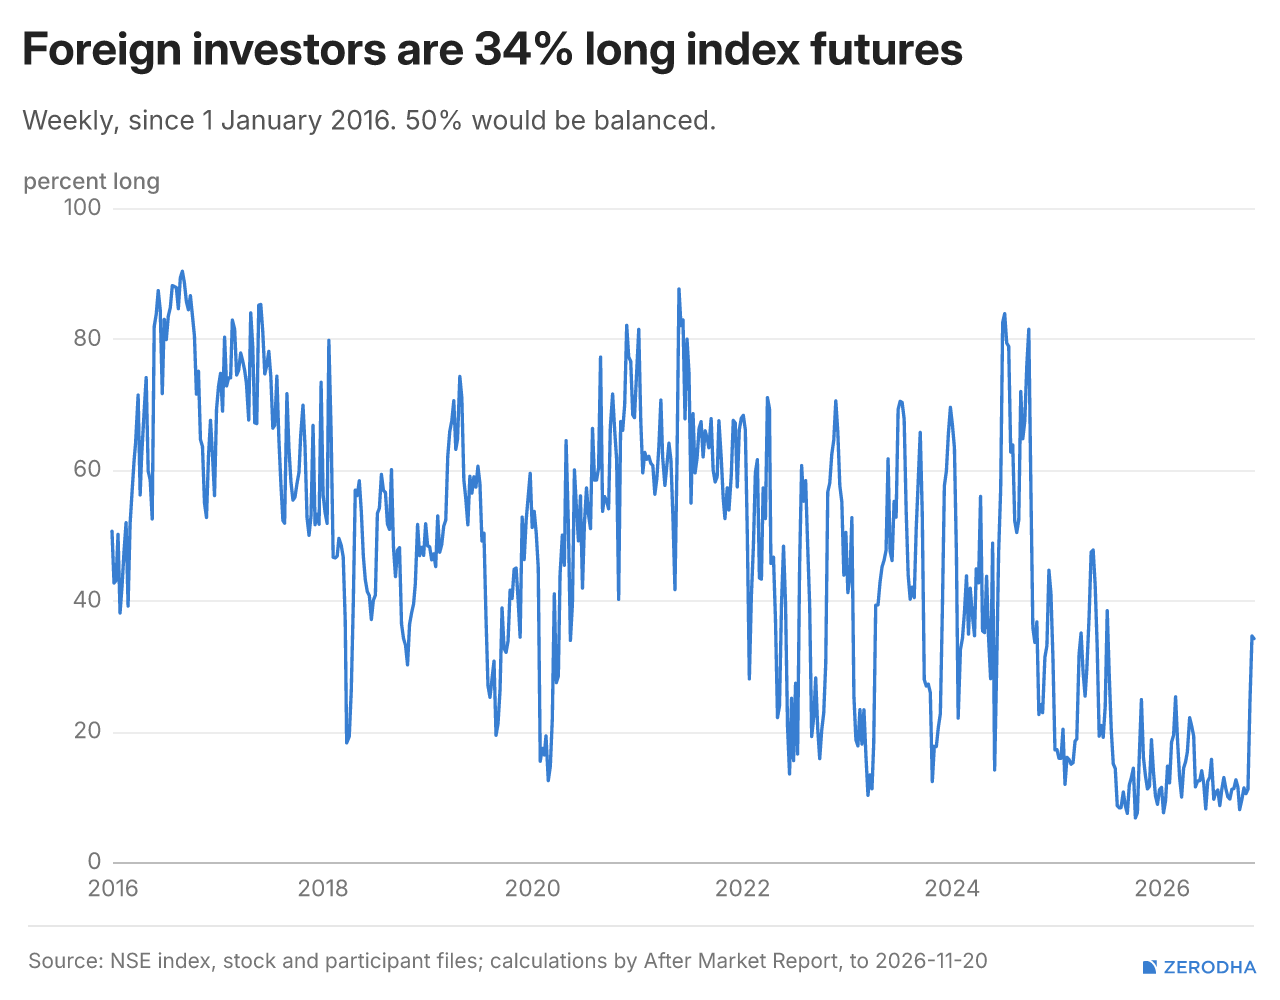
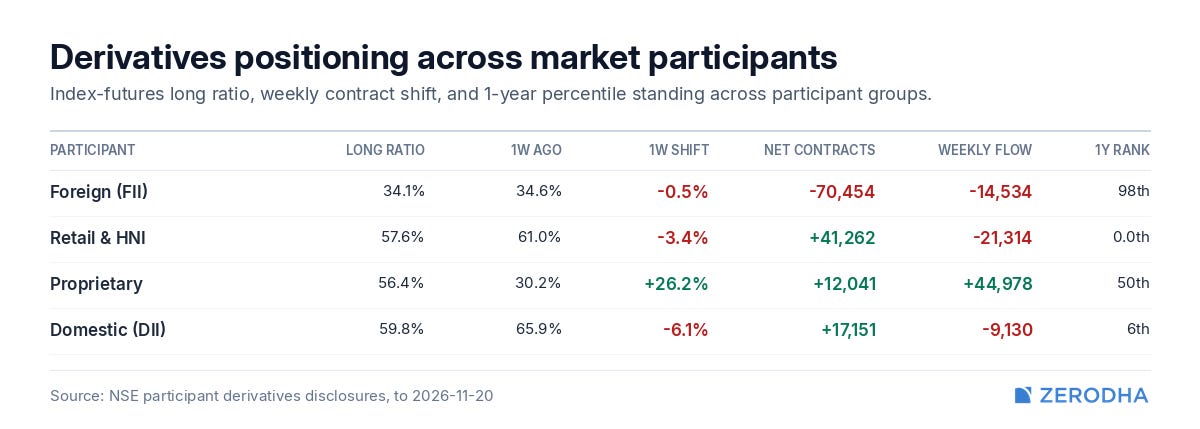
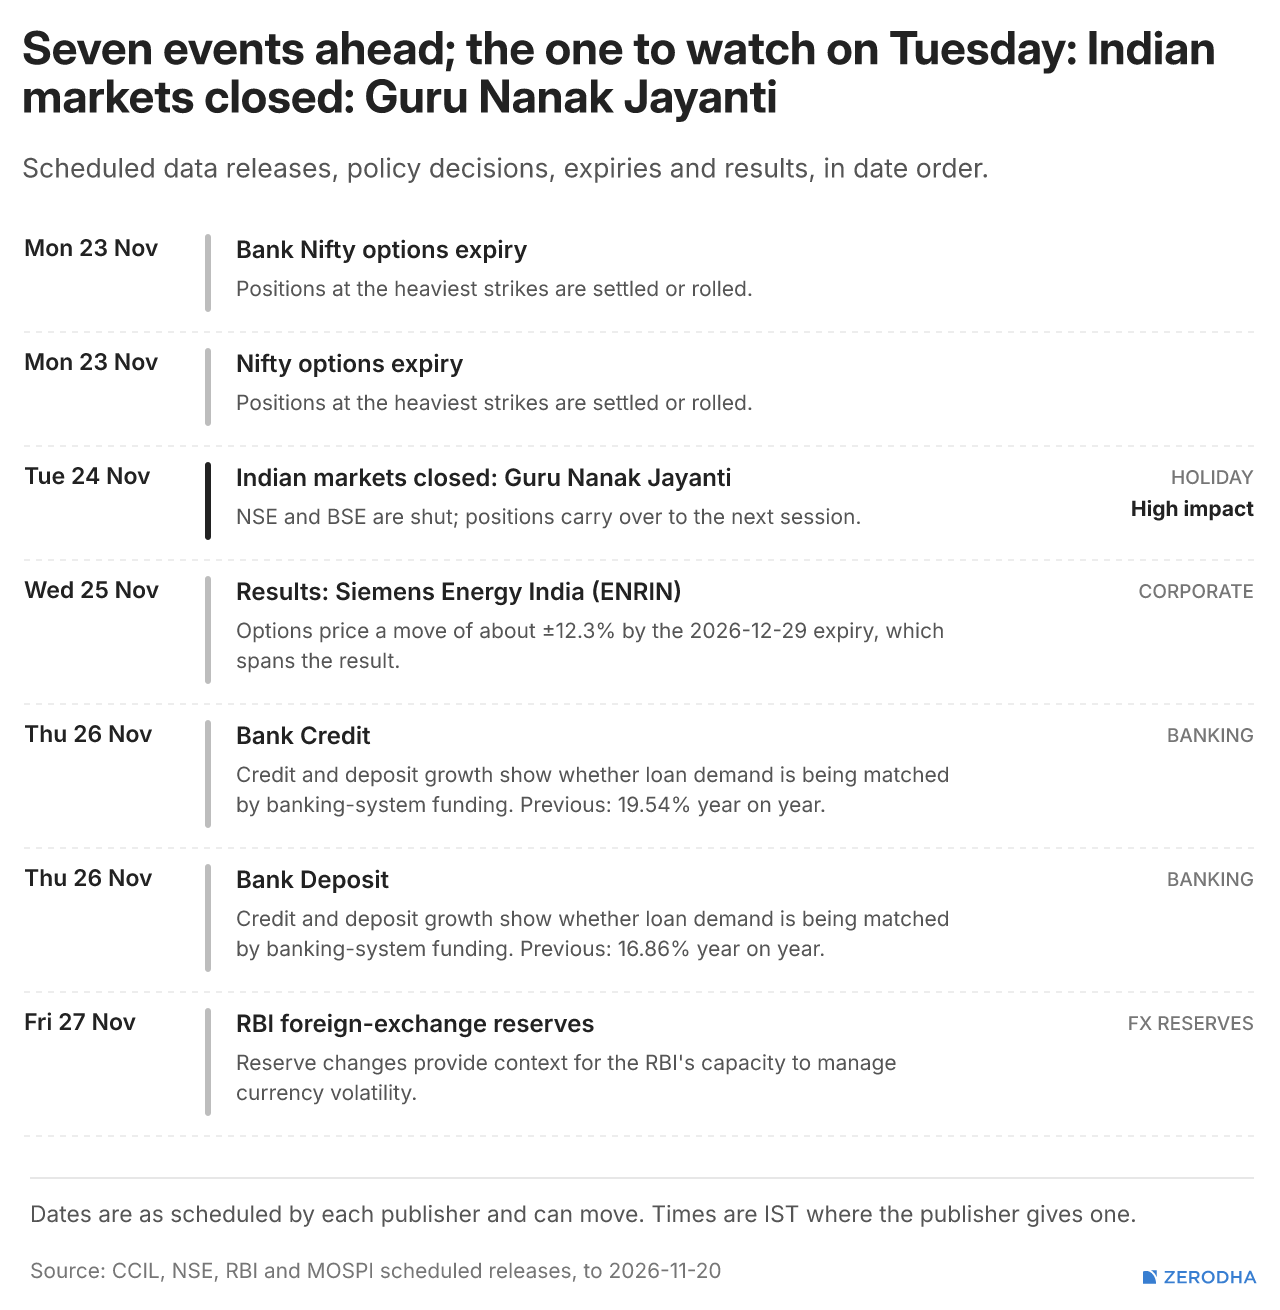
Options are pricing a ±0.90% move in Nifty by November 23, while implied volatility declined from 13% to 12.4%, benefiting option sellers. FIIs increased their net short index-futures positions to 70,454 contracts, while retail and HNI participants remained net long, and short covering dominated single-stock futures.
Week ahead
Check out Weekly market metrics
We’re in Week 47 of 2026, with just six weeks left in the year. Indian markets extended their recovery for the fourth consecutive week, with NIFTY gaining 2.6% to close at 25,801, just 2% away from its all-time high. Bank NIFTY was the standout performer, gaining nearly 6% and hitting a fresh all-time high.
But there's more to this week's story. We take a closer look at the record FII buying in November and why headline investment figures can be misleading when viewed without adjusting for the growing size of India's stock market. We also look at the pickup in volatility, the sharp correction in gold and silver, and what the options market is pricing in ahead of the monthly expiries.
With the broader market showing renewed strength, the key question now is whether NIFTY can sustain its momentum and move past its previous highs. Let's break it all down.
That’s it for this edition. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!