
Welcome to the weekly edition of Aftermarket Report, where we wrap up the week in the markets and take you through everything that mattered, both in India and globally.
What data points and transformations do you want to see?
We’re also experimenting with a weekly edition of the Aftermarket Report, and we’d love to know what you’d find useful in it.
Unlike the daily report, the idea here is to step back from individual trading sessions and look at the bigger picture — what changed over the week, where trends are building, how sectors and themes are moving, how positioning has shifted, and what the data tells us when viewed over a longer timeframe.
We’re exploring everything from weekly market breadth, sector and thematic trends, F&O positioning and flows to volatility, commodities, global markets, and more. But we want to know what you would like to track.
What data points, transformations, ratios, comparisons, charts, or indicators would make a weekly market wrap genuinely useful for you?
Tell us what you’d like to see. Your feedback will help us shape the weekly edition of the Aftermarket Report.
Weekly market performance
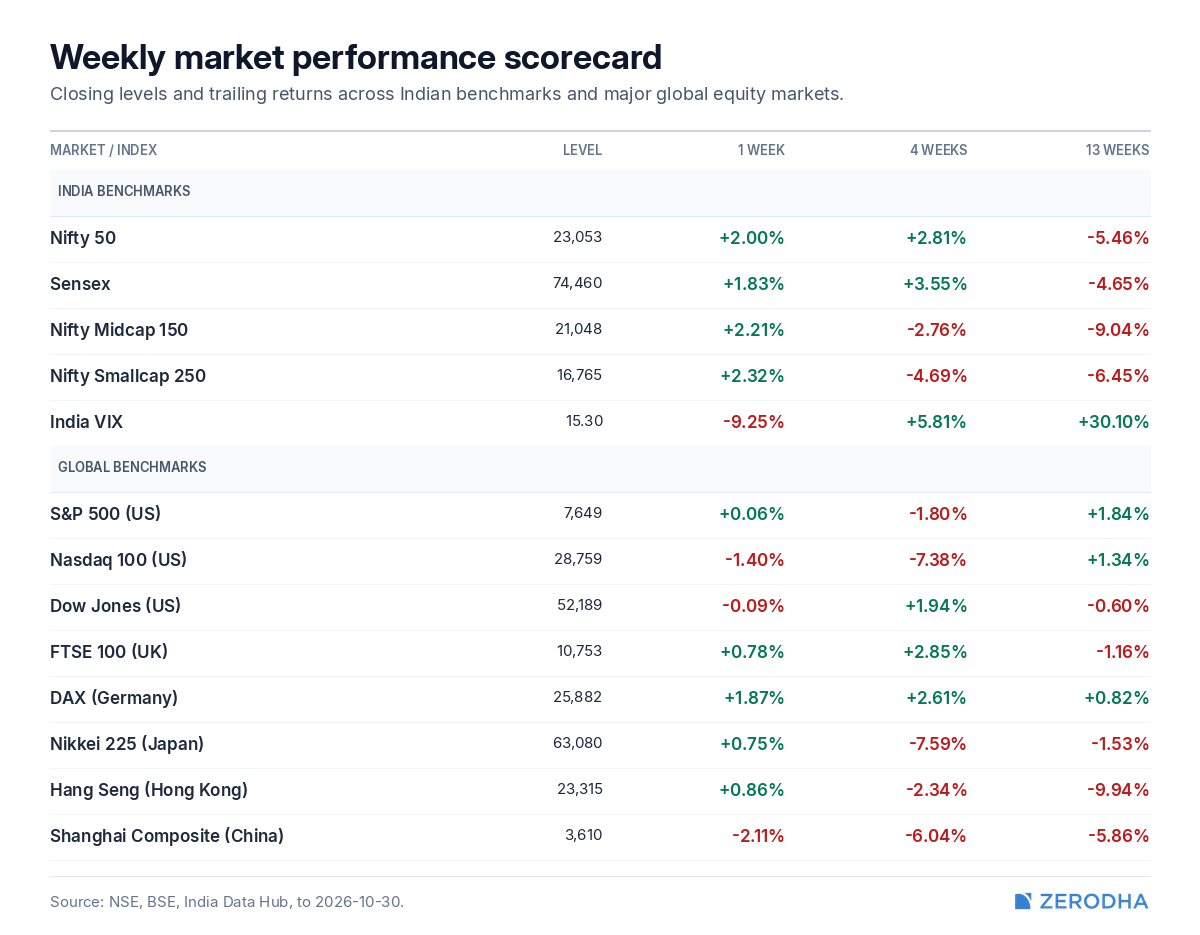
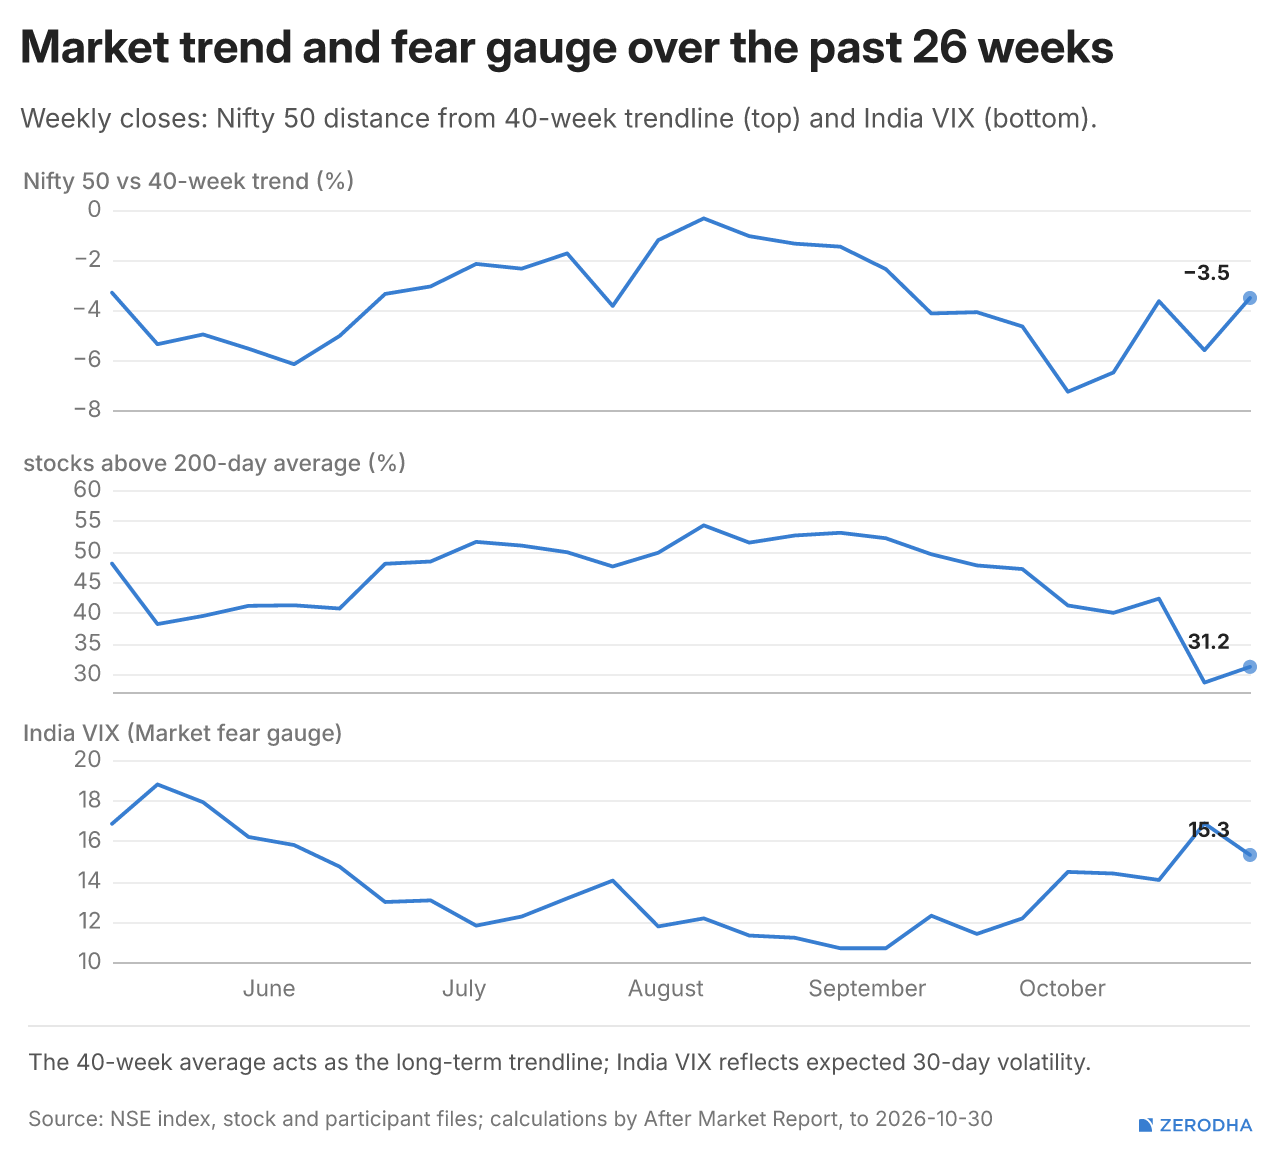
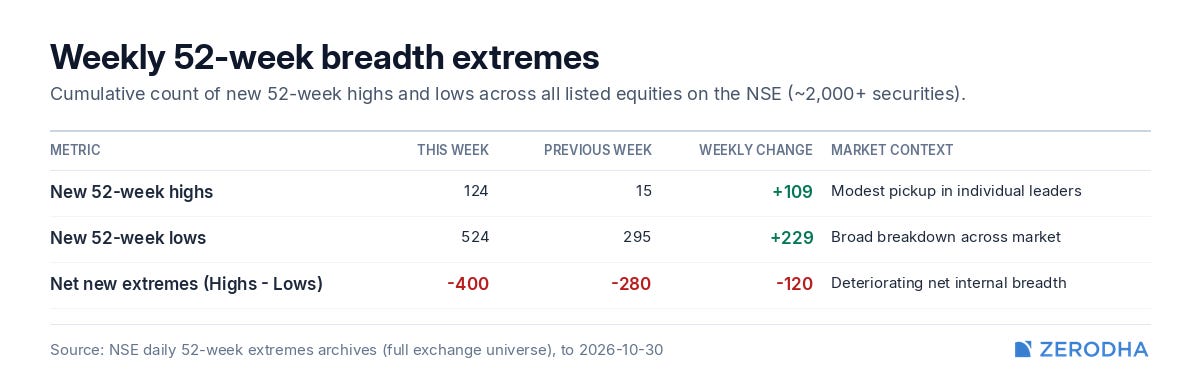
Nifty gained 2% for the week to close at 23,053, despite continued weakness in the broader market. India VIX eased to 15.30, while foreign and domestic institutions bought a combined ₹9,866 crore. However, 524 stocks hit fresh 52-week lows, while only 124 made new highs, highlighting persistent underlying weakness.
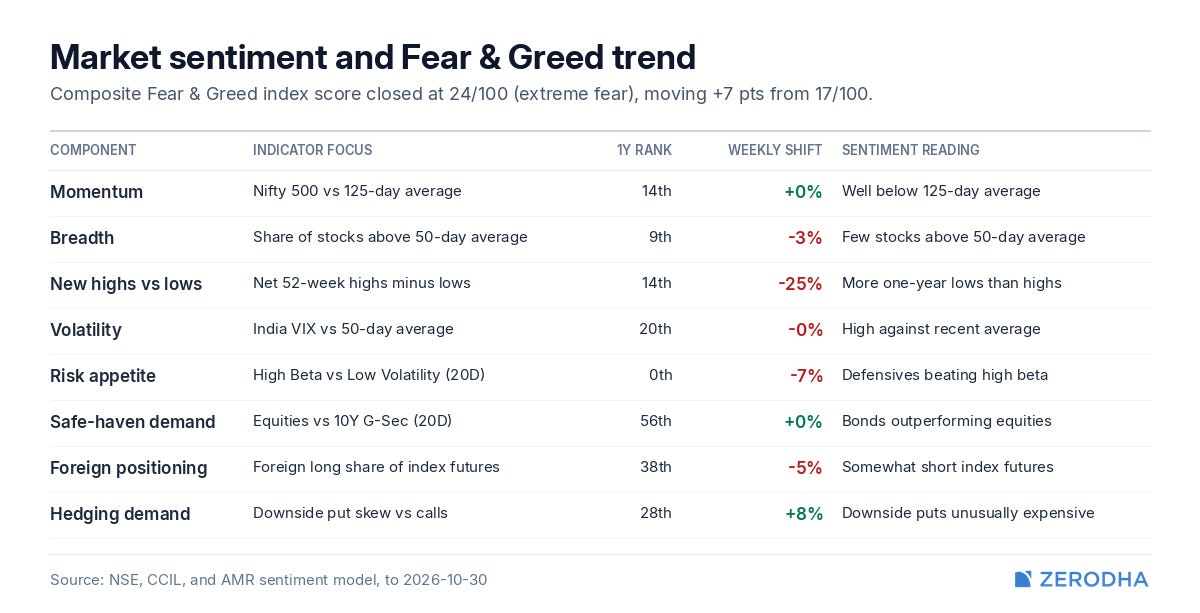
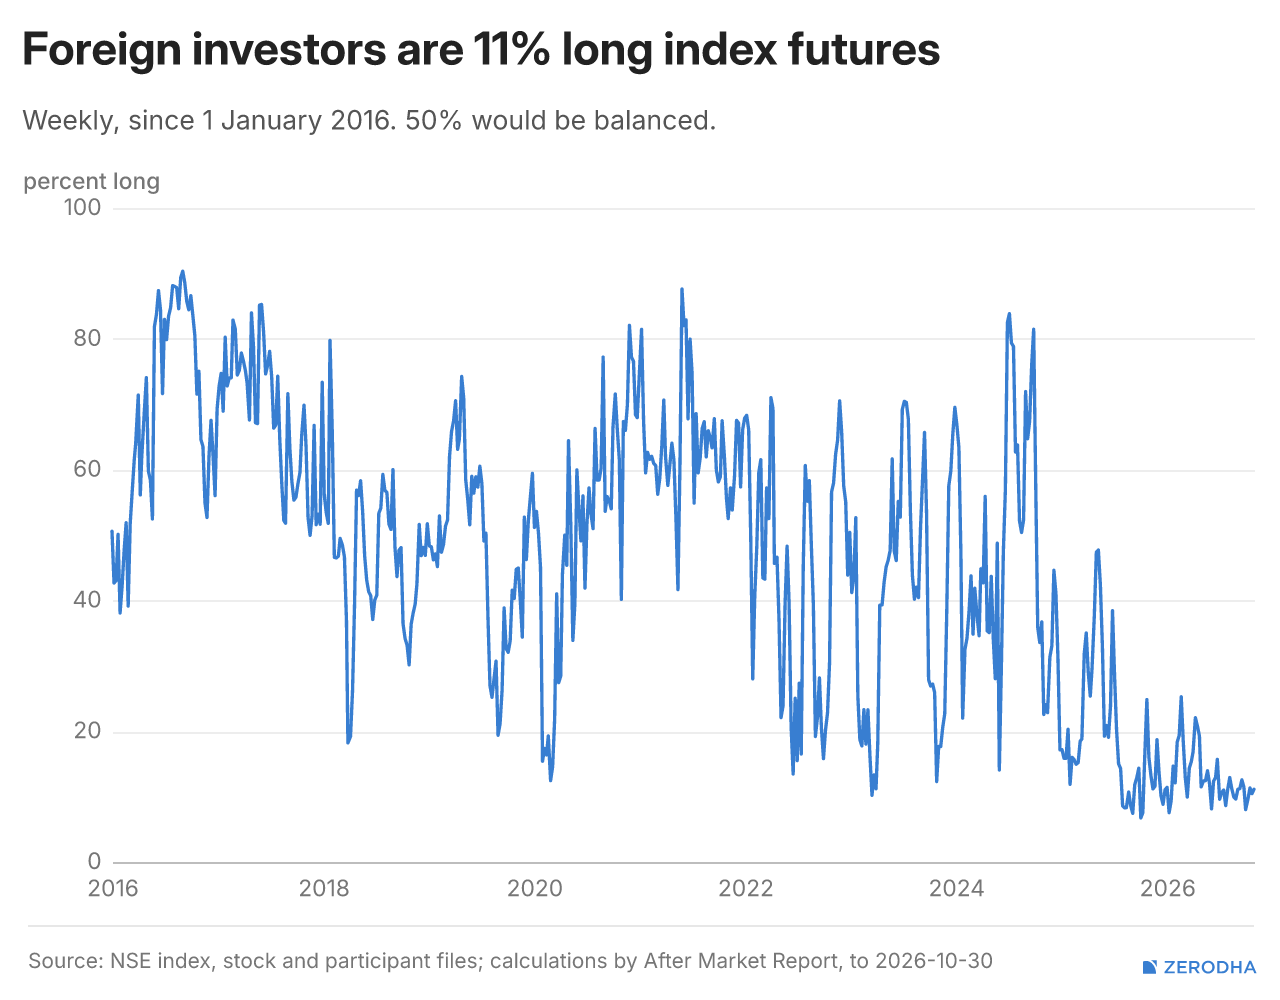
Despite the weekly recovery, the broader market remains in a downtrend, with Nifty trading 3.5% below its 40-week moving average. Only 31.2% of NSE stocks are above their 200-day average, while foreign investors remain heavily short-positioned in index futures.
What is the macro backdrop doing?
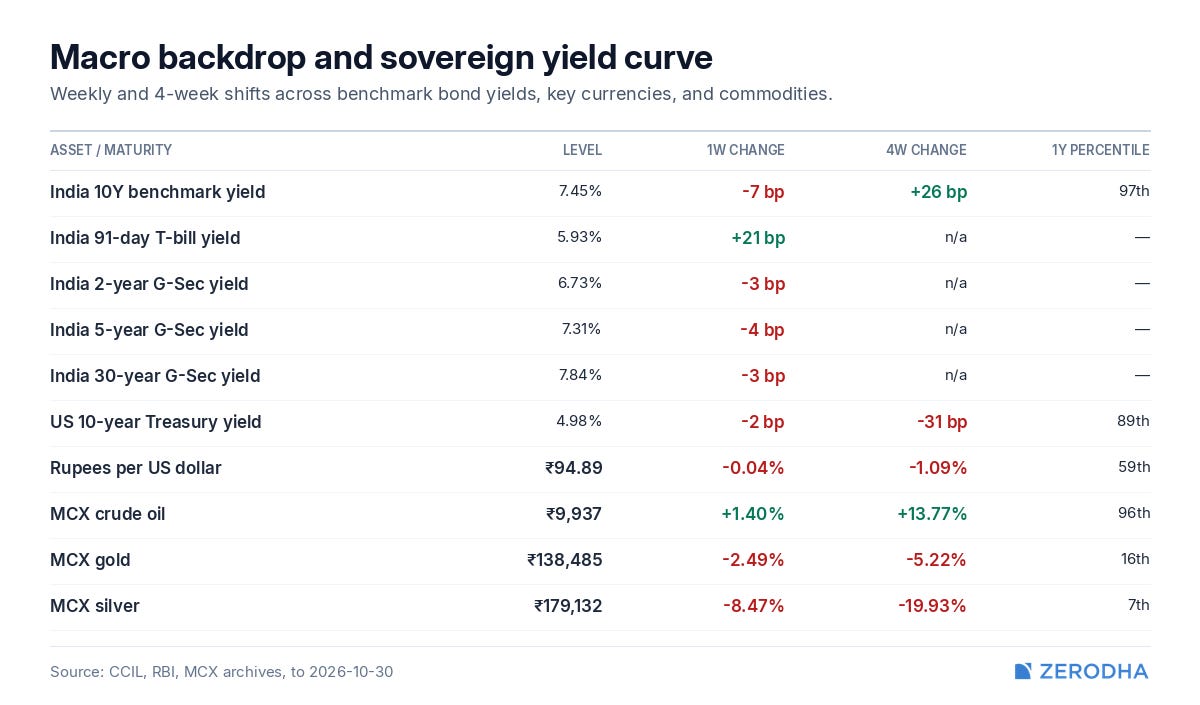
India’s 10-year bond yield declined 7 basis points to 7.45%, while the rupee traded at ₹94.89 against the dollar. Crude oil gained 1.4% during the week and nearly 14% over four weeks, while gold and silver declined 2.49% and 8.47%, respectively.
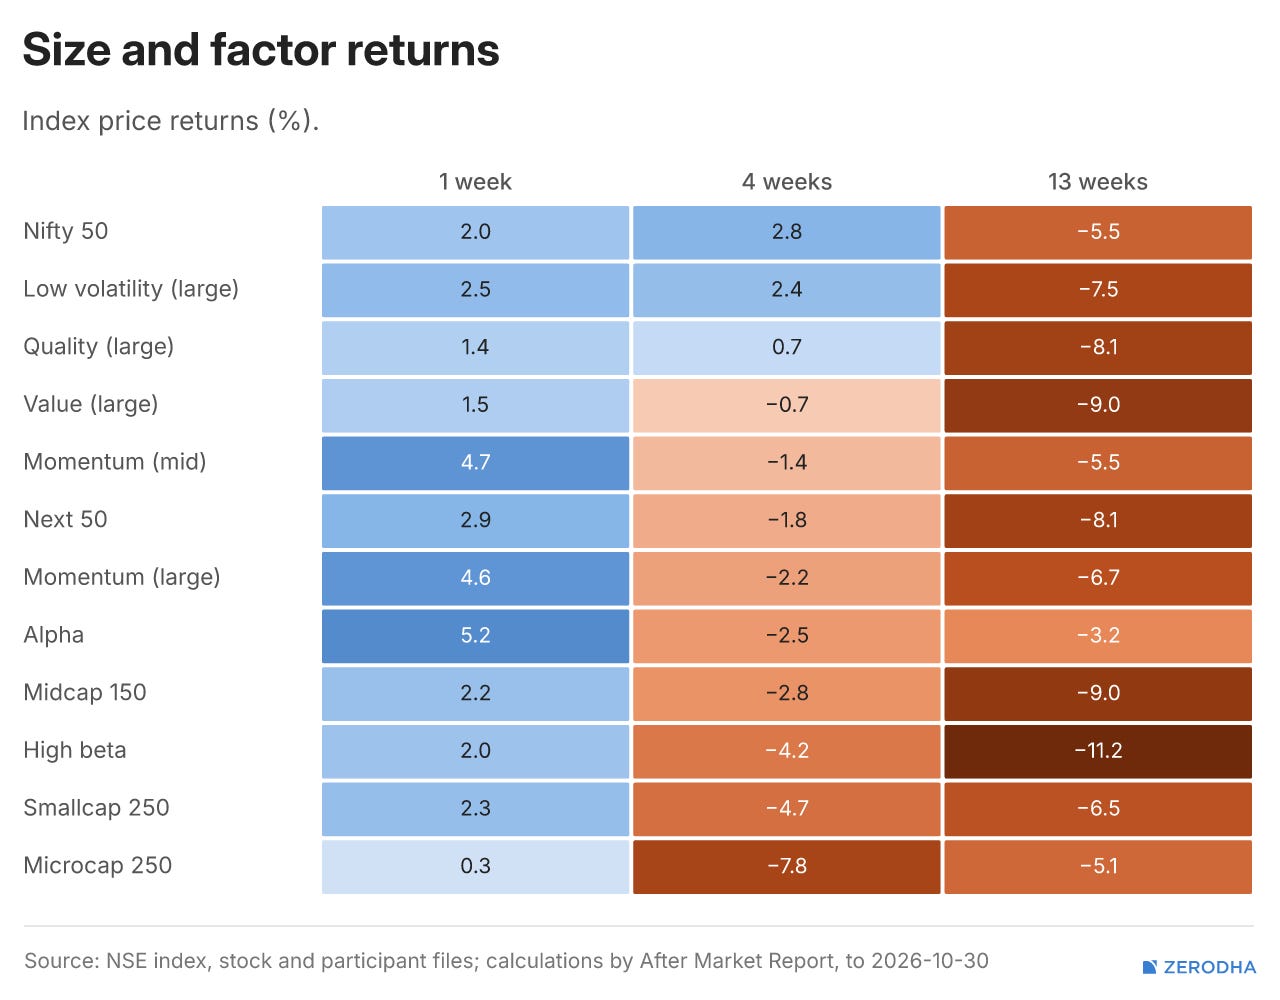
Momentum continued to outperform, with last week’s strongest stocks gaining a median 0.28%, compared with a 0.40% decline for the weakest stocks. Momentum has worked in nine of the past 13 weeks, while only 11% of recent breakouts managed to hold above their breakout levels.
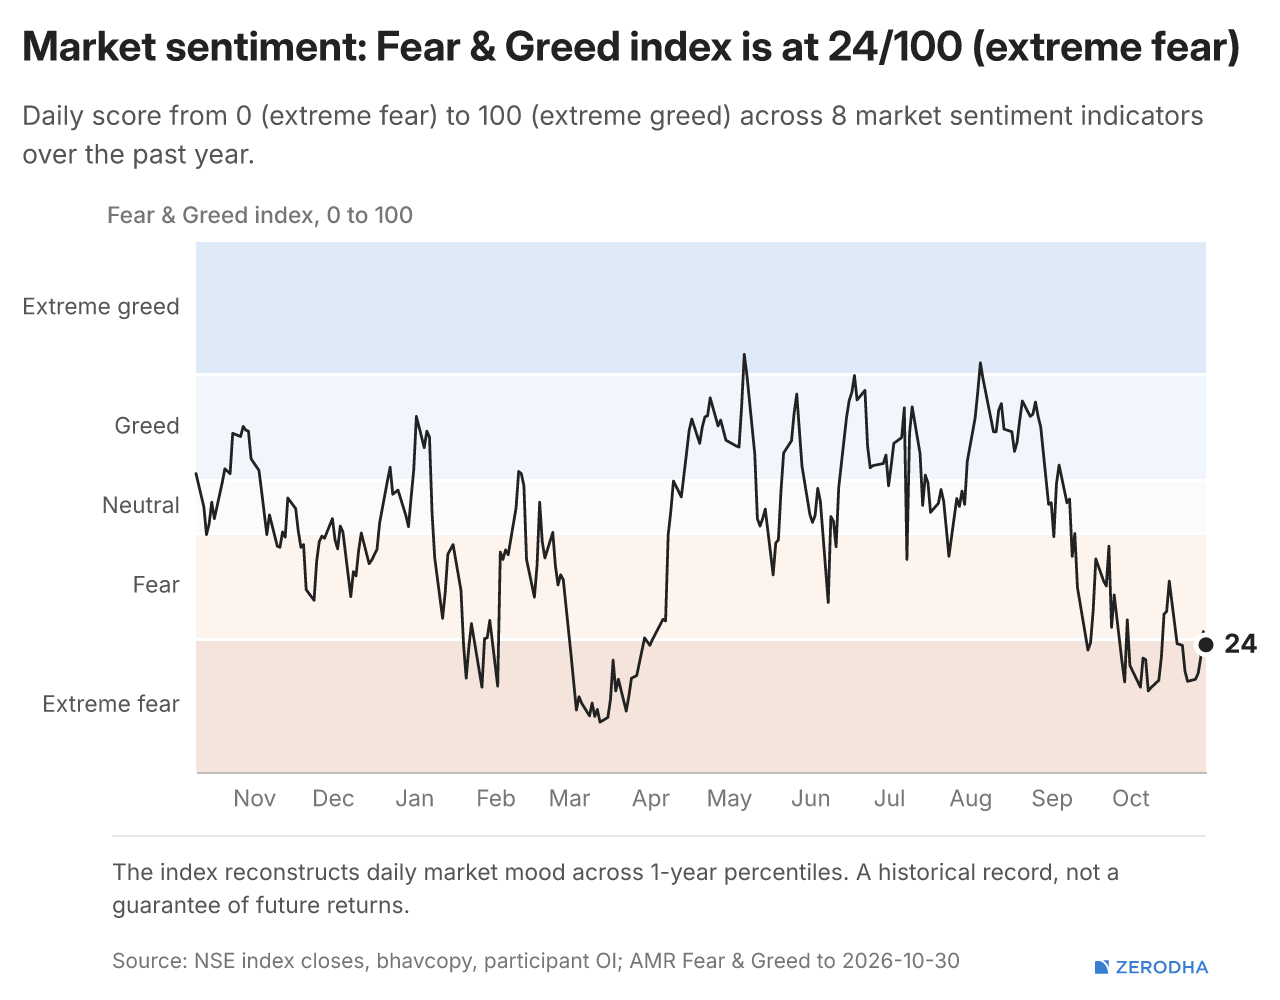
Fear & Greed trend
Market Breadth
Valuation Check
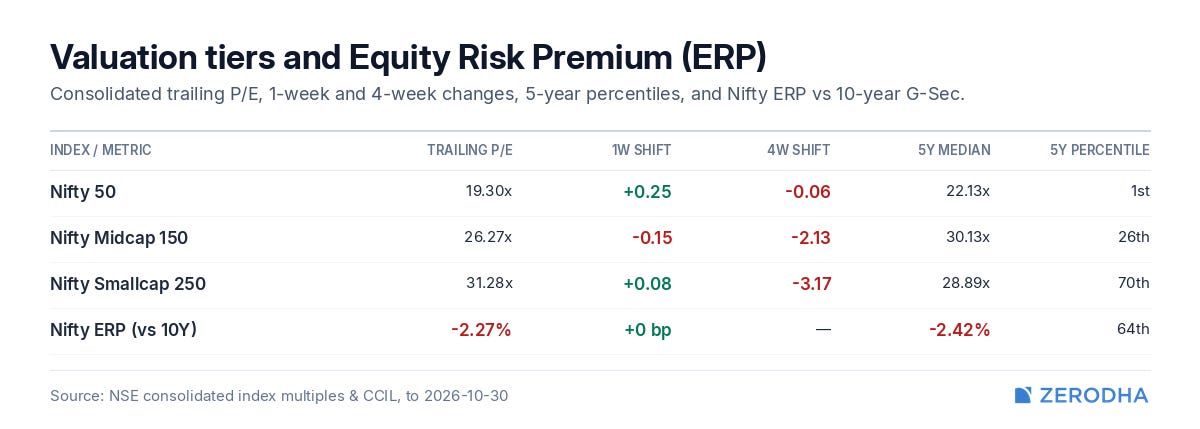
Nifty’s trailing P/E stands at 19.3×, near its five-year lows, compared with 31.28× for smallcaps and 26.27× for midcaps. Smallcaps continue to command a significant valuation premium over largecaps, while the equity risk premium remains close to its historical median.
Sectoral summary
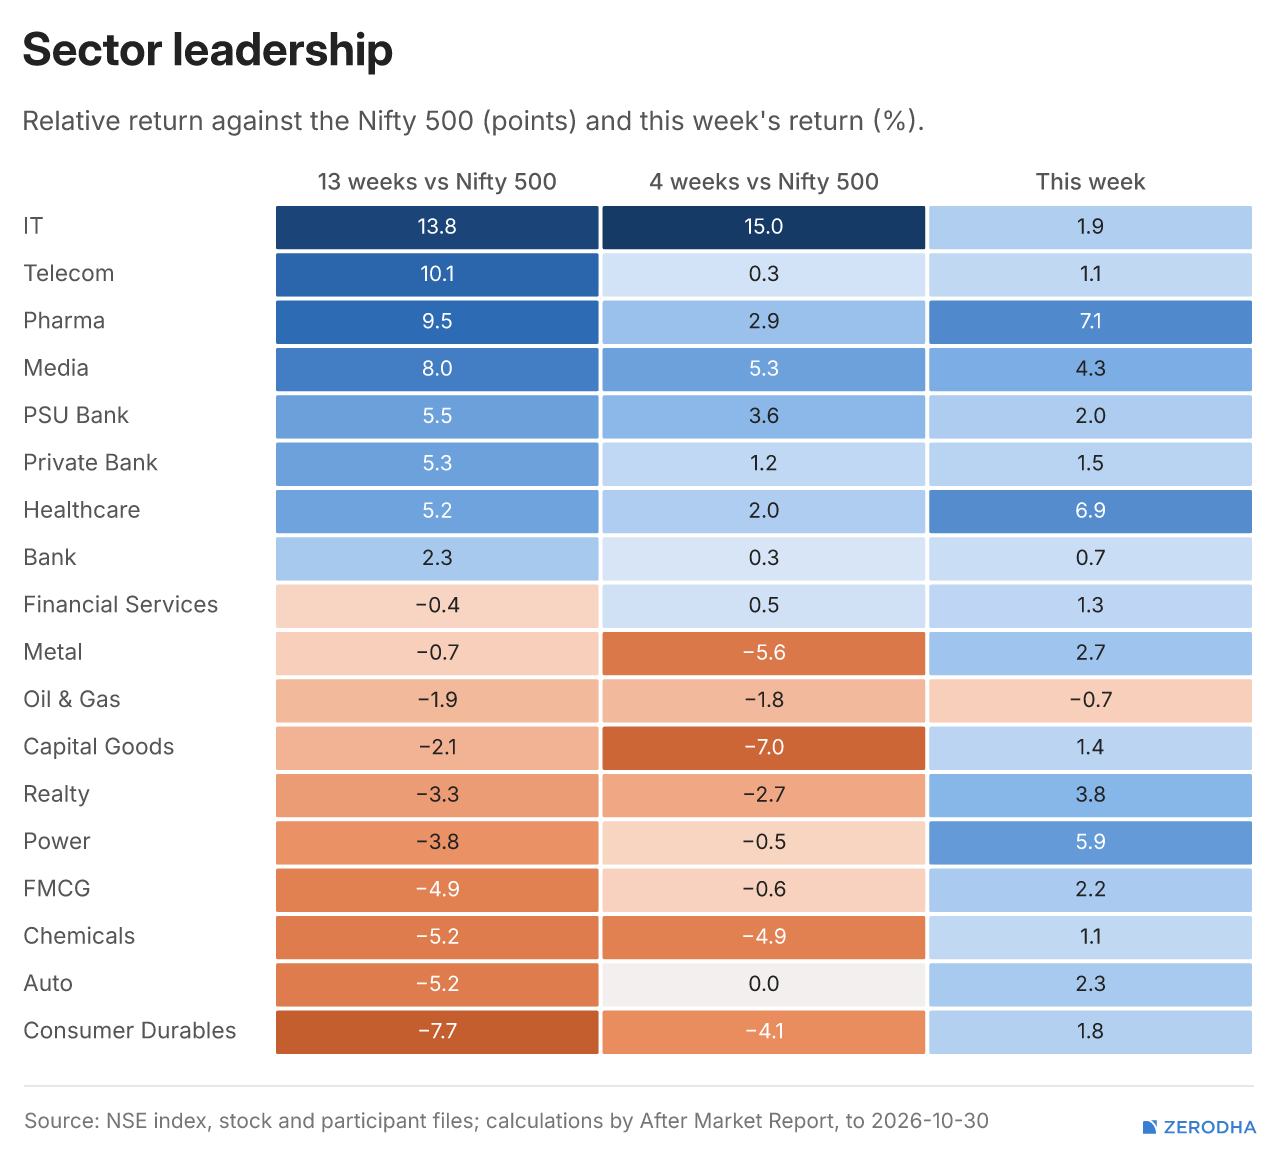
IT, Telecom, Pharma and Media continue to lead the broader market over the past 13 weeks, with IT outperforming the Nifty 500 by 13.8 percentage points. Financial Services is showing signs of improvement, while Oil & Gas has shifted from leading to lagging.
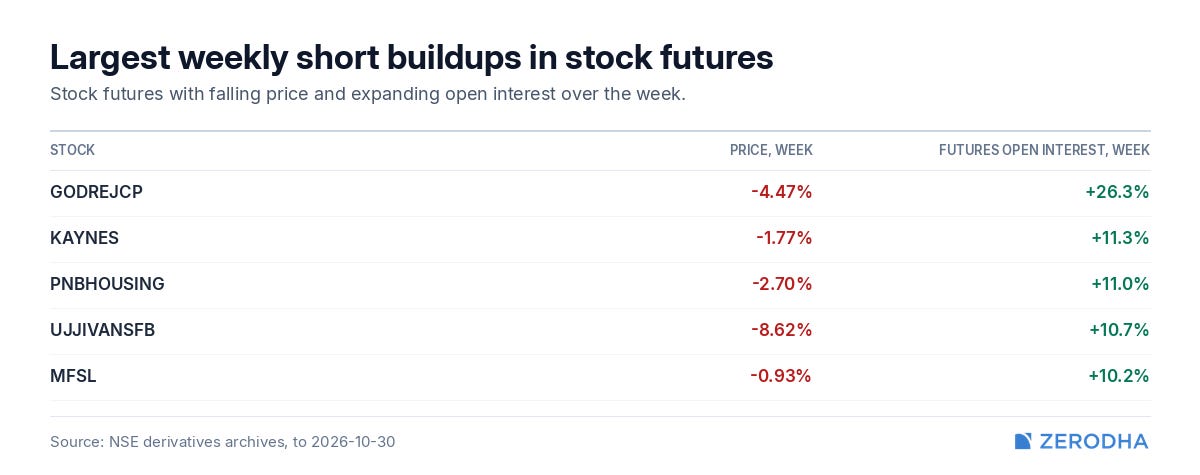
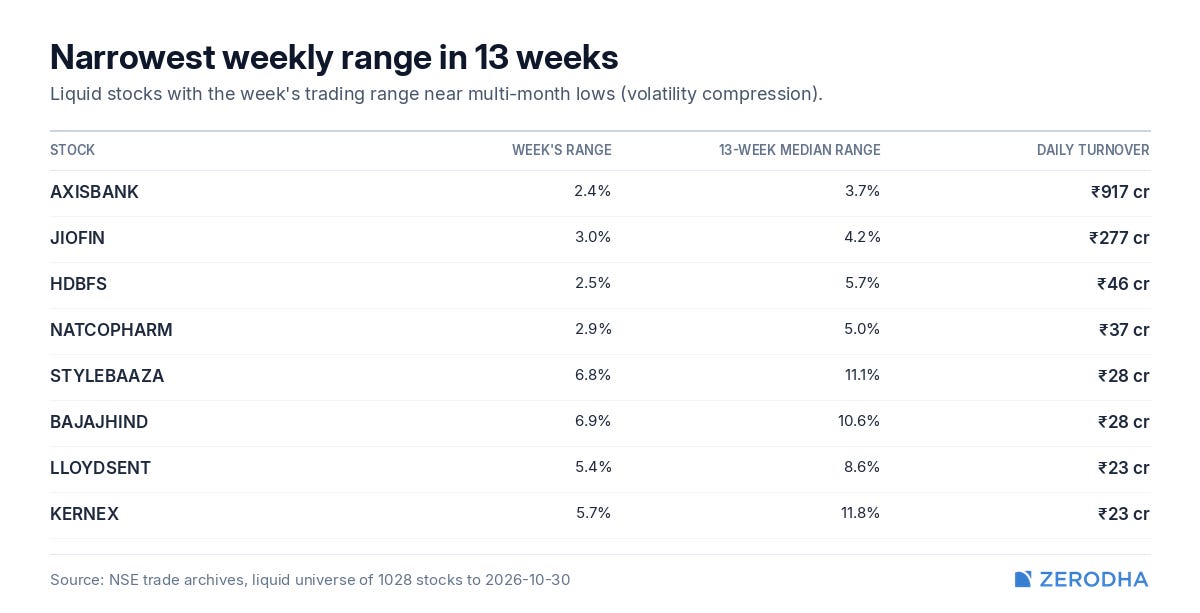
Selective stock screeners
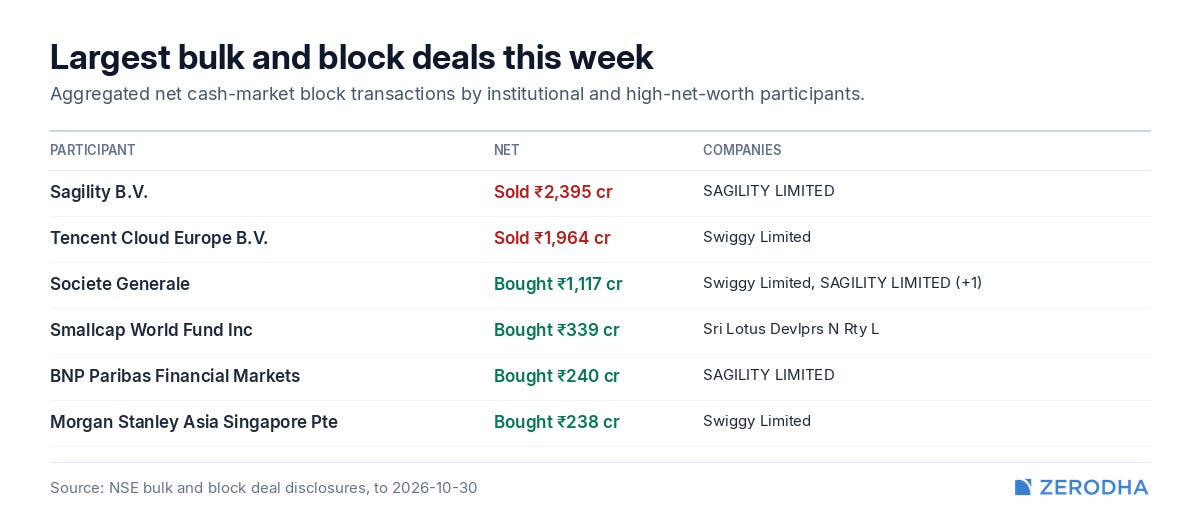
Deals of the week
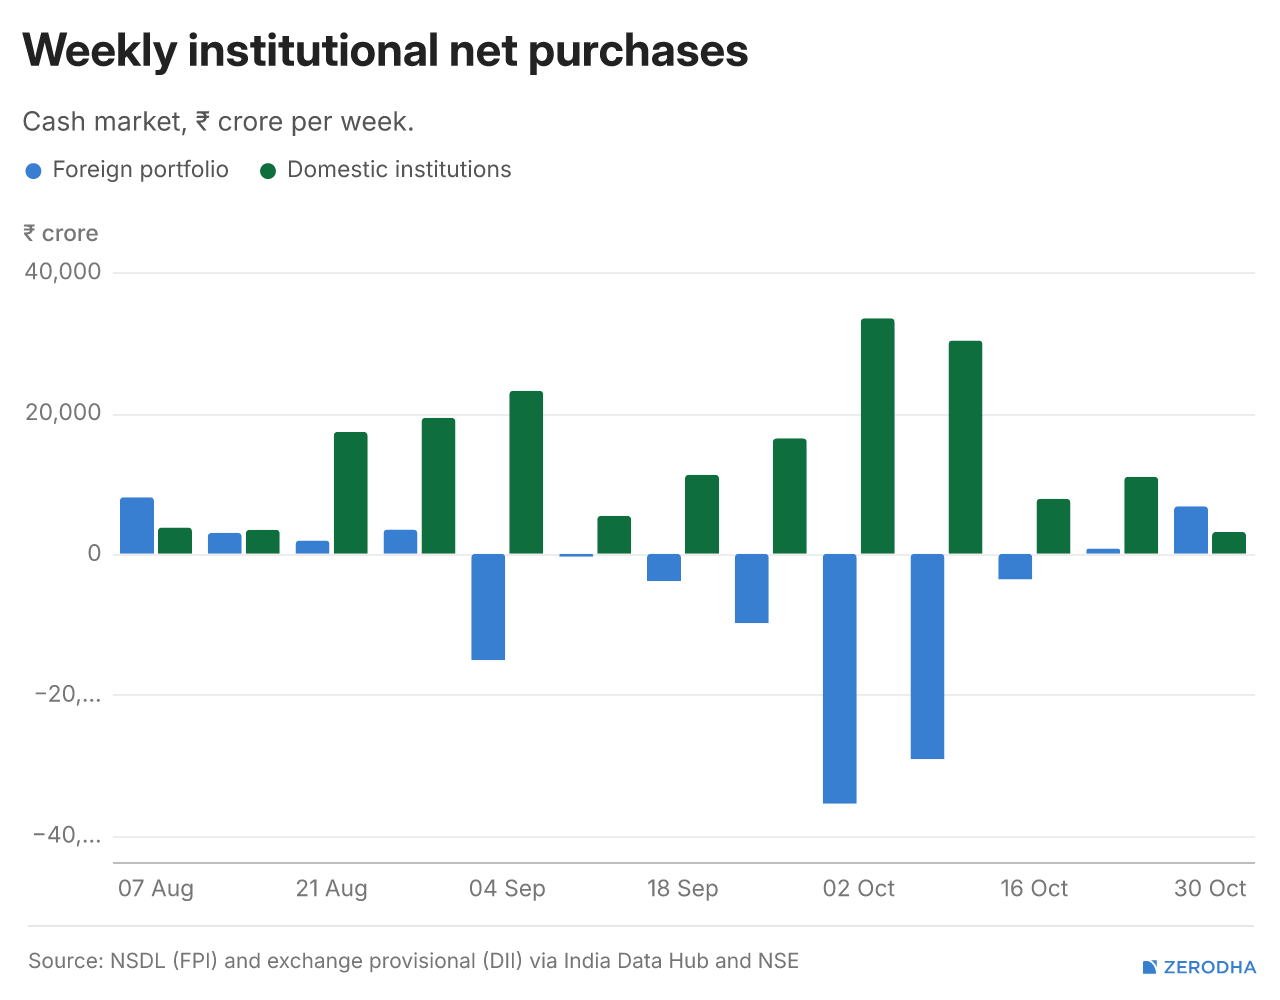
Institutional flows & positioning
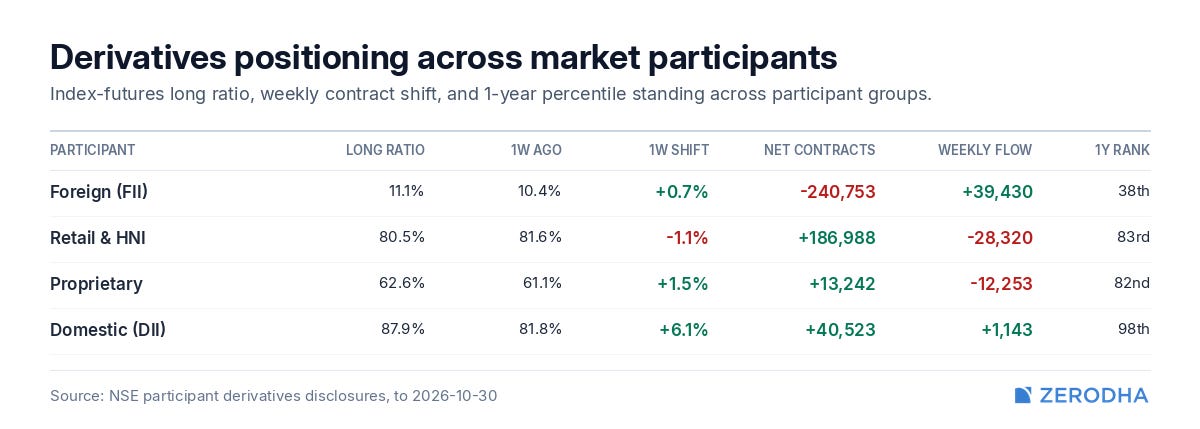
Foreign investors bought ₹6,756 crore, while domestic institutions purchased ₹3,110 crore during the week. However, over the past four weeks, FPIs have sold ₹25,279 crore, with domestic institutions absorbing the selling through purchases worth ₹52,178 crore.
Week ahead
Check out Weekly market metrics
We’re in Week 44 of 2026, and markets staged a recovery after last week’s decline. The NIFTY gained 2% to close at 23,053, moving back above the psychologically important 23,000 mark. Pharma led sectoral gains, while India VIX cooled off. However, the broader trend remains weak, with major indices still trading below their 52-week highs and key moving averages.
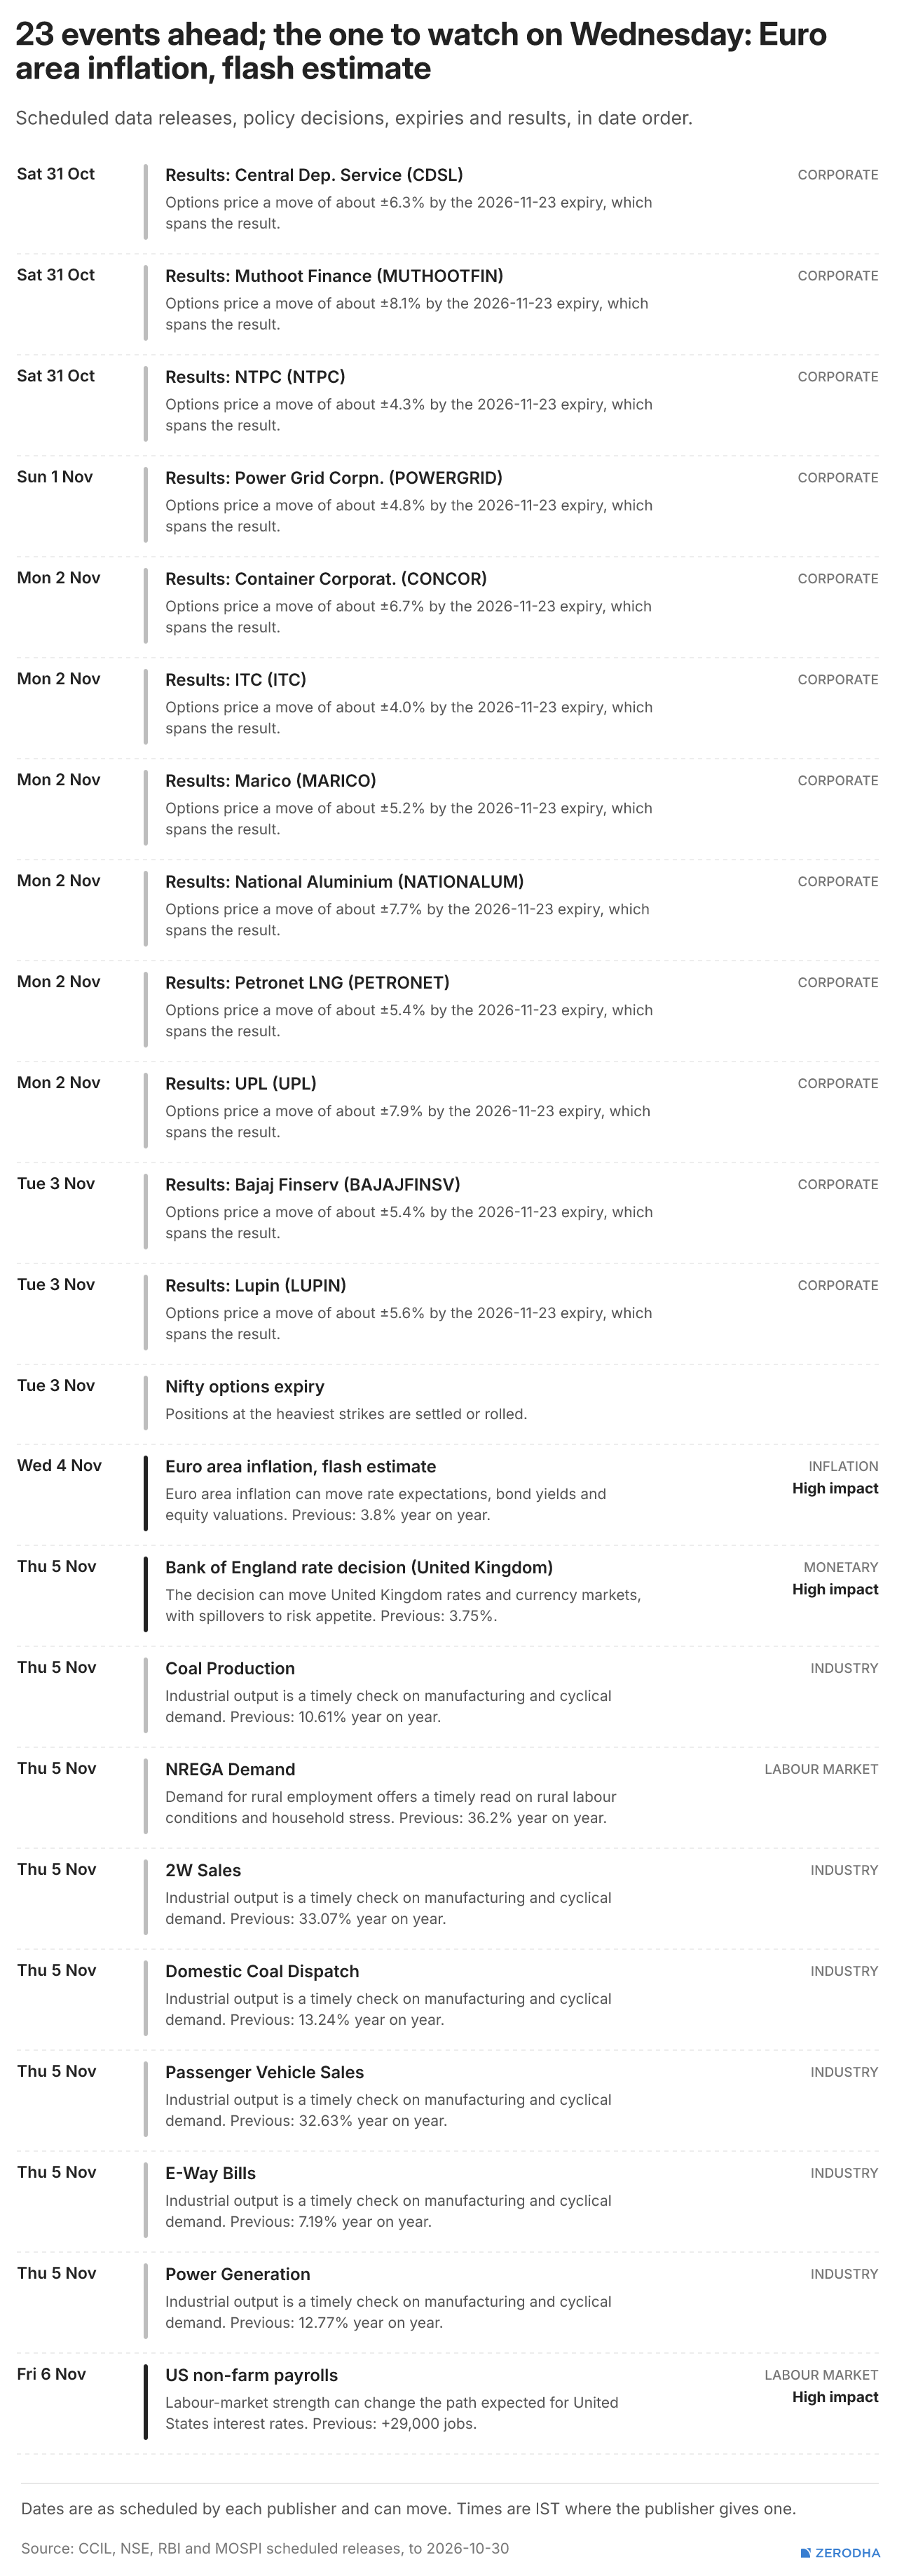
As we head into November, we look at the crucial support and resistance levels, options market signals, sectoral trends, and what could shape the markets in the coming week.
That’s it for this edition. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!
Superrr! Would love to see more such weekly content!