
Welcome to Aftermarket Report, a newsletter where we do a quick daily wrap-up of what happened in the markets, both in India and globally.
What data points and transformations do you want to see?
We’re trying out a new format for the Aftermarket Report, with much more comprehensive coverage of the data that shapes the trading day.
Beyond the headline indices, we’re now tracking market breadth, new highs and lows, sector and thematic performance, delivery data, F&O positioning, global markets, commodities, flows, and more. We’re also looking at ways to transform this raw data into insights that are actually useful for traders and investors.
The idea is simple: bring different datasets together in one place to give you a clearer picture of what’s happening beneath the surface of the market.
This is still a work in progress, and we’d love your feedback. What data points are we missing? What transformations, ratios, comparisons, or indicators would you find useful? Also tell us what worked, what didn’t, and what felt unnecessary.
Your feedback will help shape the Aftermarket Report from here.
Markets Today
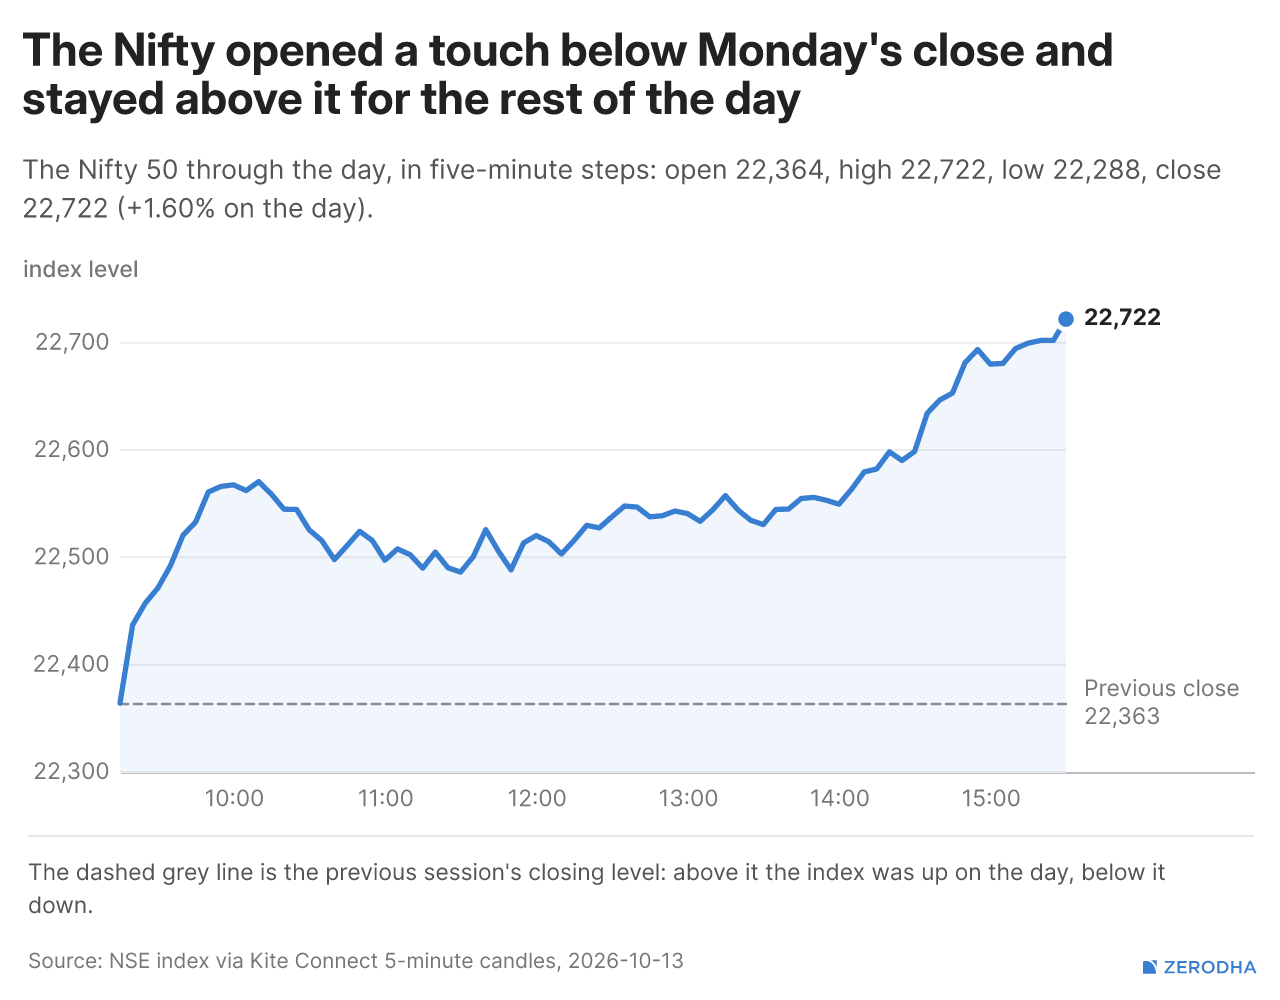
Nifty opened flat at 22,364, led by strength in IT stocks following a strong set of earnings from HCLTech. The index quickly gained momentum after the opening bell, climbing above 22,450 within the first 15 minutes and crossing 22,550 by 9:45 AM. However, the early rally lost steam around 10 AM, with Nifty facing resistance near 22,570 and gradually slipping towards 22,500 by 11 AM.
The index remained largely range-bound between 22,490 and 22,530 through the rest of the morning, as some profit booking emerged at higher levels.
The second half began steadily, with Nifty recovering towards 22,550 around 12:30 PM before slipping back into a narrow range. The index continued to consolidate between 22,530 and 22,560 through much of the early afternoon, with buying momentum remaining subdued.
However, sentiment improved sharply after 2 PM following FM’s comments on openness to discussing & reviewing LTCG & STT, triggering a steady rally that pushed Nifty above 22,600 and eventually past 22,650 by 2:40 PM. Buying strengthened further in the final hour, with the index crossing the 22,700 mark and moving towards the day’s high. Nifty eventually closed at 22,721.95, nearly 350 points above its opening level, marking a strong recovery session as sustained buying in the second half helped the index finish near its intraday highs.
Fear & Greed Index
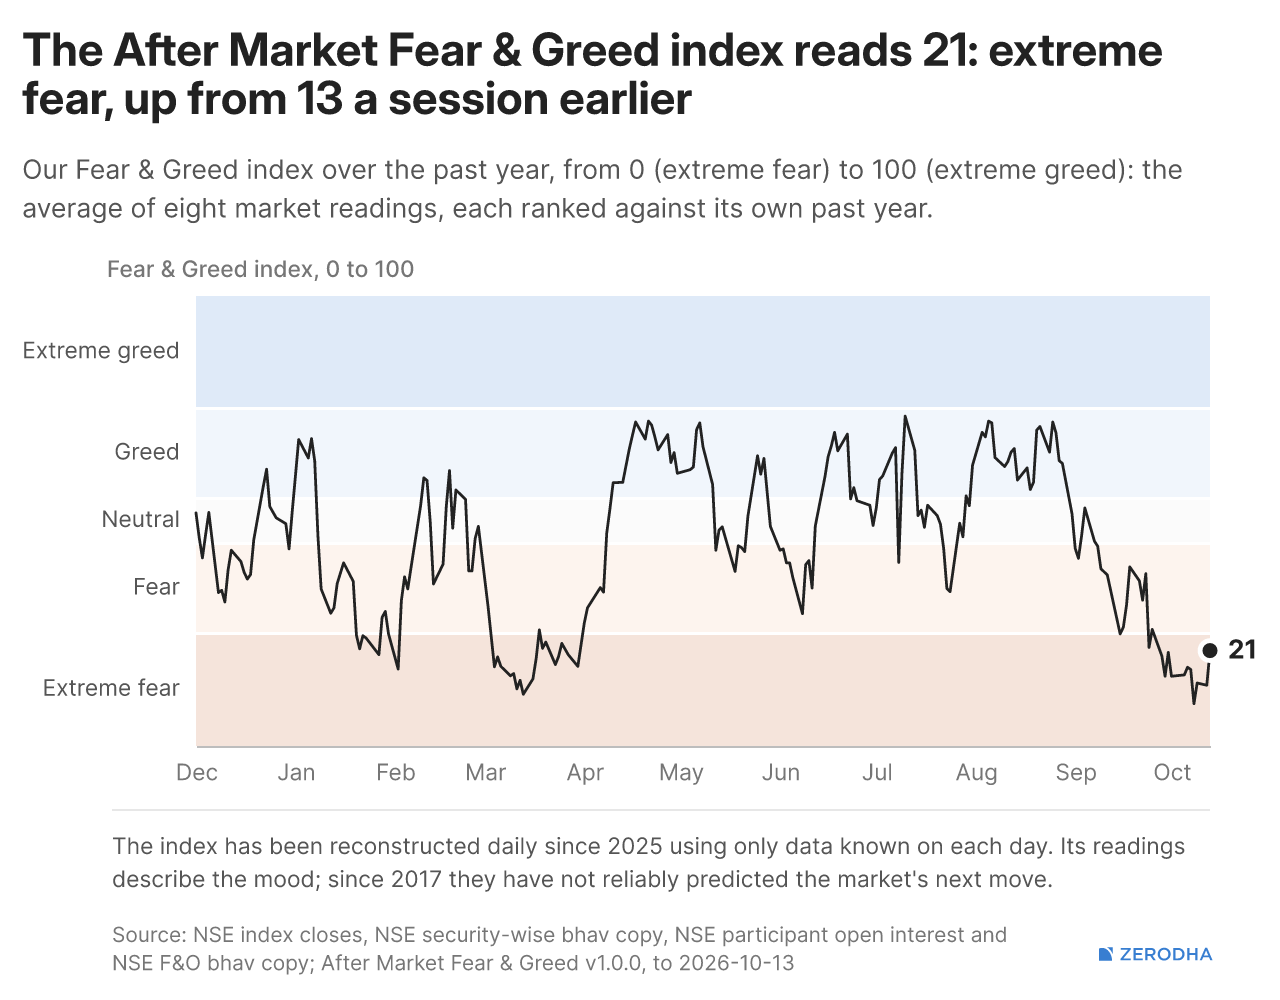
The Fear & Greed Index improved sharply from 13 to 21, but remained in extreme fear. Risk appetite showed signs of recovery, although weak market trends and defensive stocks outperforming high-beta stocks continue to reflect underlying caution.
Market Breadth
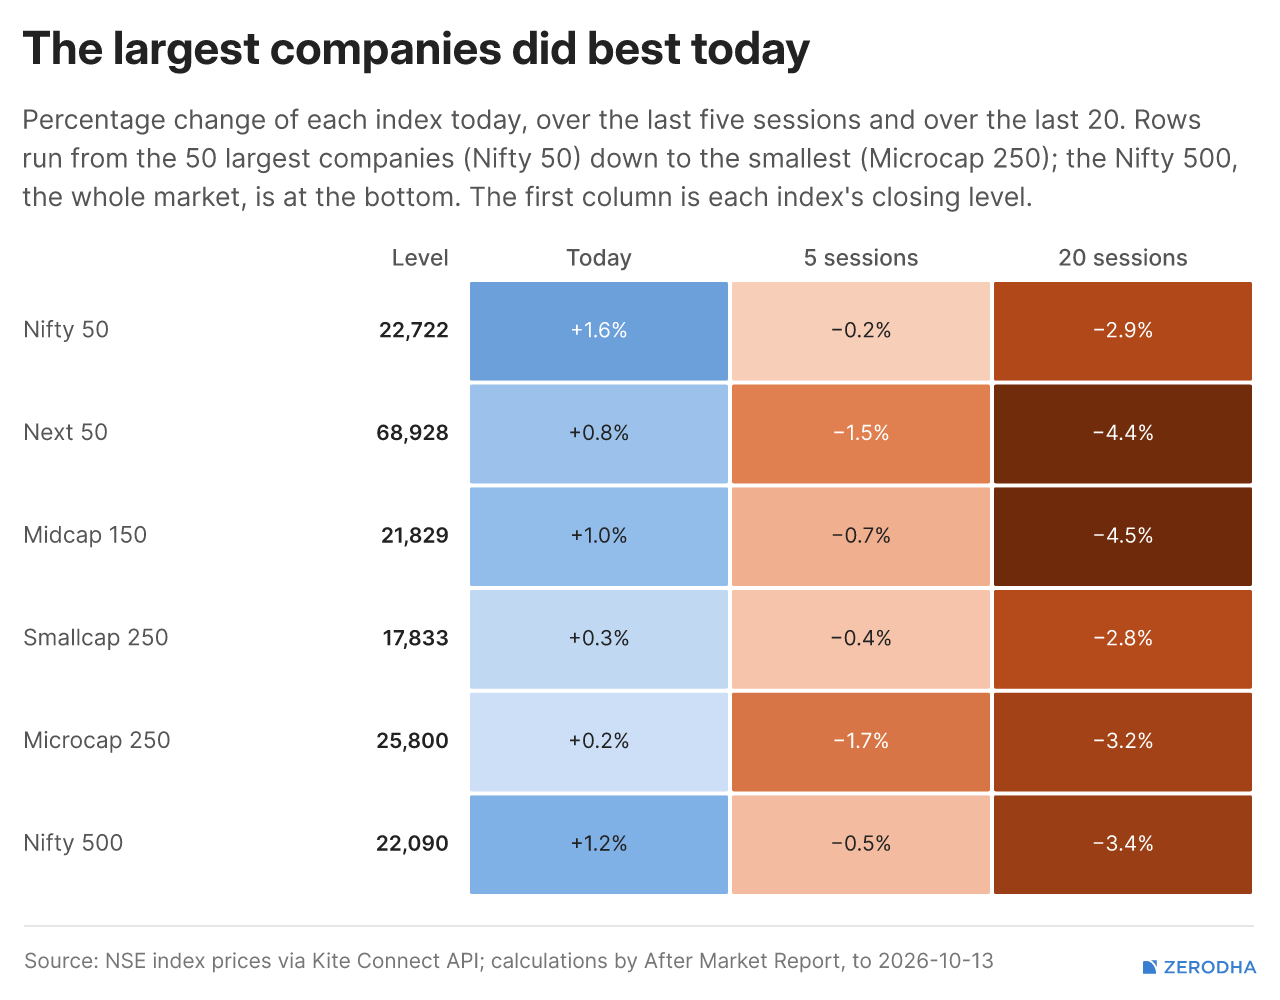
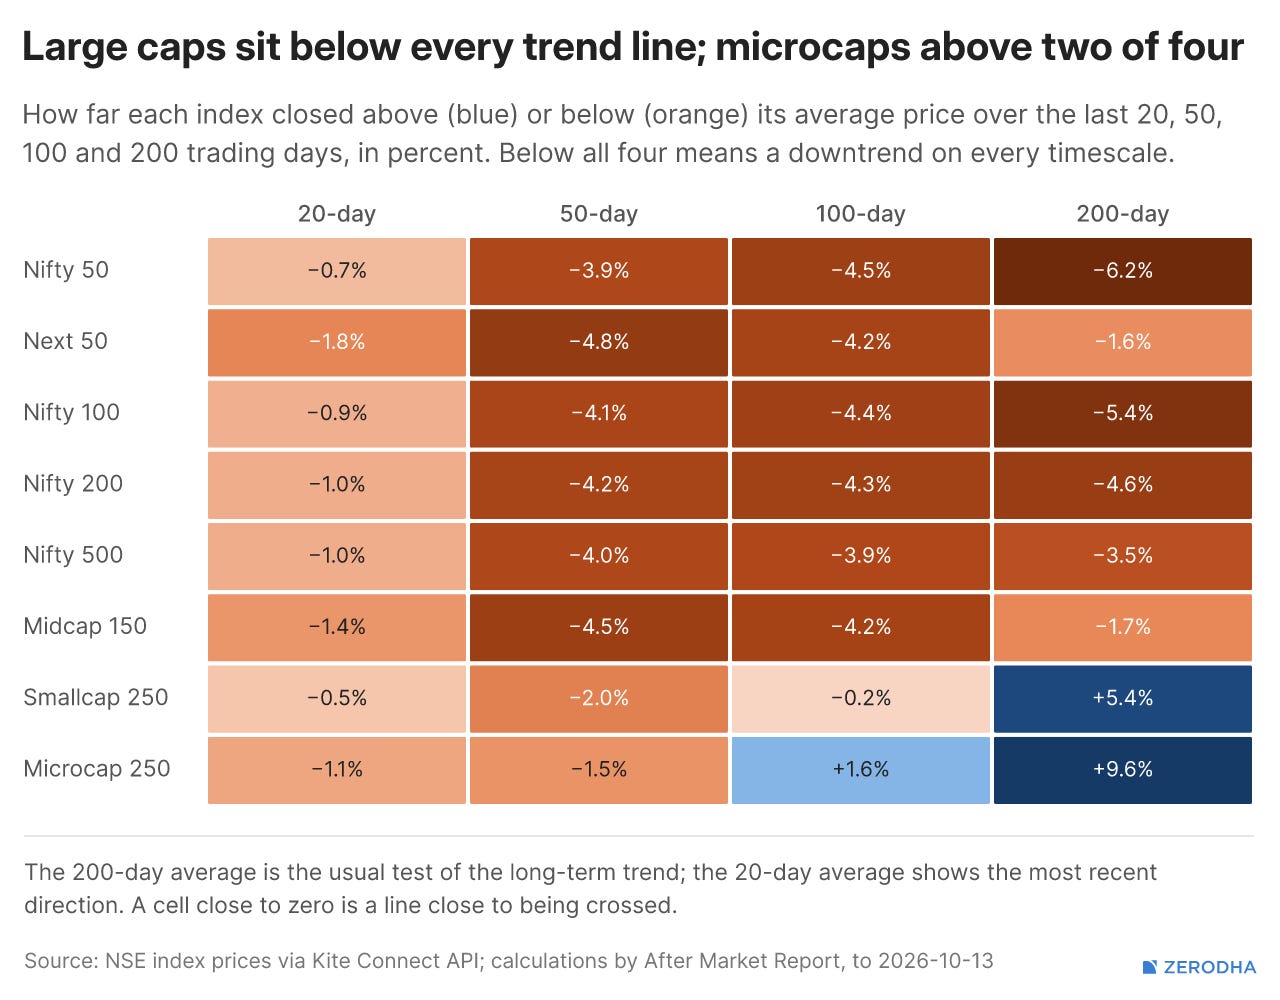
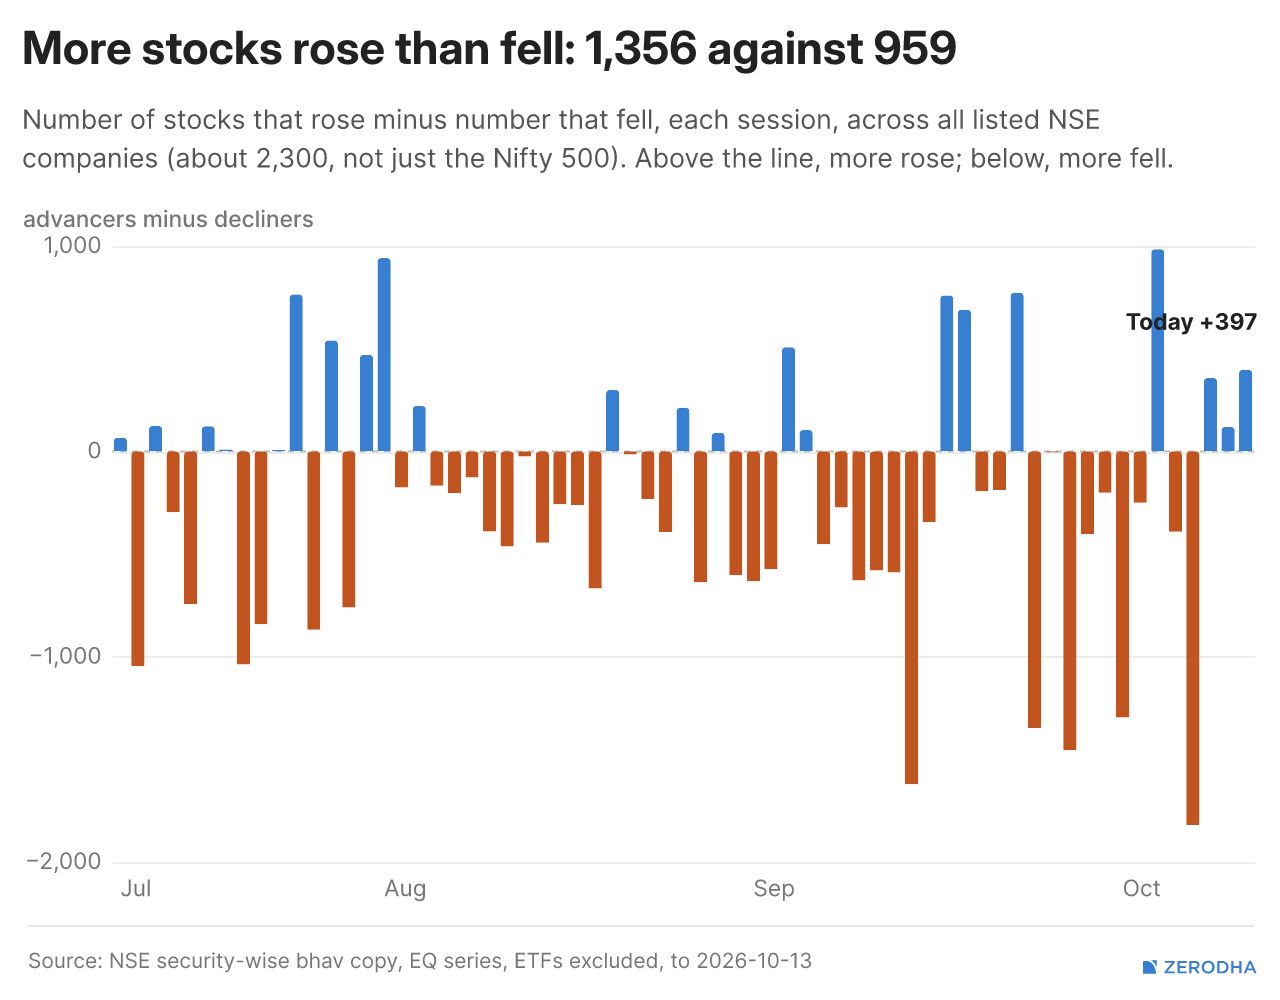
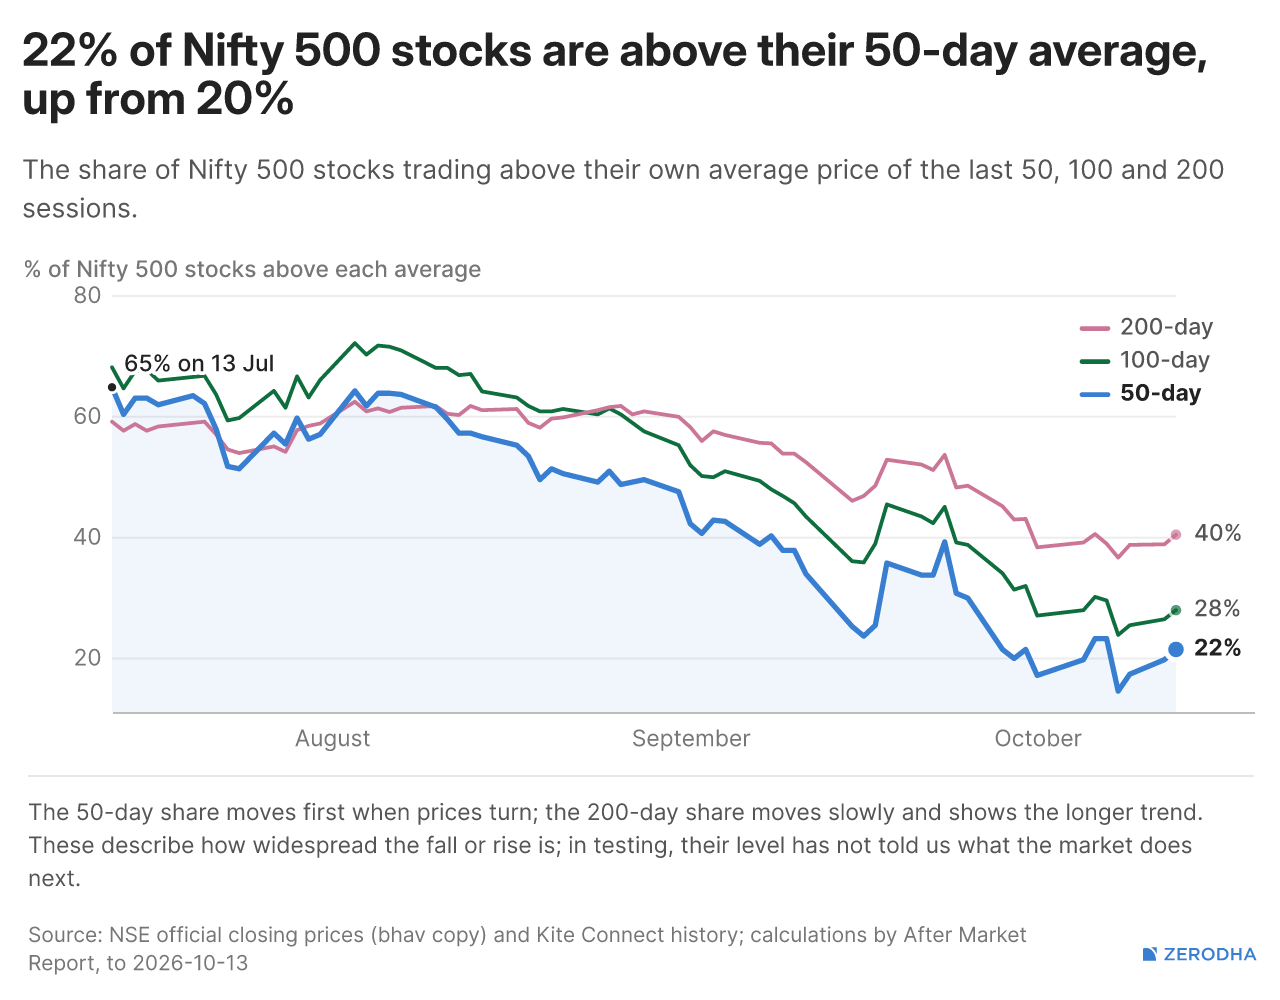
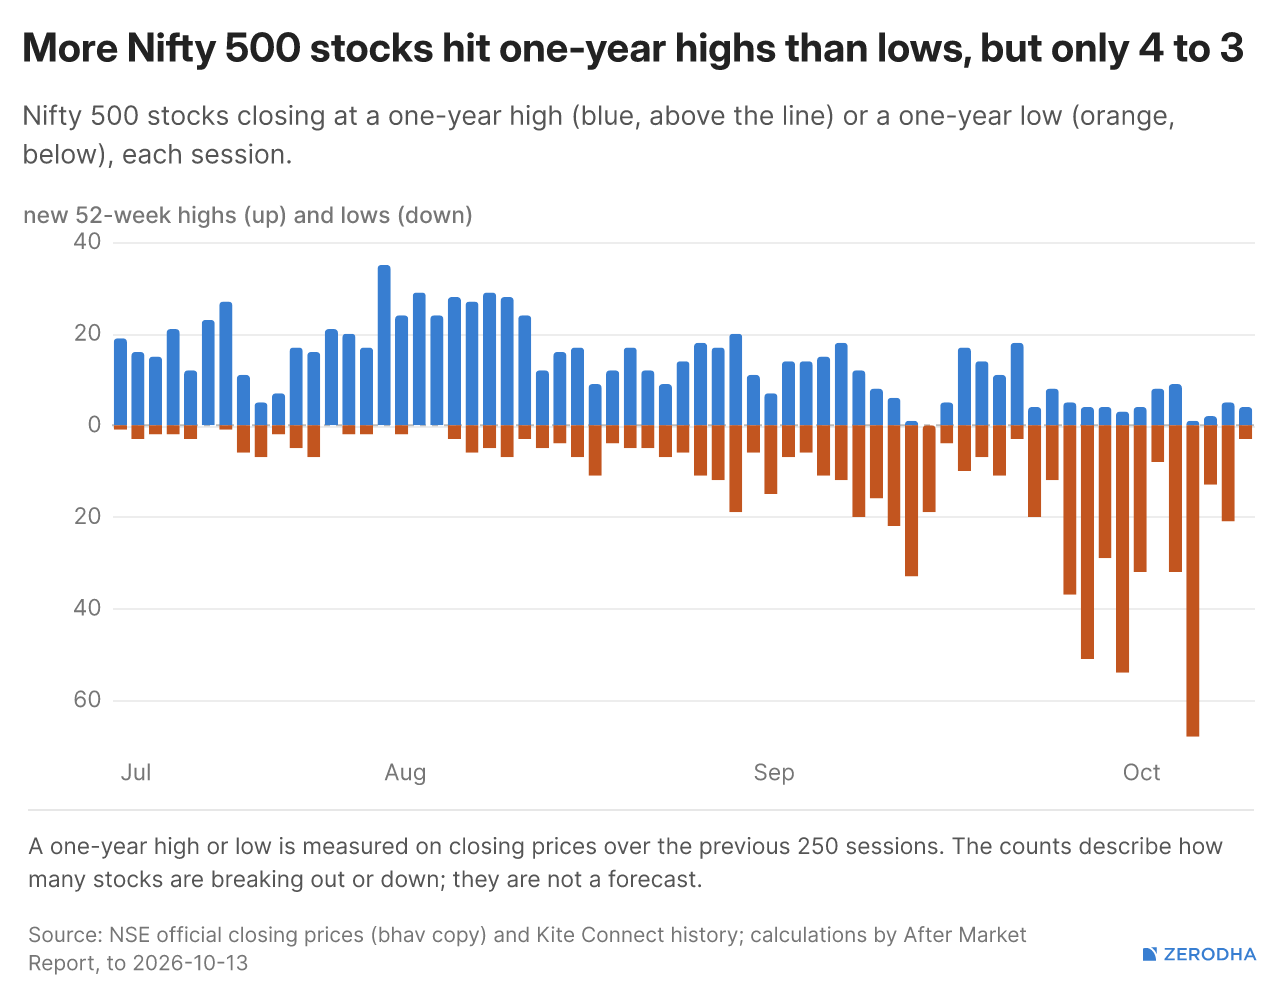
Market breadth improved, with 1,356 advancers against 959 decliners, although large-cap stocks led the rally. Only 21.5% of Nifty 500 stocks are above their 50-day average, while four stocks hit fresh 52-week highs against three new lows.
52 Week Highs & Lows
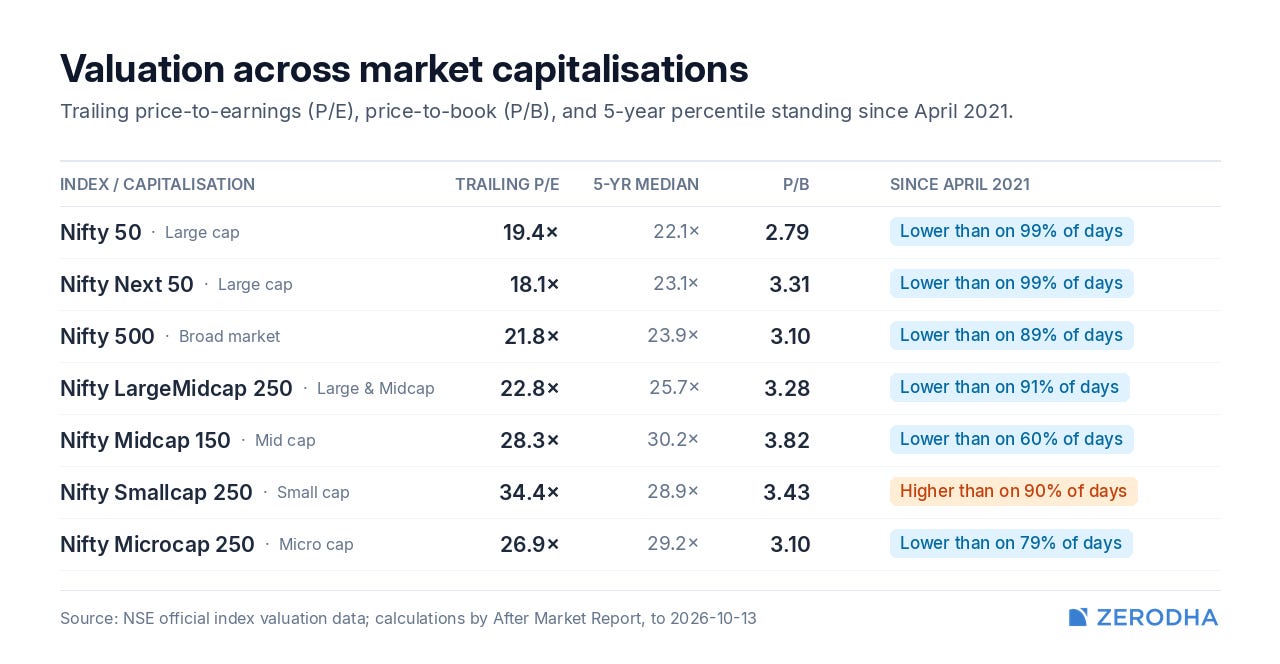
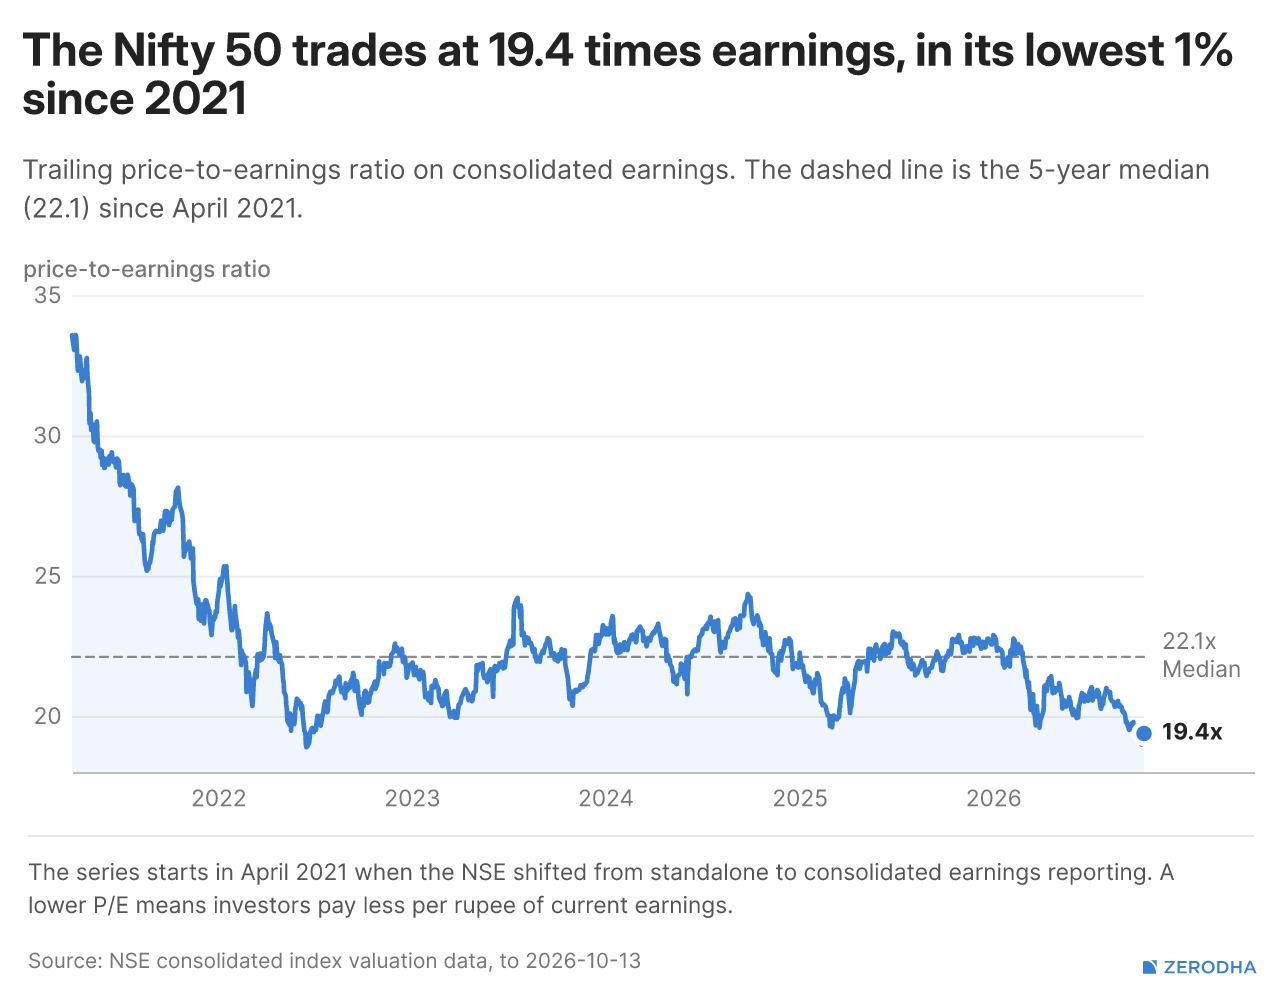
Valuation Check
Sectoral Indices Performance
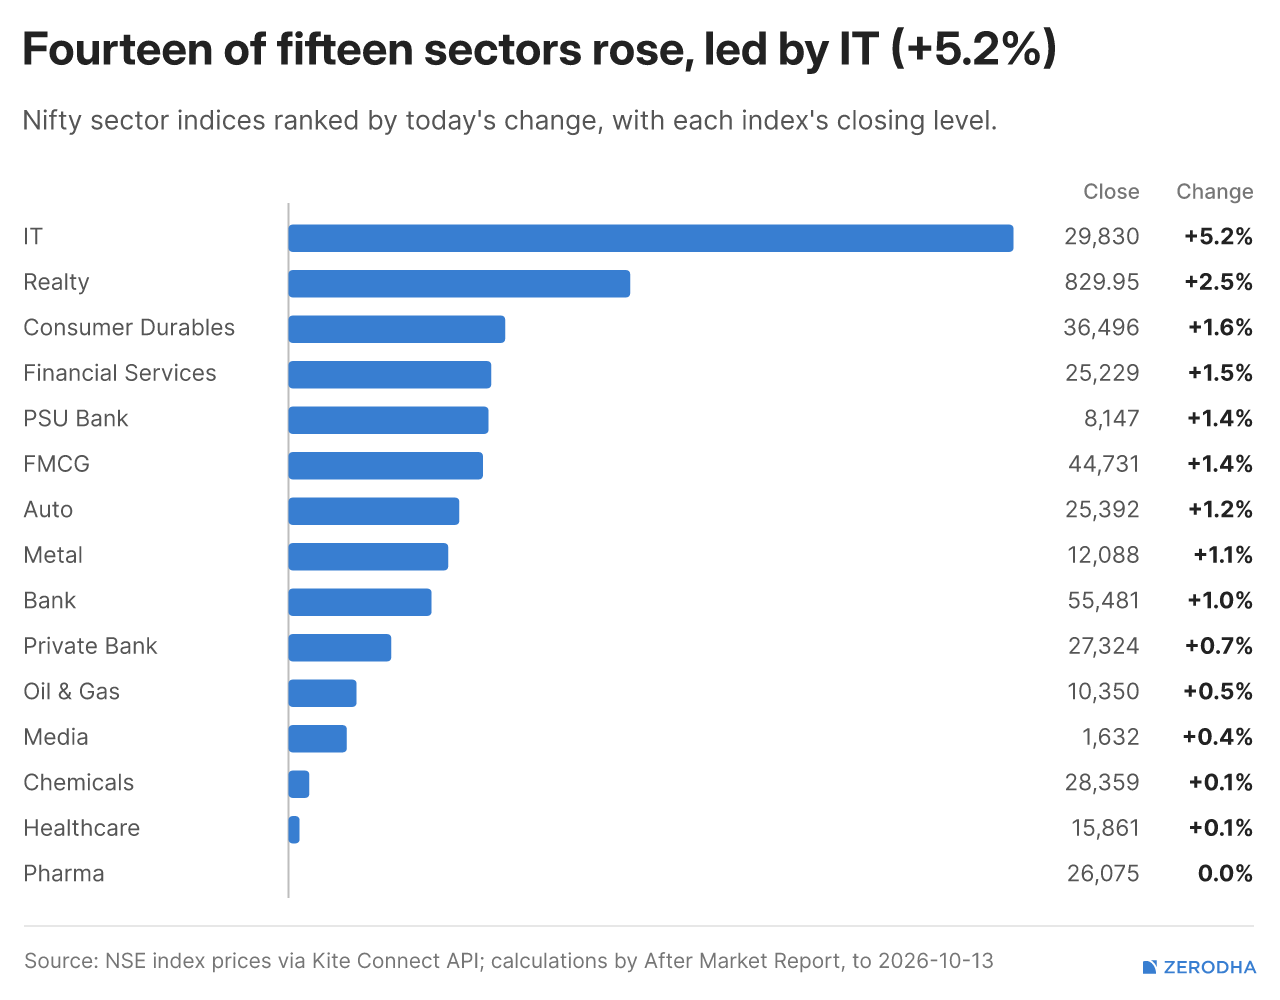
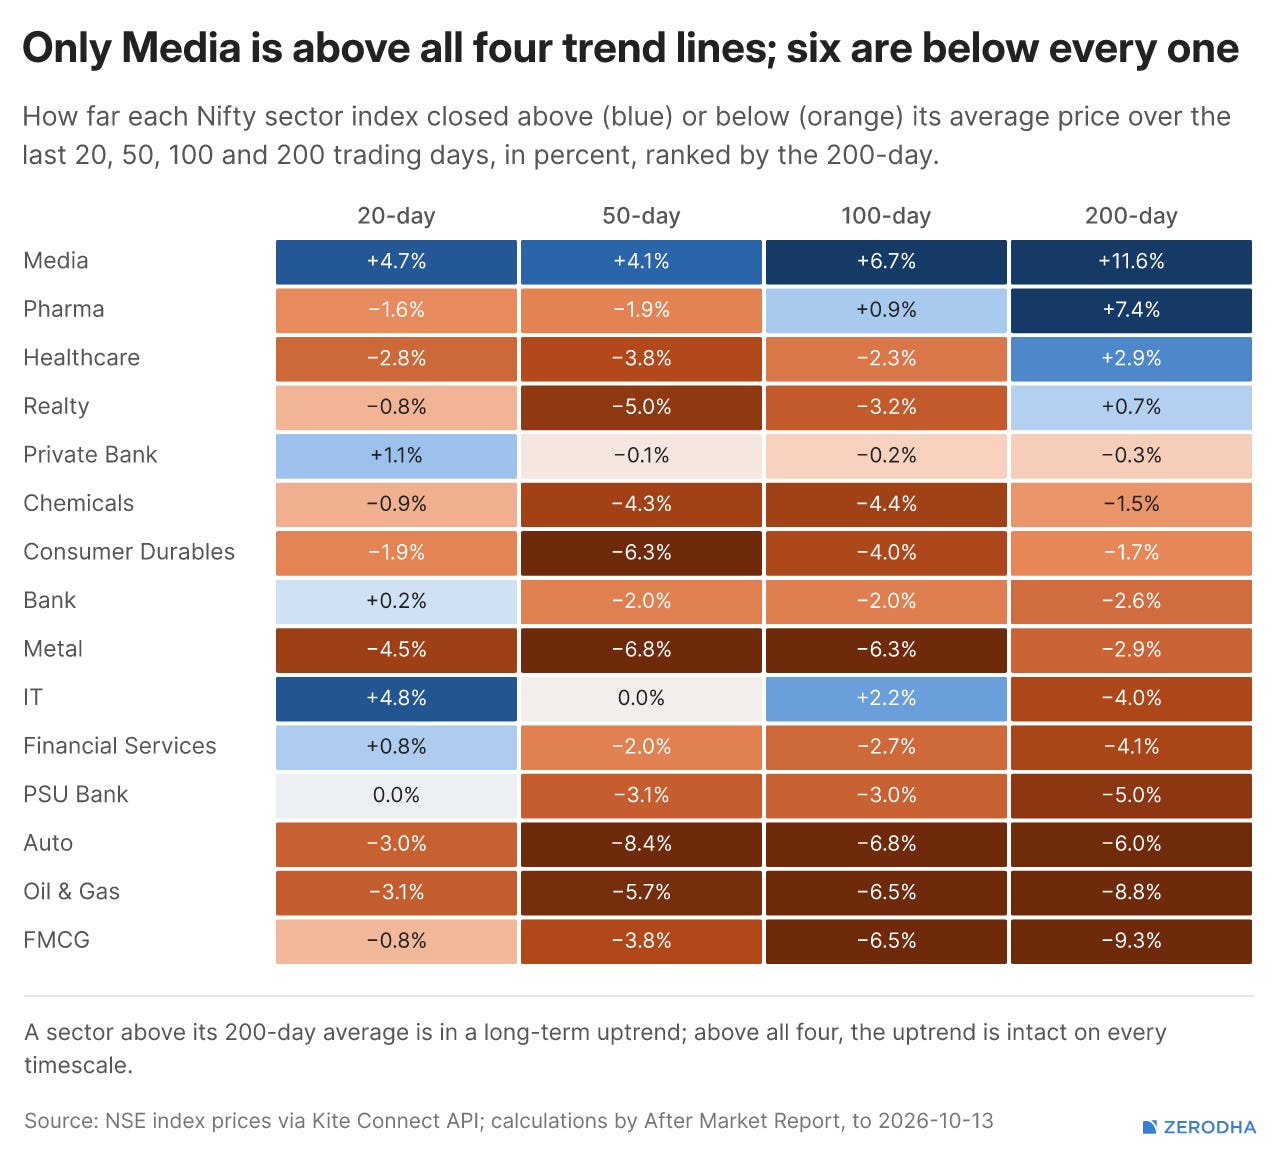
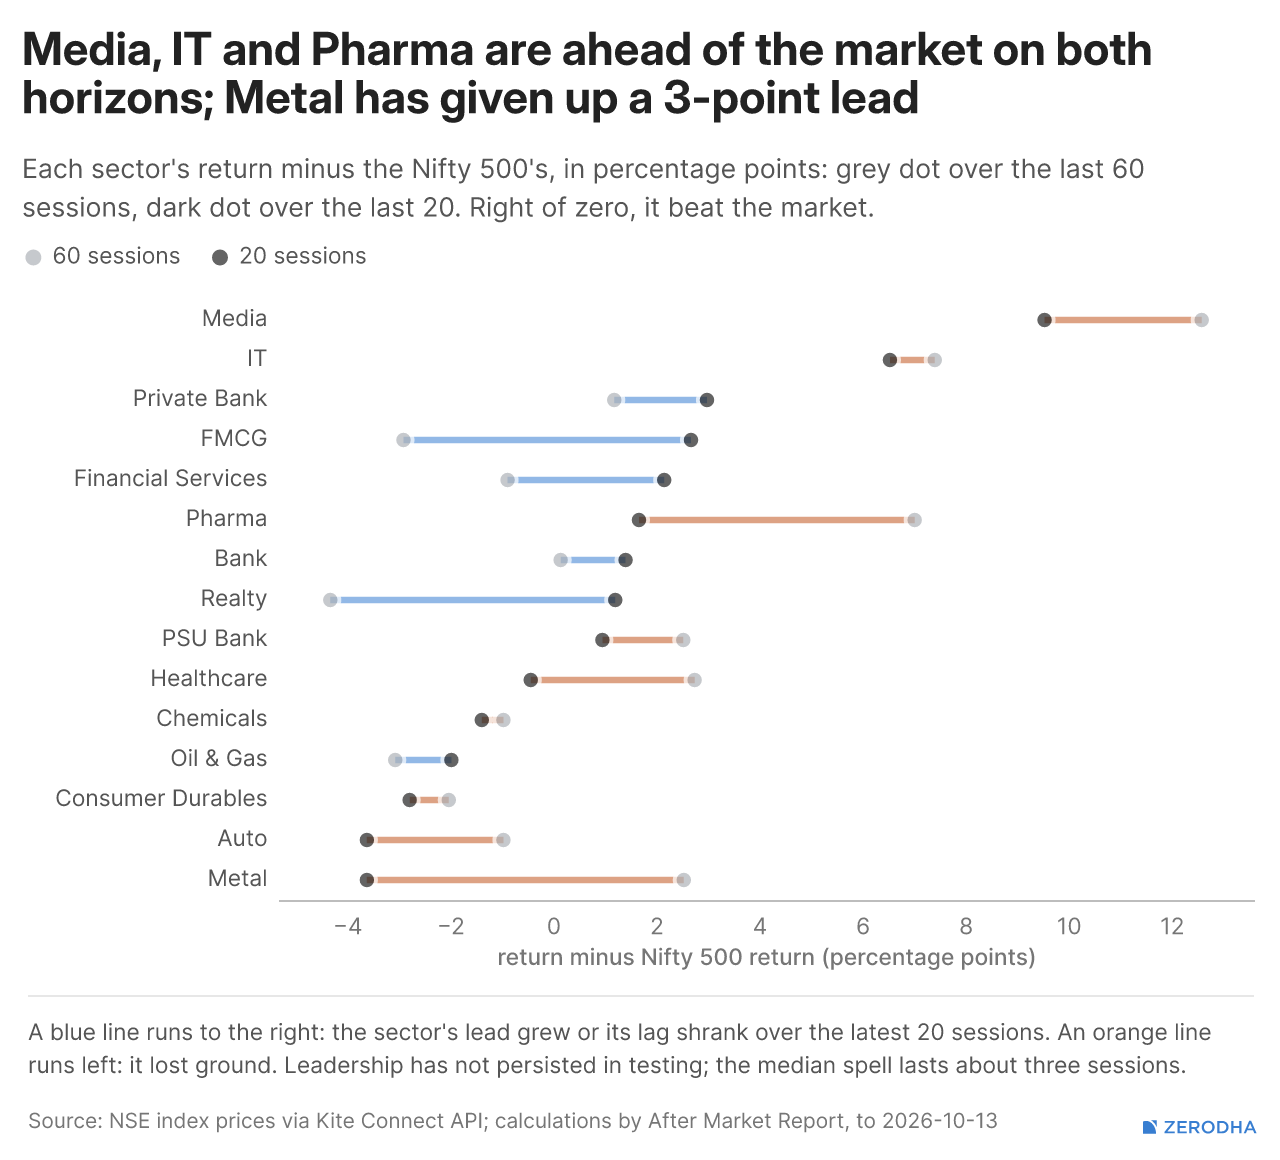
IT surged 5.22%, leading gains across 14 of 15 sectors, while Pharma was the only sector in the red (-0.01%). Media, IT and Pharma remain the relative leaders over 20 and 60 sessions, with Media the only sector trading above all four key moving averages.
Winners & Losers
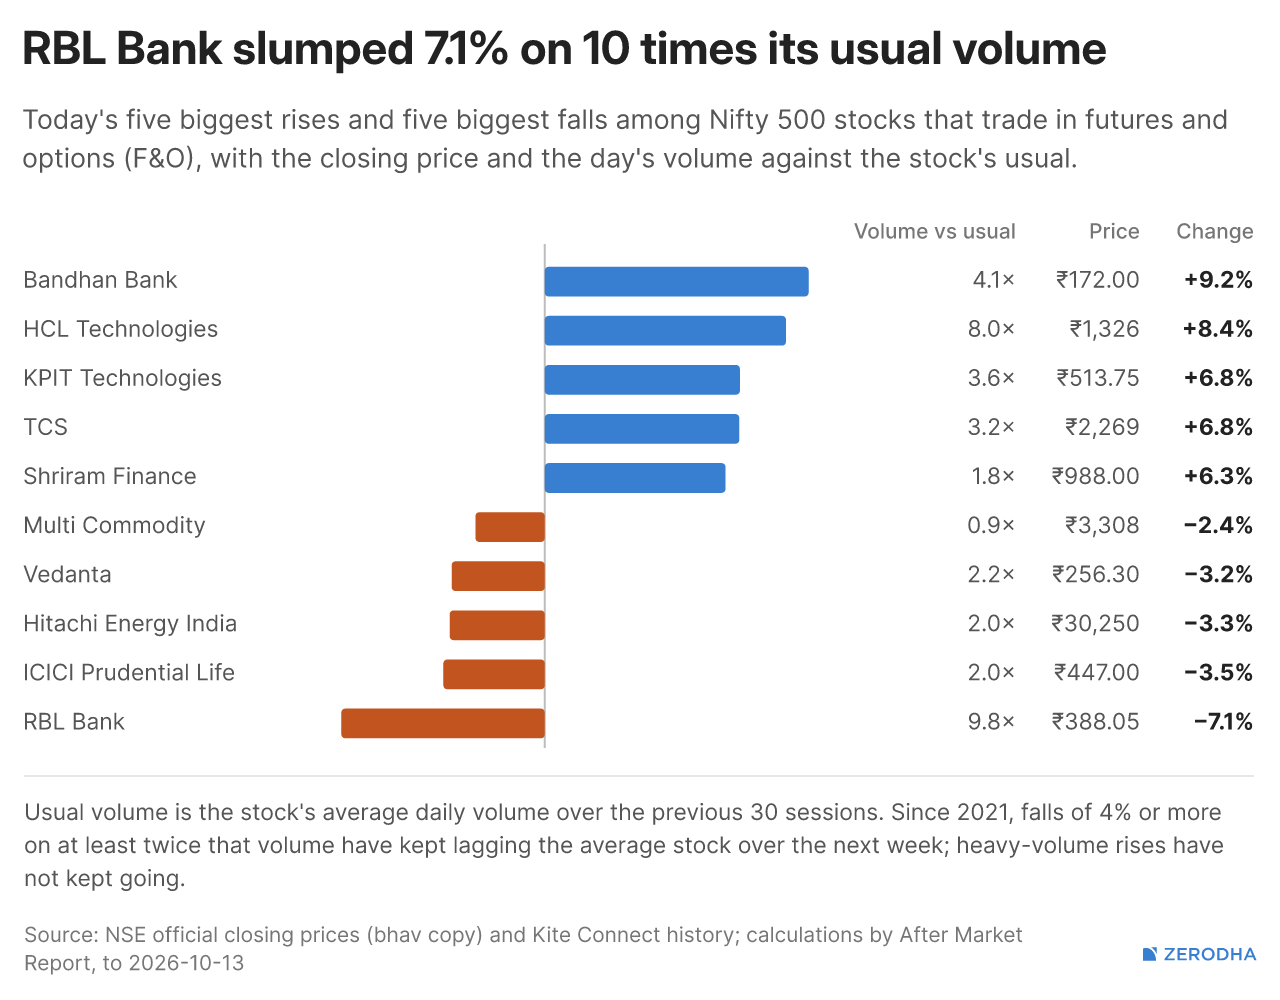
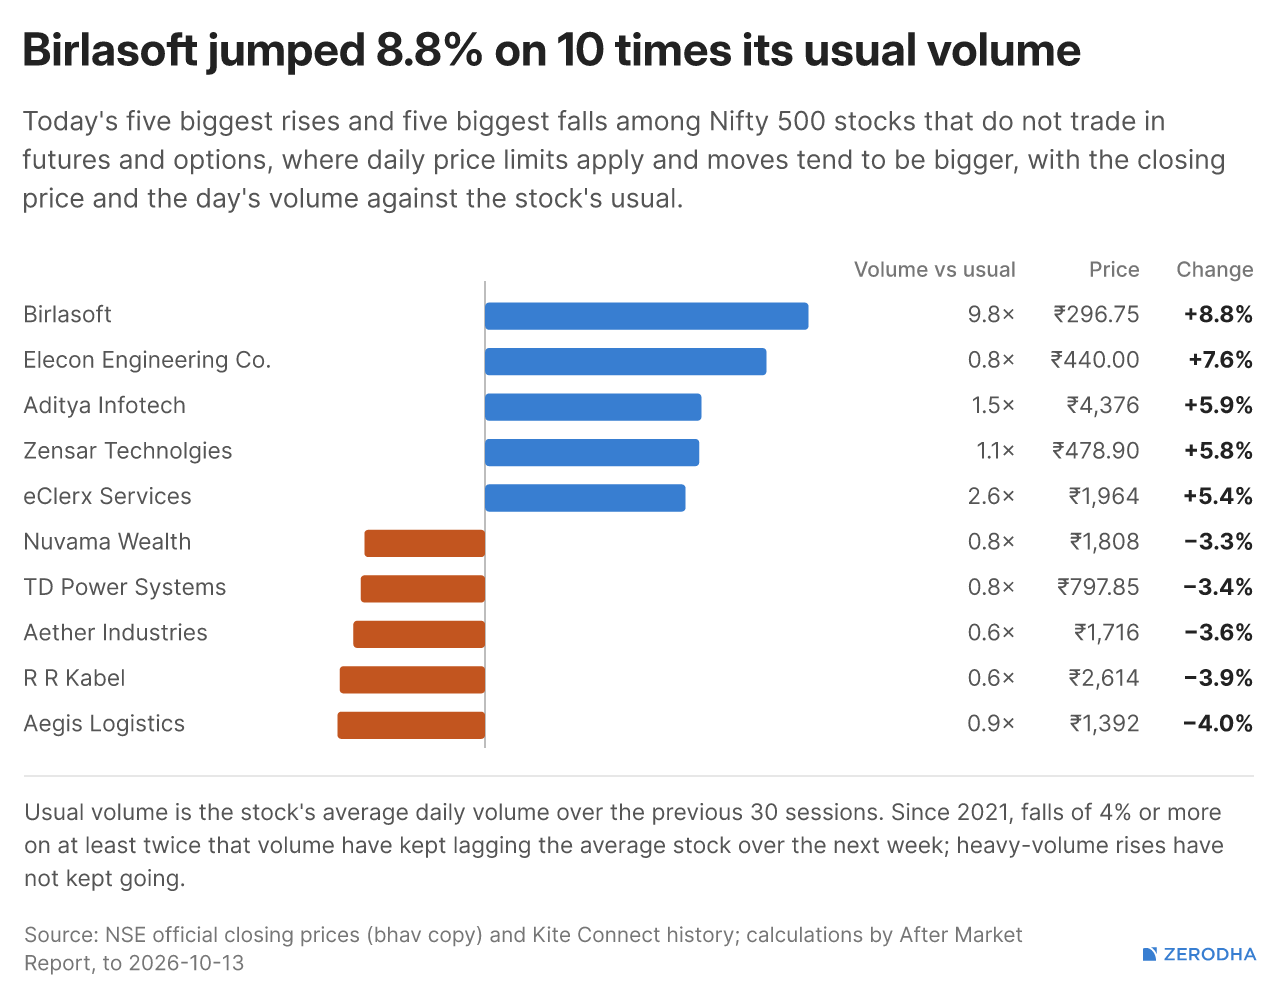
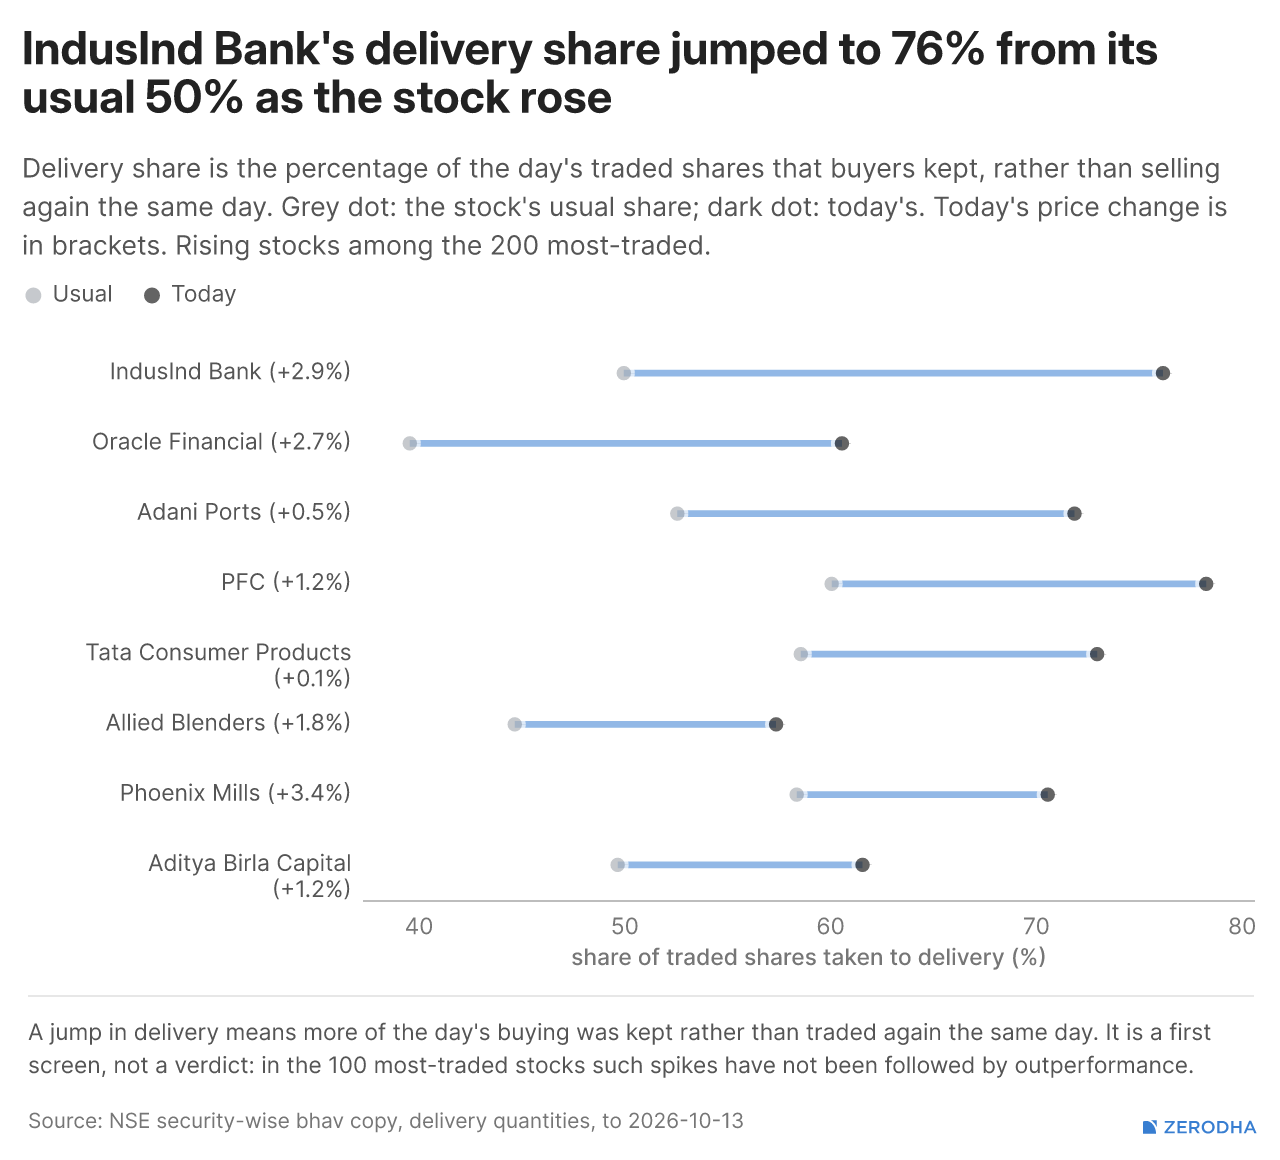
Birlasoft jumped 8.76% on nearly 10× usual volume, while HCL Technologies gained 8.42% on heavy trading. RBL Bank plunged 7.10%, while IndusInd Bank recorded a delivery spike, with 76% of traded shares going to delivery against its usual 50%.
Delivery Data
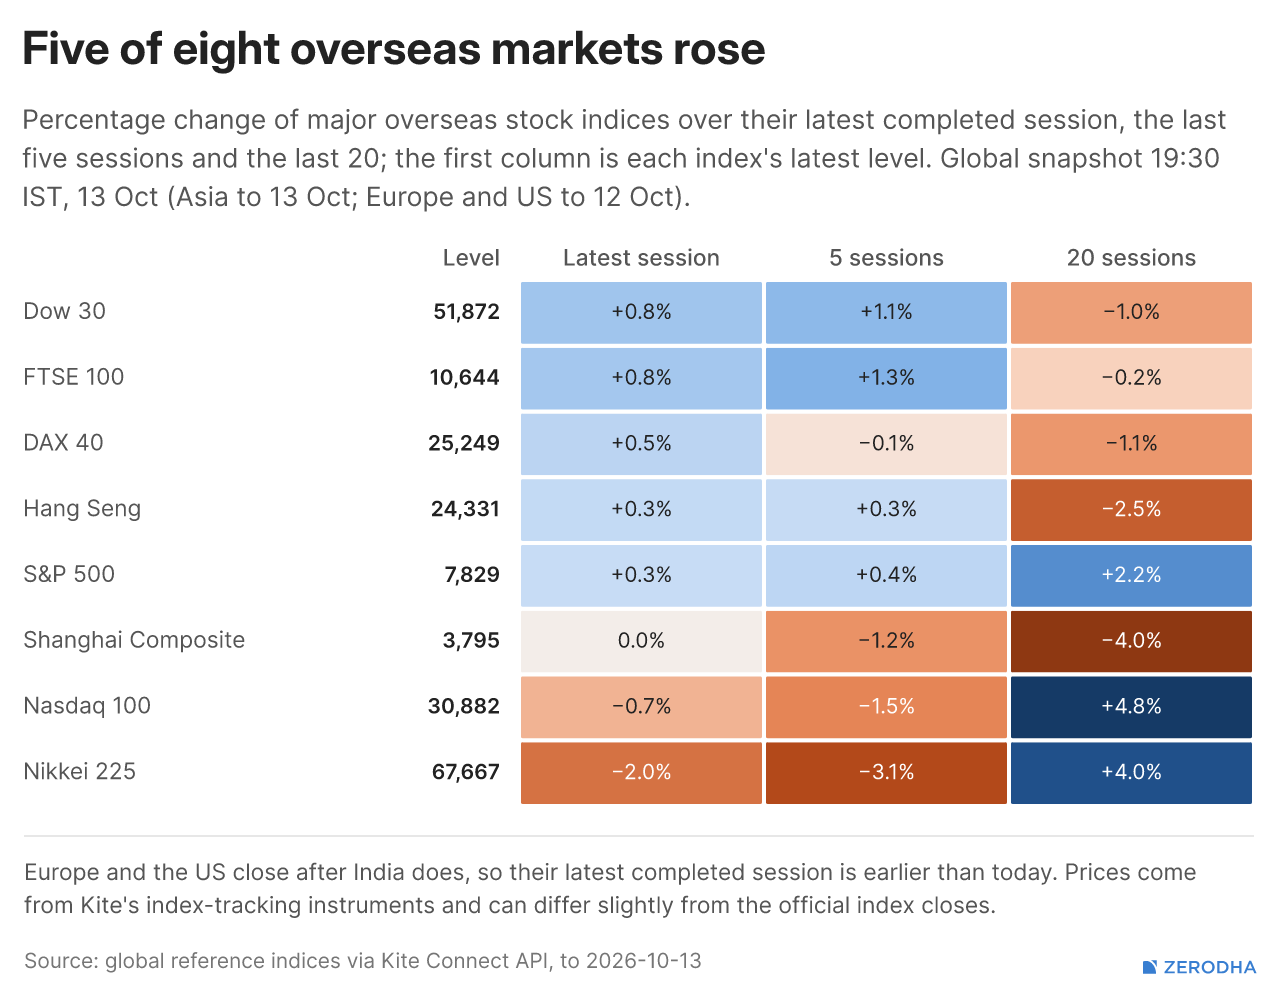
Global Markets
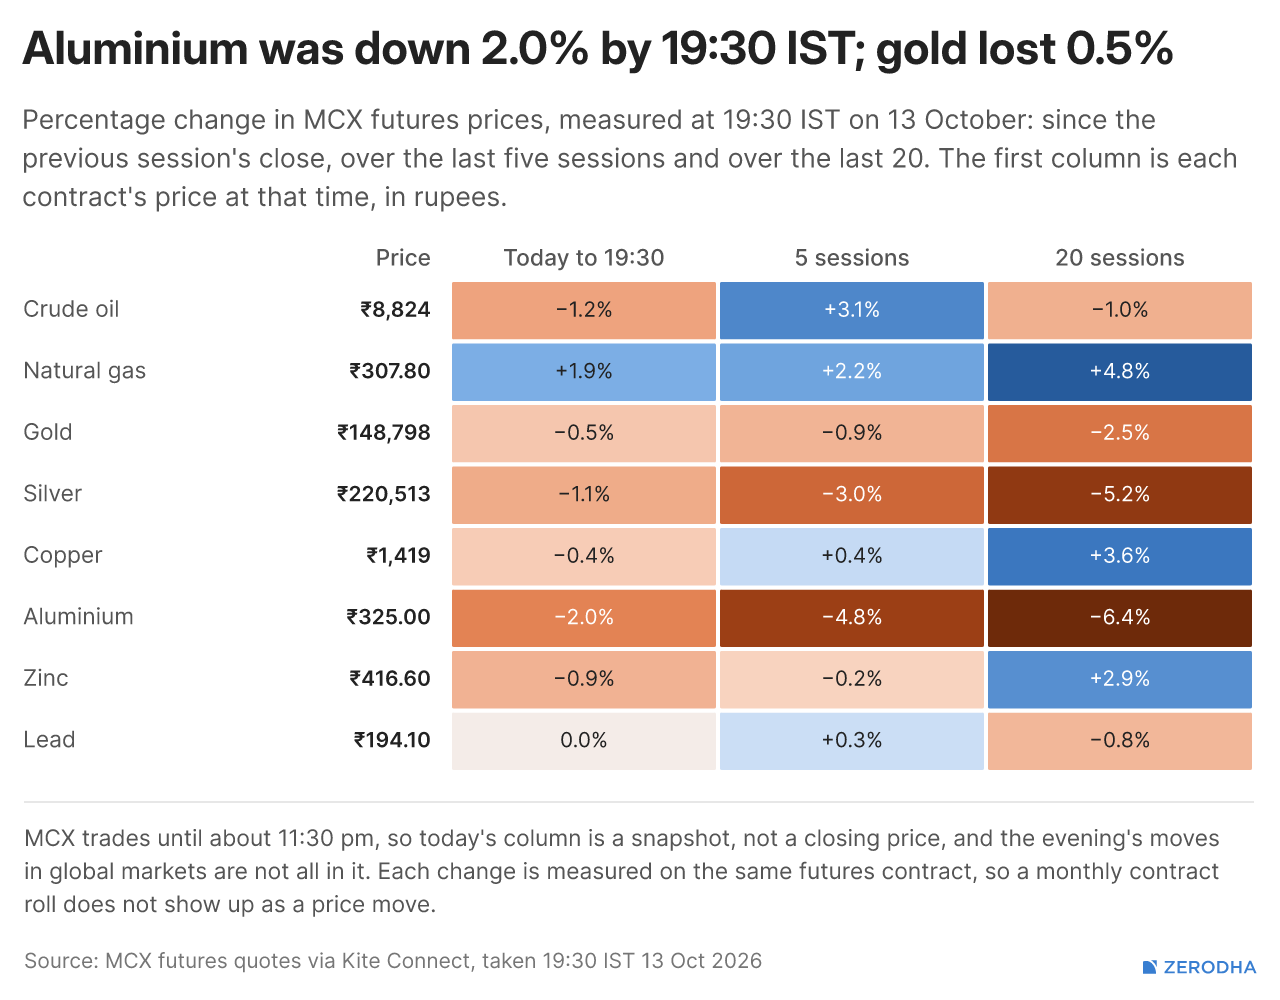
Commodities
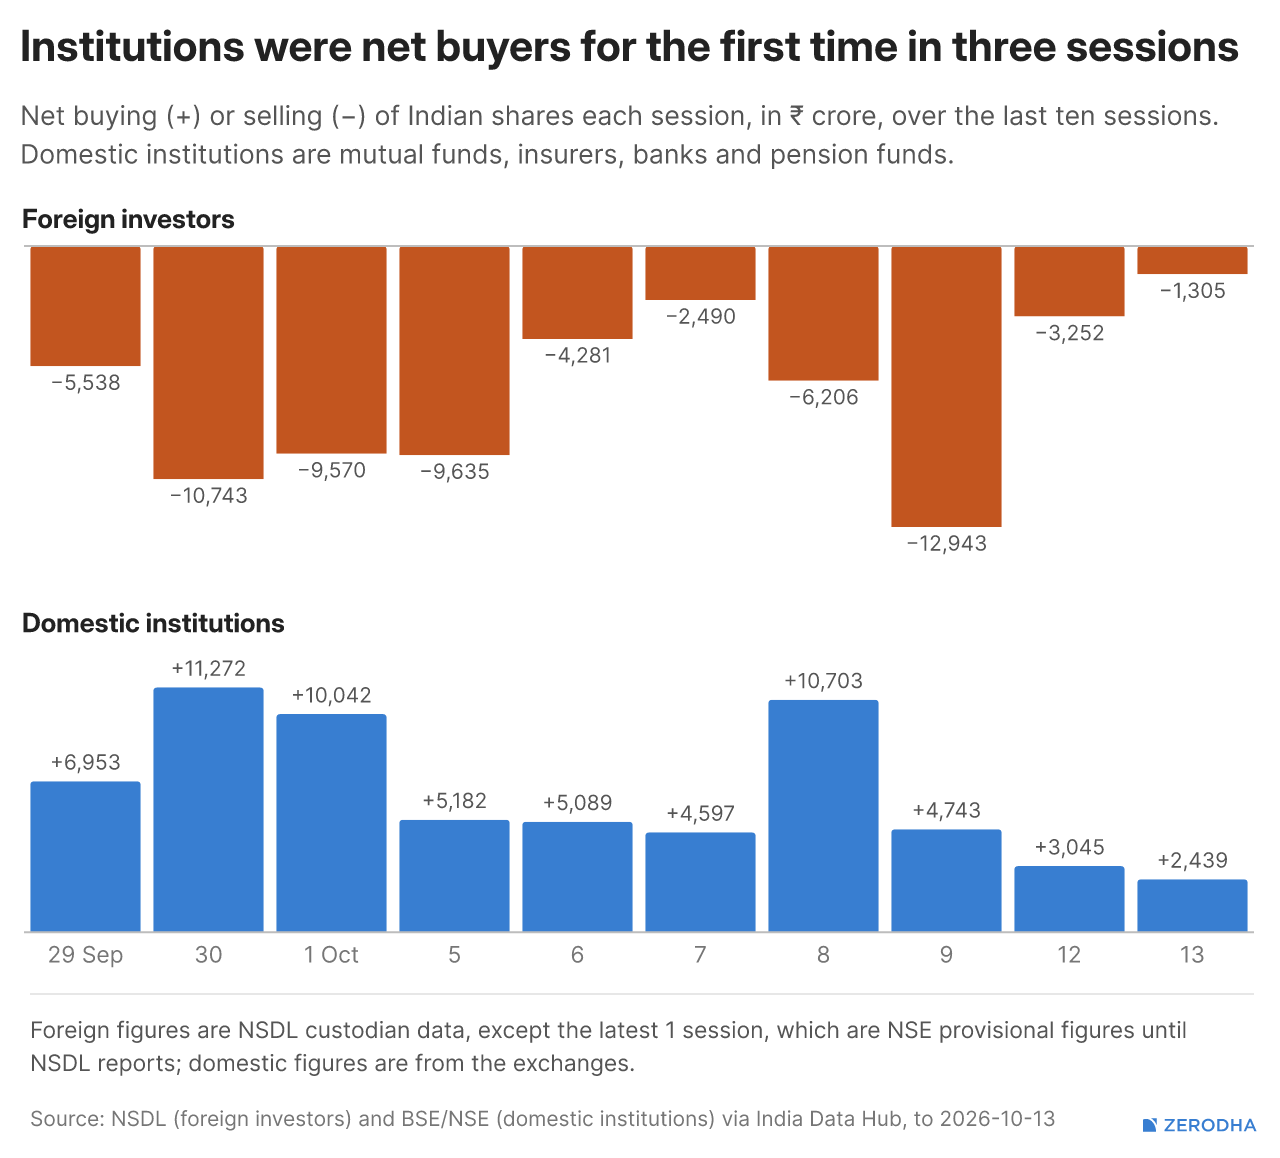
Institutional Flows & Participant Positioning
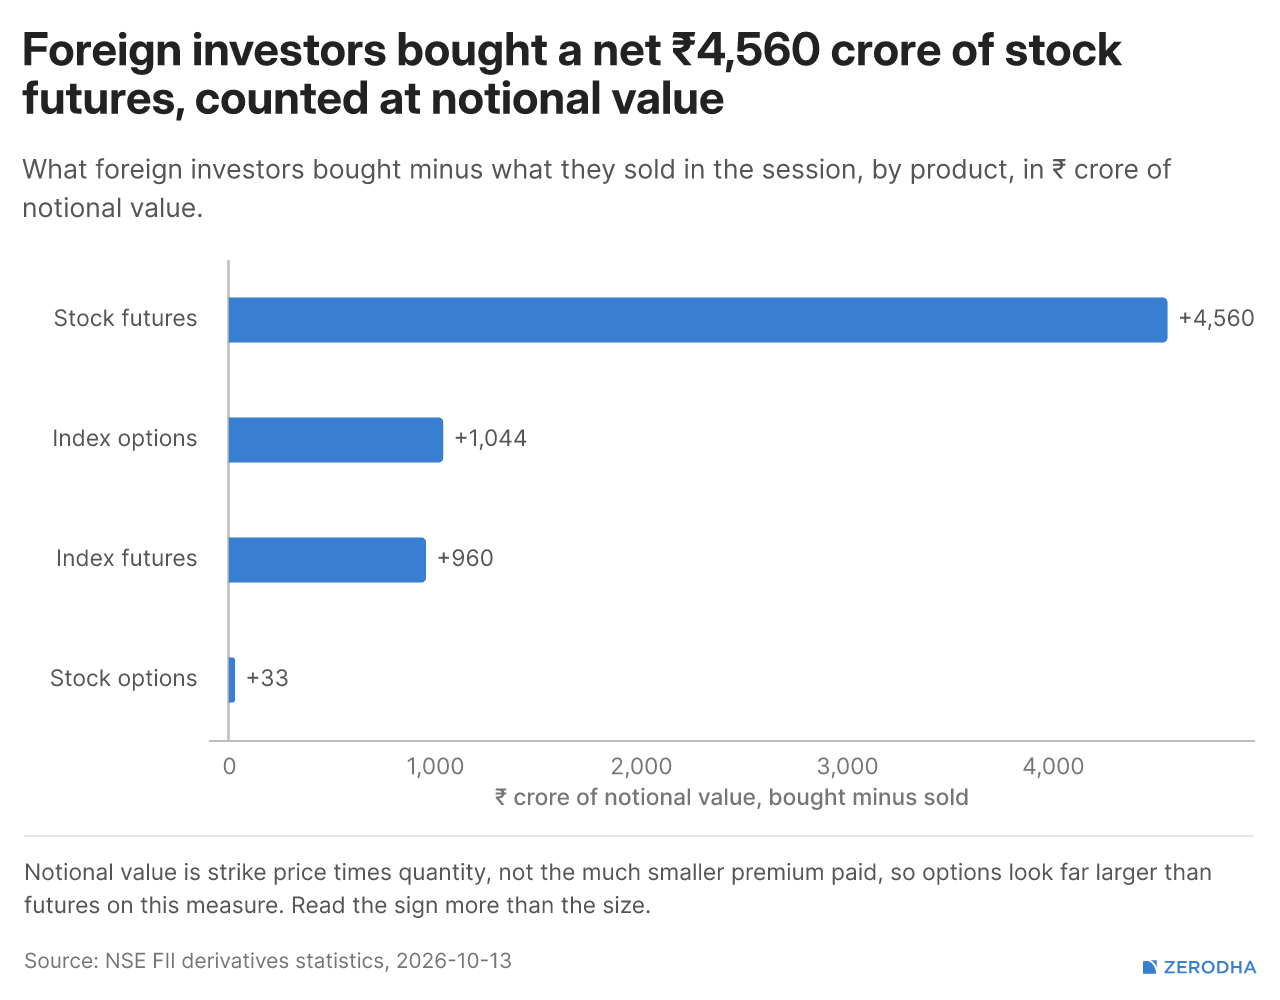
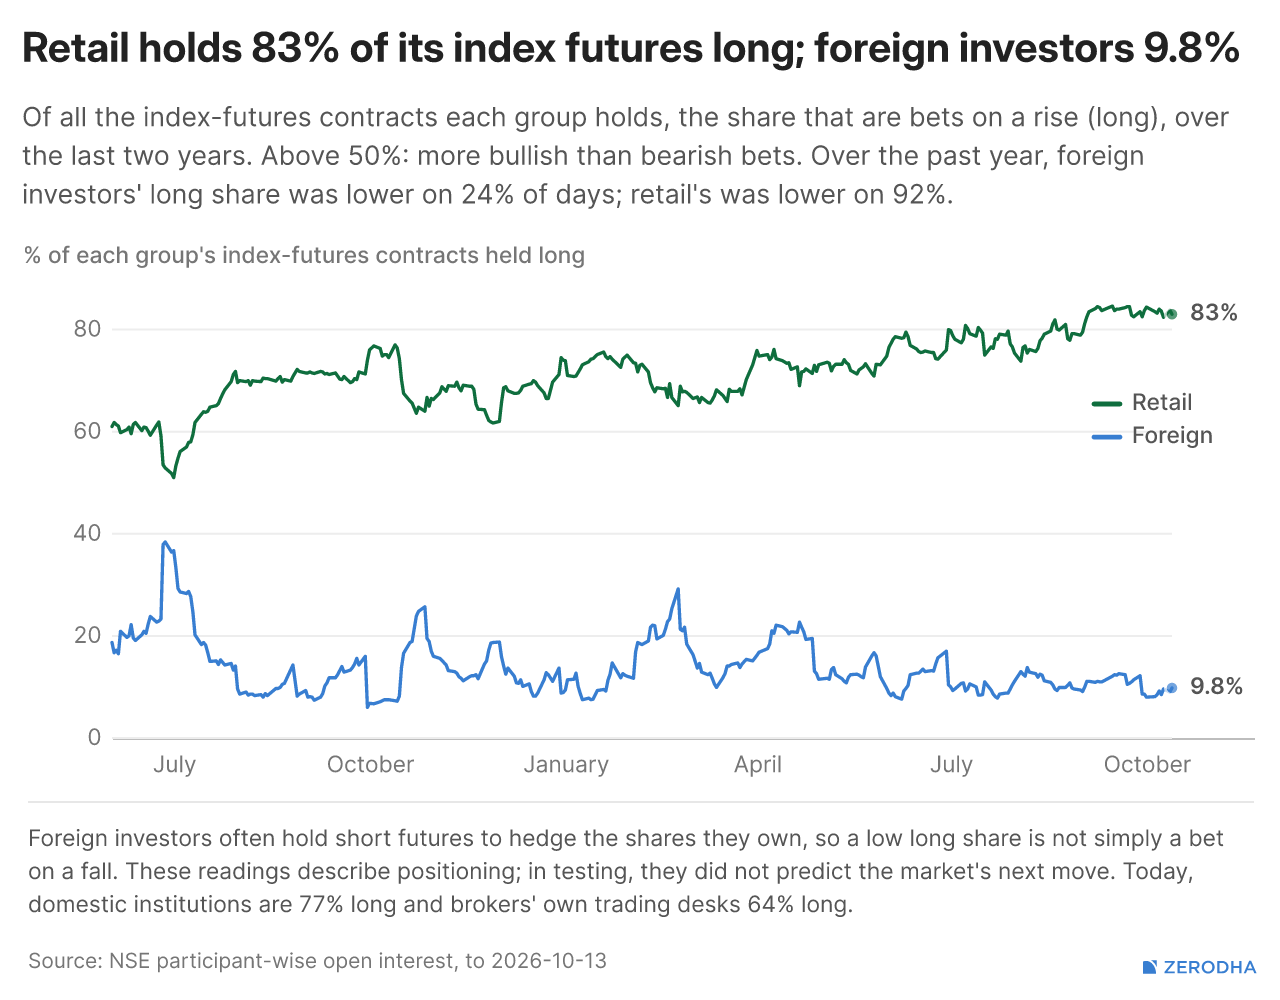
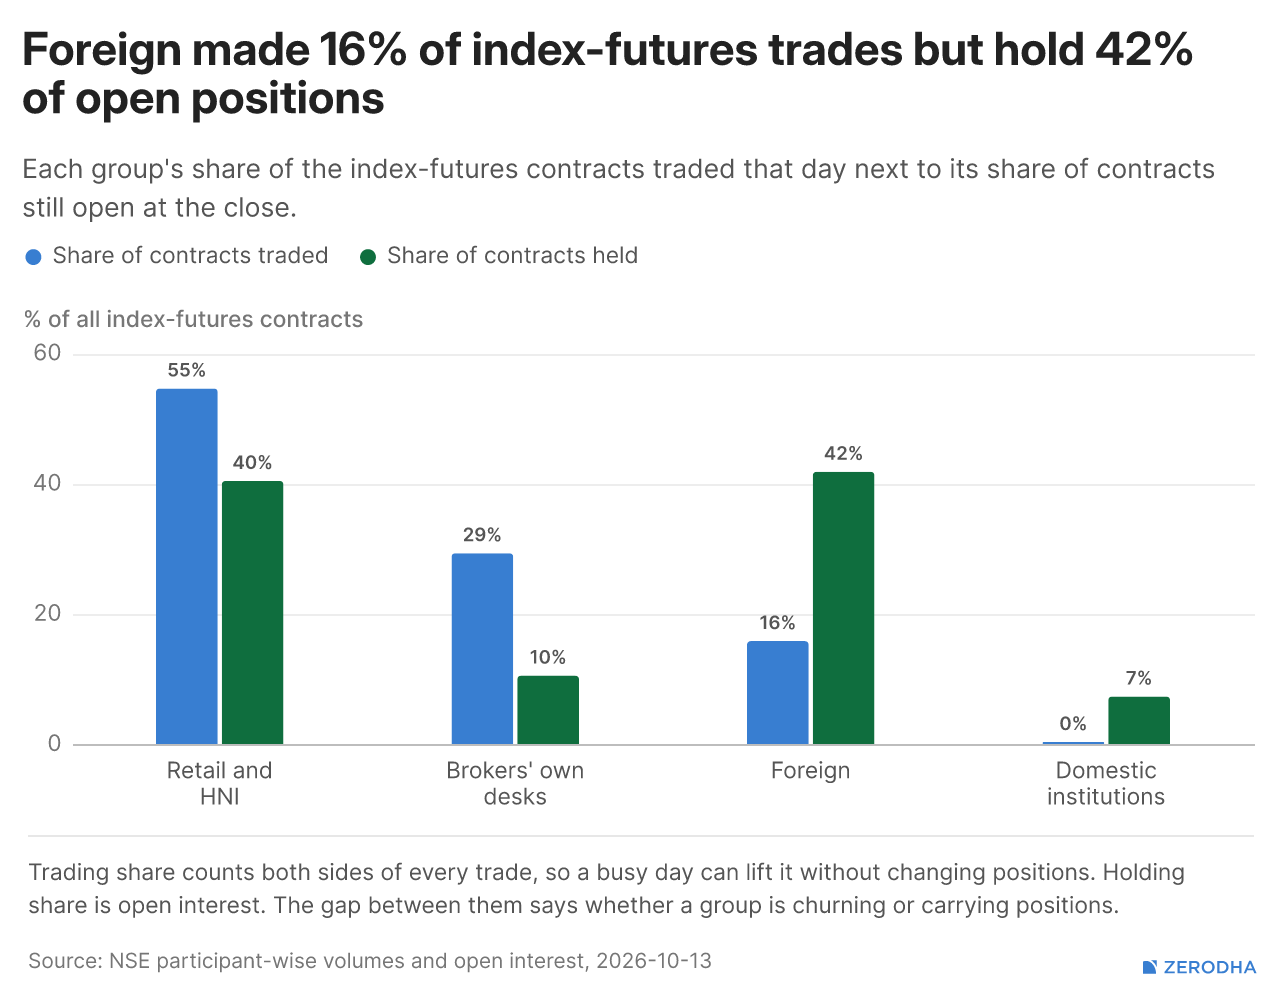
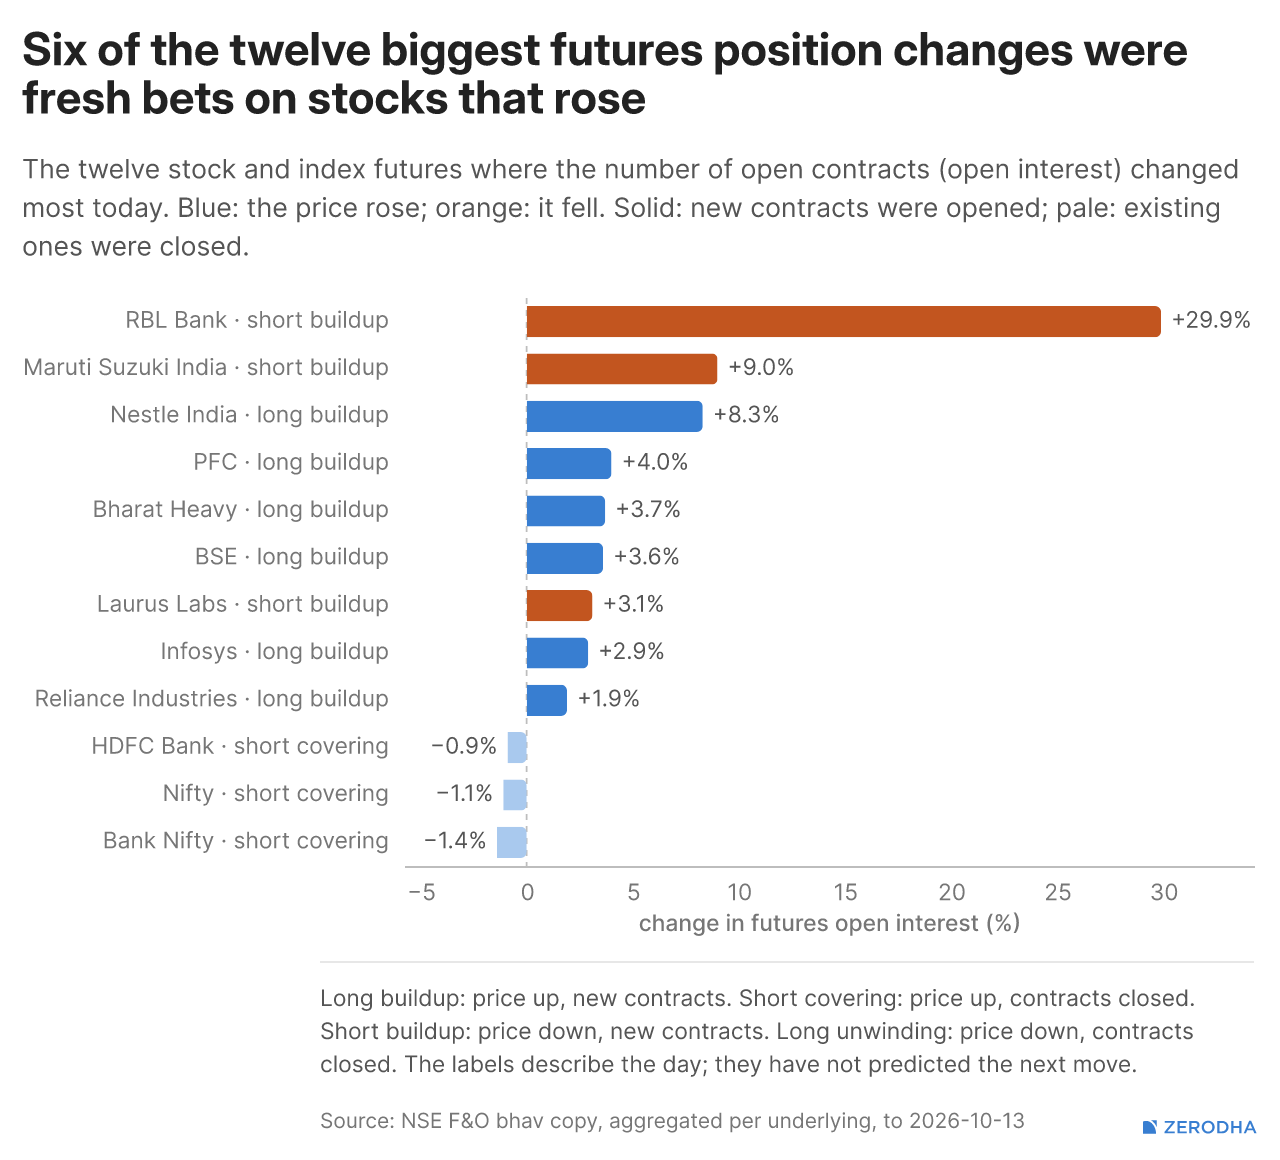
Put writing strengthened, lifting the PCR from 0.73 to 1.27, while implied volatility fell from 14.6% to 12.6%. FIIs remain heavily bearish with just 9.8% of index-futures positions long, against 83% for retail and HNIs; six of the 12 largest stock-futures OI moves were long buildups.
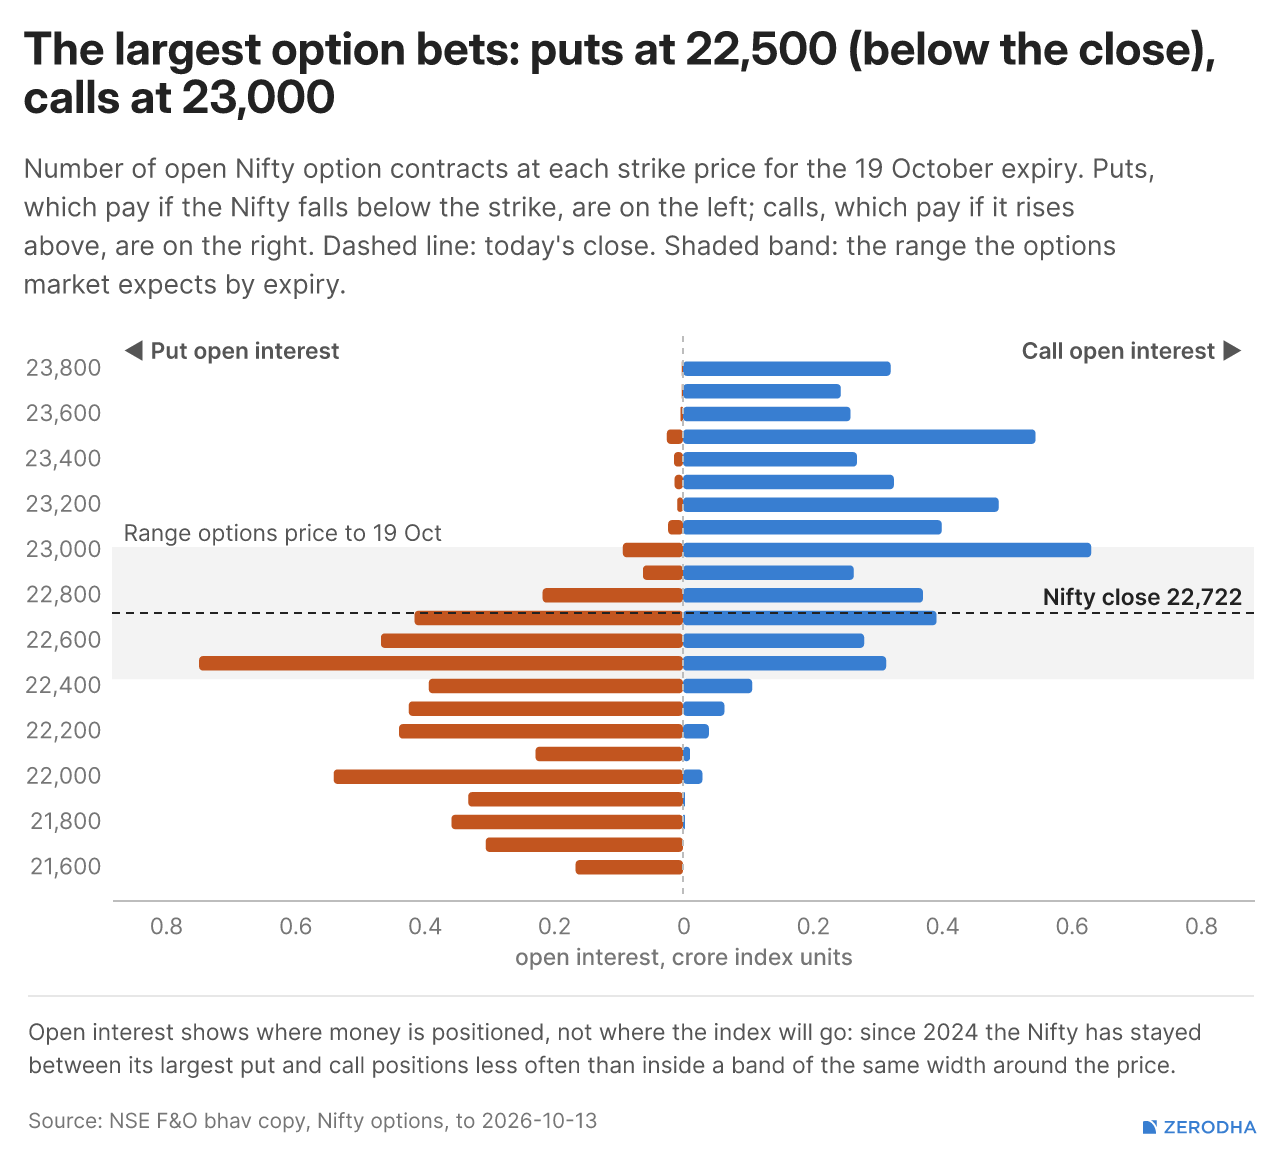
Options imply a 22,516–23,102 range into October 19 expiry, with the heaviest put OI at 22,500 and call OI at 23,000. The 20-day moving average at 22,882 remains the first major trend hurdle.
Thematic Indices
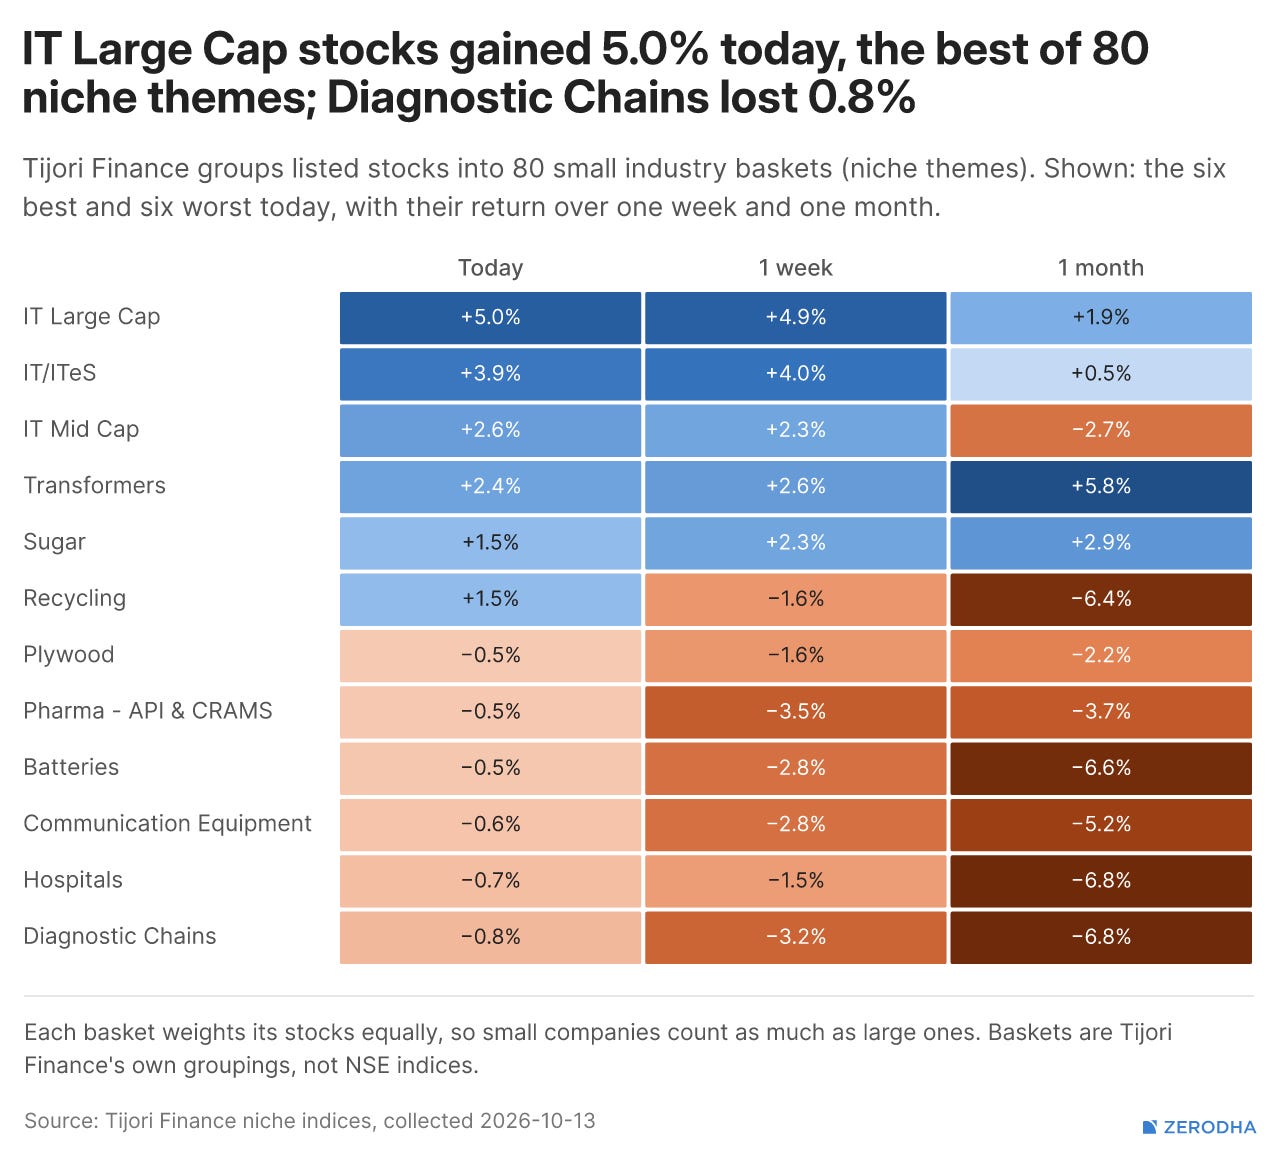
Tijori’s niche indices, where today’s move sorts pockets of the market beyond standard sector baskets. You can also track promoter buying and other interesting stuff, like Capex activity by the companies in the Tijori App’s idea dashboard
F&O Corner

Top Stories in India
NPCI deferred the implementation of merchant discount rate (MDR) charges on select UPI transactions until after Diwali. The levy was originally scheduled for October 15, with a revised date to be announced later. Dive deeper
Tata Elxsi reported a 10% YoY rise in Q2 FY27 net profit to ₹170 crore, while revenue grew 15% to ₹1,056 crore. Higher employee and operating costs kept profit growth below revenue growth. Dive deeper
Sun Pharma’s board approved a proposal to raise up to ₹10,000 crore through non-convertible debentures (NCDs). Dive deeper
ICICI Life Insurance reported a 25% YoY rise in Q2 FY27 net profit to ₹374 crore, supported by higher premium income. Net premium earned grew 16.5% to ₹13,804 crore. Dive deeper
SEBI extended its relaxation allowing companies to revise IPO fresh issue sizes by up to 50% without filing new draft offer documents until March 31, 2027, subject to specified conditions. Dive deeper
Top Stories Globally
South Korea’s Kospi plunged 7.4% to its lowest level since July, dragged down by a sharp sell-off in semiconductor stocks. Samsung Electronics fell 7.7% and SK Hynix dropped 8.8% amid concerns that advances by Chinese chipmaker CXMT could intensify competition in the global memory chip market. Dive deeper
Crude oil fell below $92 per barrel, snapping a three-session rally as the US temporarily eased restrictions on Russian diesel exports for six months, raising expectations of additional global energy supplies. Dive deeper
OPEC+ crude oil production rose by around 900,000 barrels per day to 39.07 million bpd in September, driven largely by higher Saudi Arabian output despite continued disruptions in the Strait of Hormuz. Dive deeper
The dollar index fell 0.3% to 102.26, retreating from an 18-month high of 102.61 as oil prices eased and investors reassessed geopolitical risks ahead of the US midterm elections. Dive deeper
The IMF raised its 2026 global growth forecast to 3.1% from 3%, with growth expected to accelerate to 3.4% in 2027. Resilient advanced economies and rising AI investment supported the upgrade, although elevated energy prices remain a key risk. Dive deeper
Management Chatter
In this section, we highlight interesting comments from management at major companies and from policymakers in the Indian and Global Economies.
FM Nirmala Sitharaman says the government is open to hearing views on LTCG tax review:
“LTCG, a lot of people are commenting on it, both Indian and foreign investors. This debate on STT in the market and the question of treating all asset classes similarly, there is a lot of debate. It is healthy to have this debate.”
"We are very close to the Budget and the preparation for the Budget has started, and it may not be the best time for me to say what I will or what I will not consider" - Link
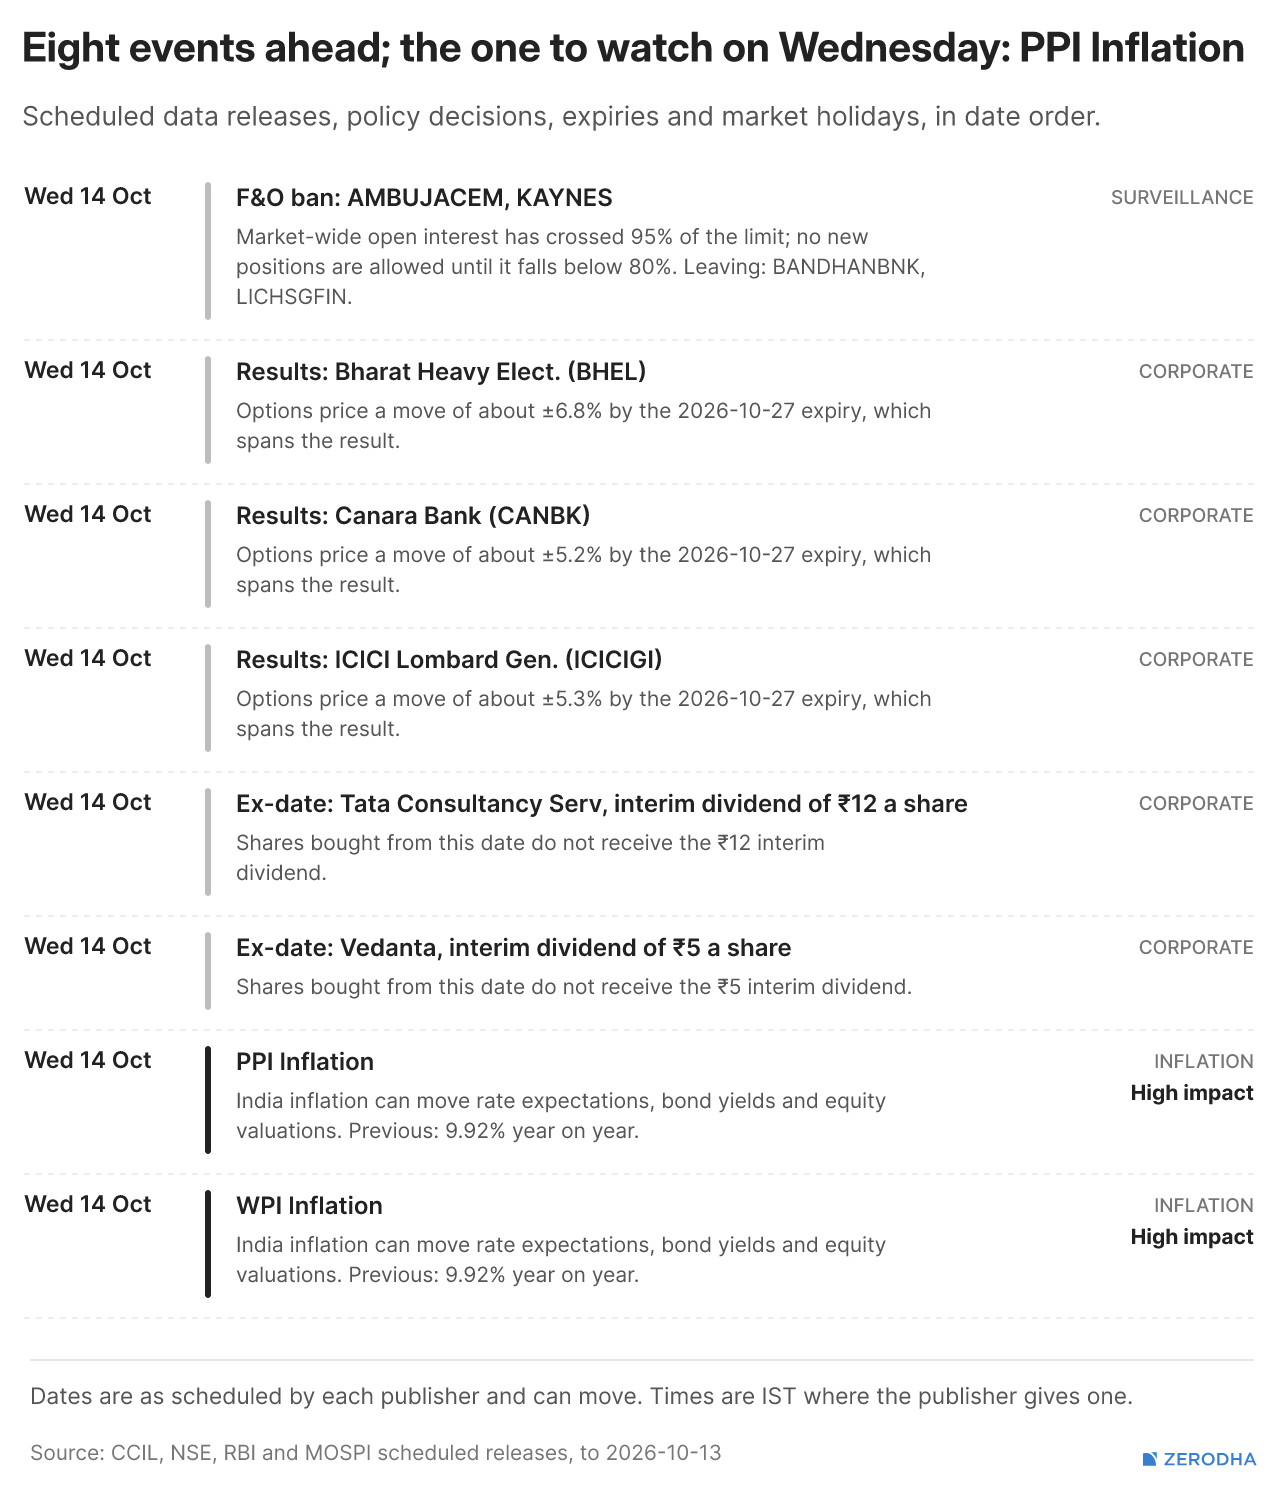
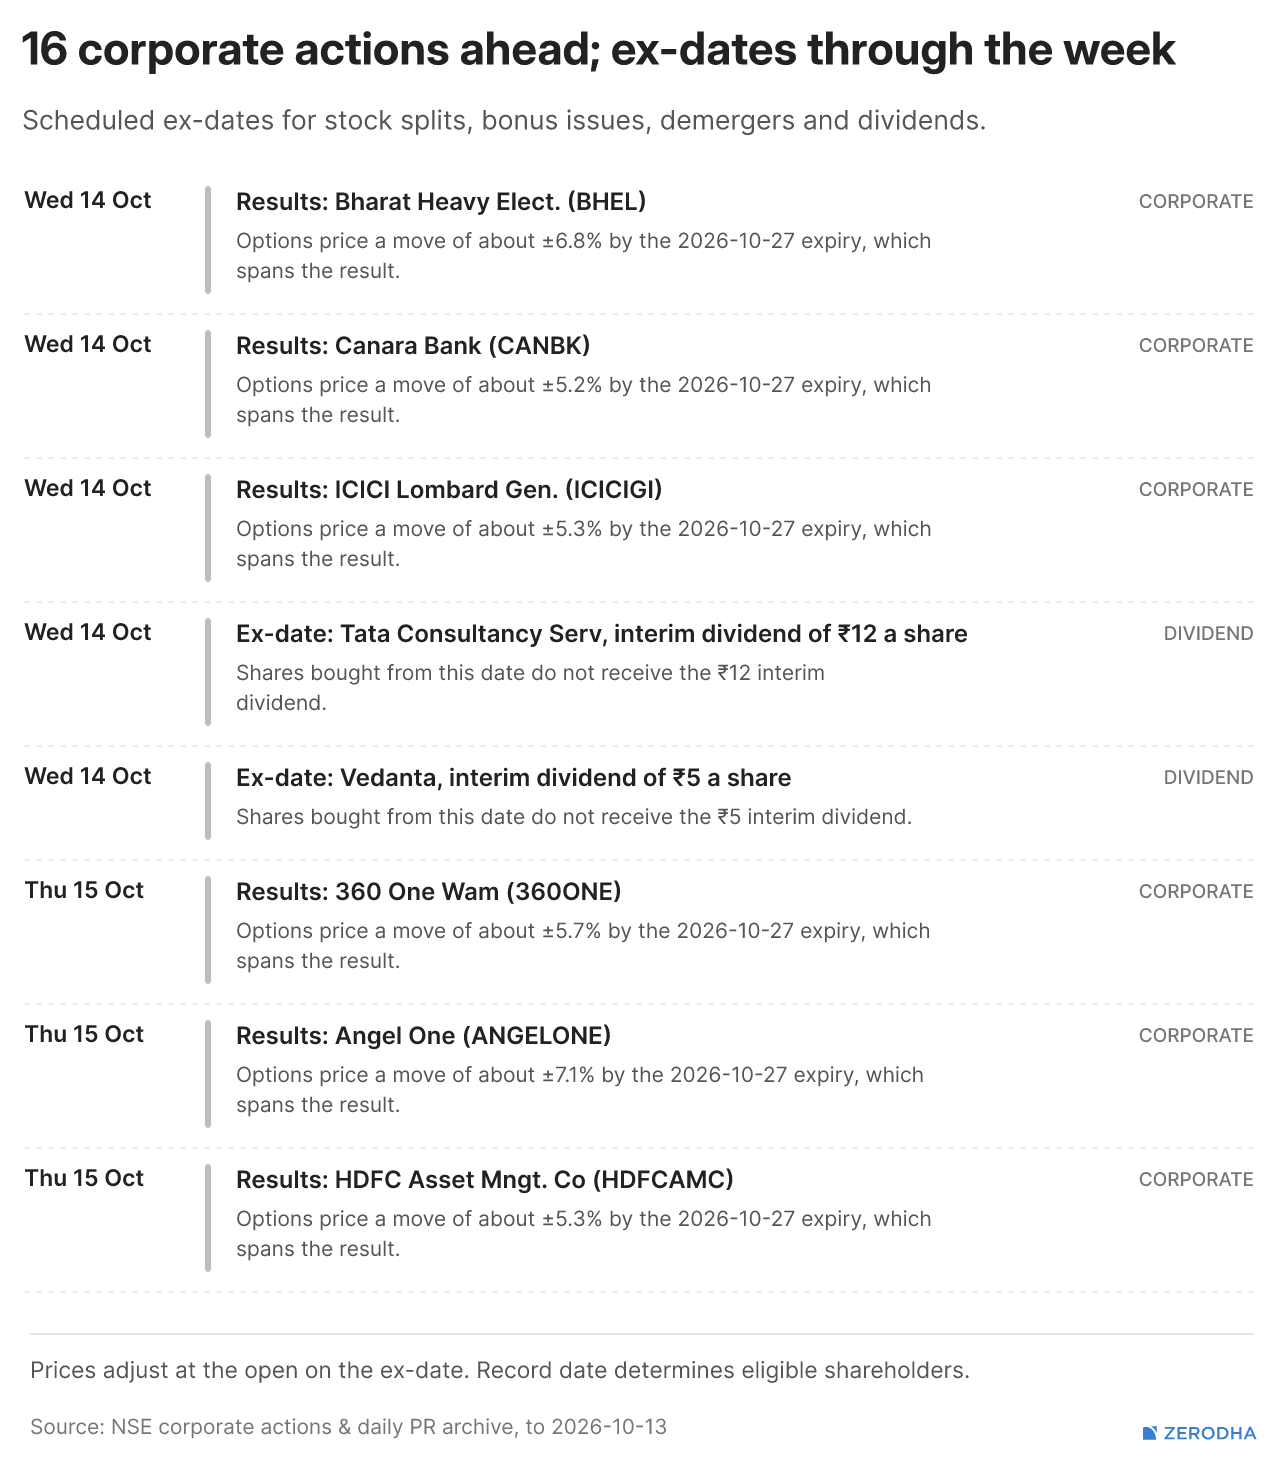
The week ahead & Corporate Actions
Corporate Actions
Published by Zerodha. Not investment advice. Data from NSE, BSE, and MCX.
In our latest episode of In The Money by Zerodha, we explore the story of Paul Tudor Jones, the legendary macro trader known for his approach to risk management and his role during the 1987 stock market crash.
From an early career setback in cotton trading to the lessons he took away from Silver Thursday, we look at the experiences that shaped his trading philosophy.
How did Jones approach risk? What did he learn from his early losses? And what can his career teach us about surviving the markets over the long run?
That’s it from us for today. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!
Clean I like it
Also put Stock related major news
Like did before