
Welcome to the weekly edition of Aftermarket Report, where we wrap up the week in the markets and take you through everything that mattered, both in India and globally.
What data points and transformations do you want to see?
We’re also experimenting with a weekly edition of the Aftermarket Report, and we’d love to know what you’d find useful in it.
Unlike the daily report, the idea here is to step back from individual trading sessions and look at the bigger picture — what changed over the week, where trends are building, how sectors and themes are moving, how positioning has shifted, and what the data tells us when viewed over a longer timeframe.
We’re exploring everything from weekly market breadth, sector and thematic trends, F&O positioning and flows to volatility, commodities, global markets, and more. But we want to know what you would like to track.
What data points, transformations, ratios, comparisons, charts, or indicators would make a weekly market wrap genuinely useful for you?
Tell us what you’d like to see. Your feedback will help us shape the weekly edition of the Aftermarket Report.
Weekly market performance
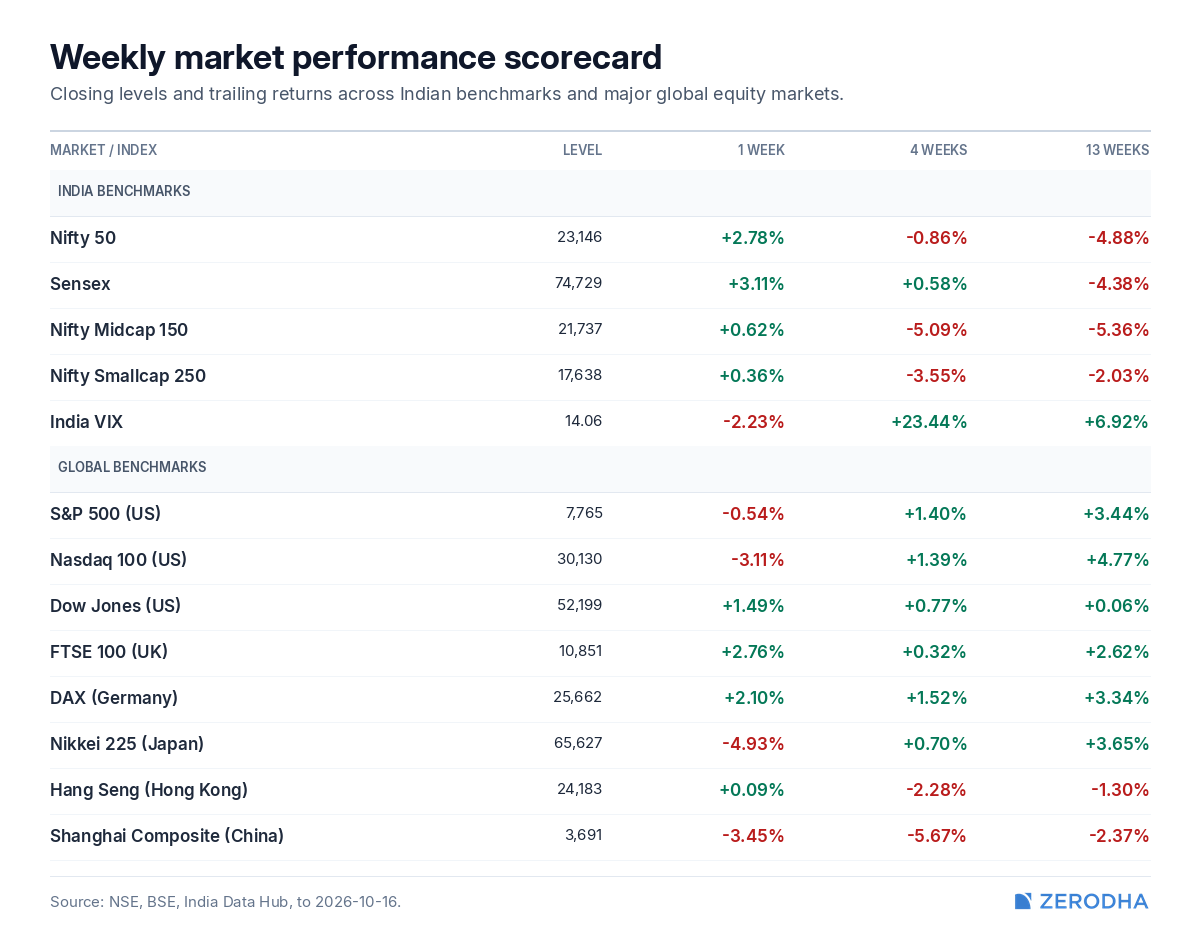
Nifty gained 2.78% to close at 23,146, recovering after its first positive week in nine weeks. However, the broader market remains in a downtrend, with weak participation, persistent foreign selling and elevated bond yields continuing to weigh on sentiment.
What is the macro backdrop doing?
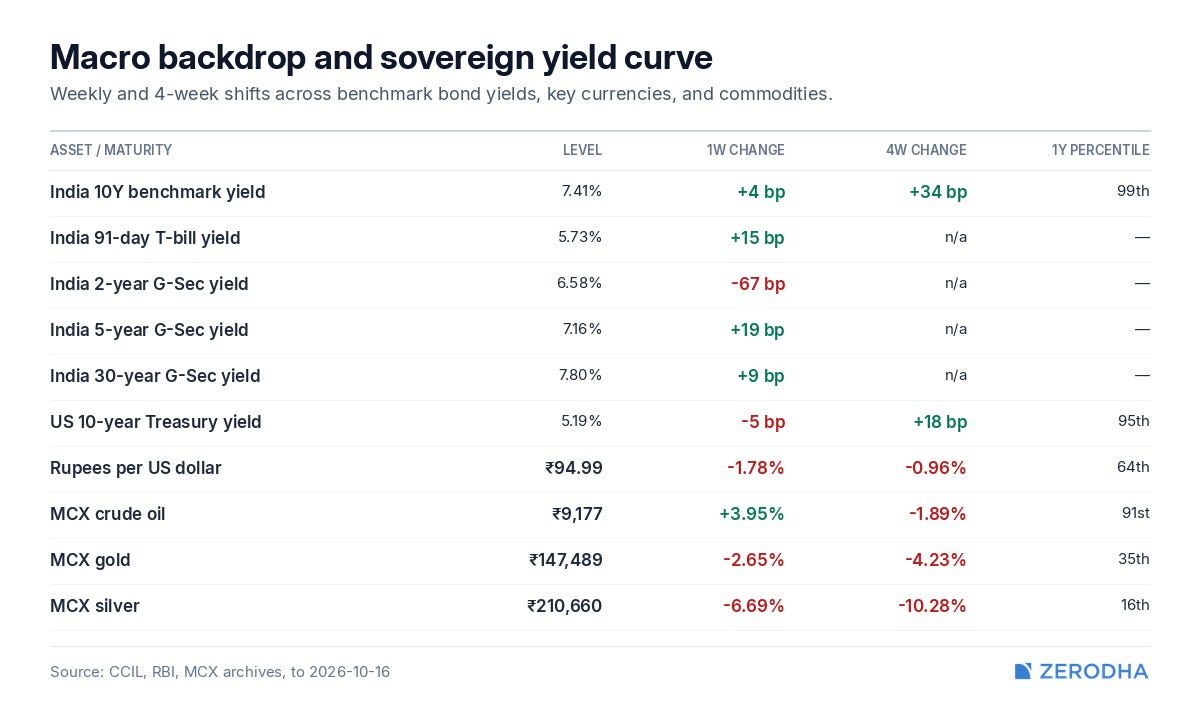
India’s 10-year government bond yield rose 4 bps to 7.41%, remaining near its highest levels in a year, while the rupee strengthened to ₹94.99 per dollar. Crude oil gained 3.95% during the week, while gold and silver fell 2.65% and 6.69%, respectively.
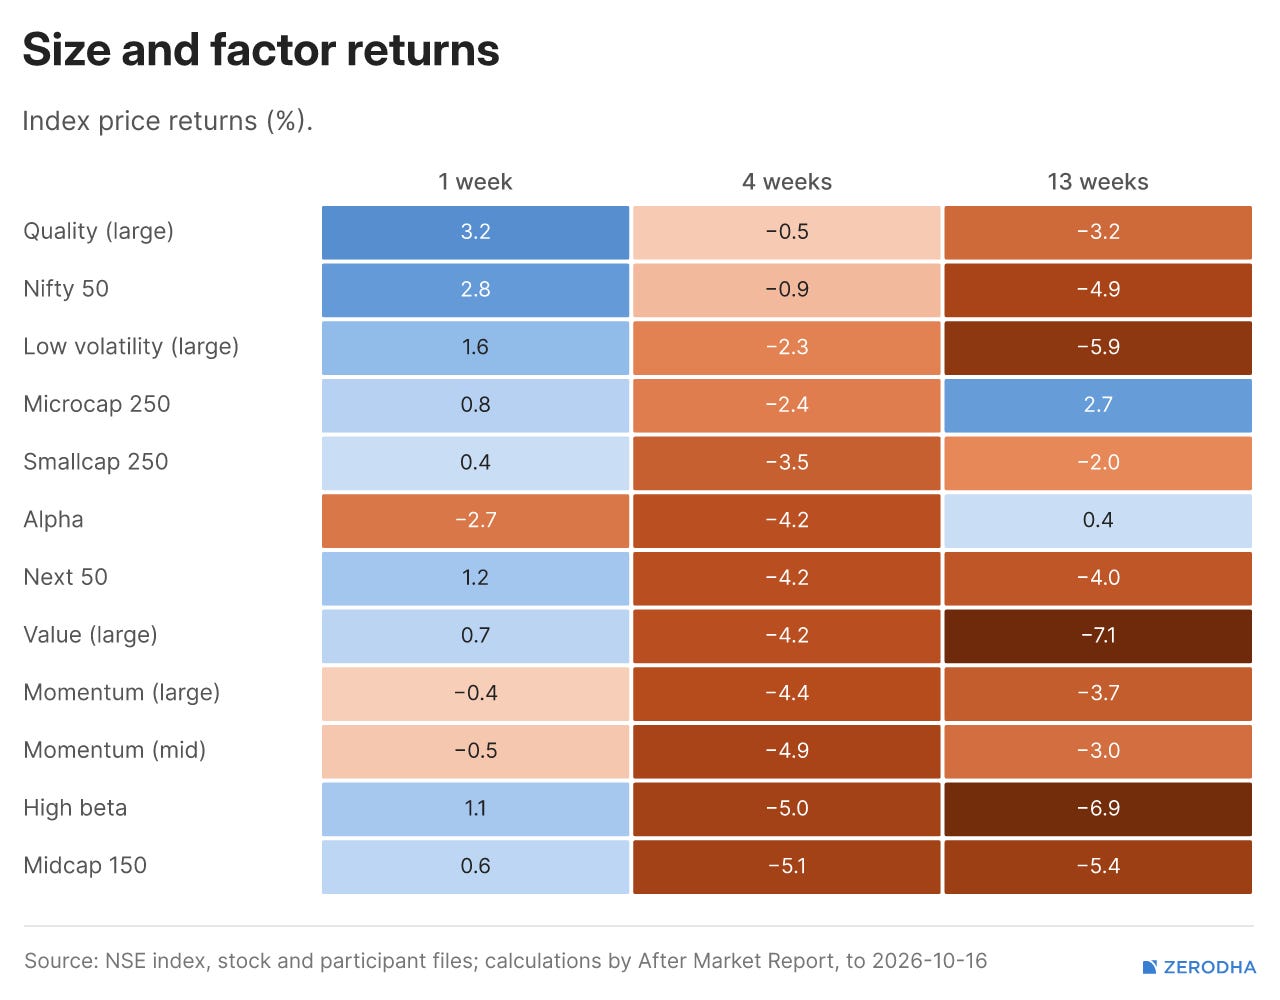
Reversal strategies outperformed momentum this week, with last week’s weakest stocks gaining a median 0.54%, compared with a 0.01% decline for the strongest stocks. However, momentum has still outperformed in nine of the last 13 weeks, while Quality stocks have held up better than High Beta stocks over four weeks.
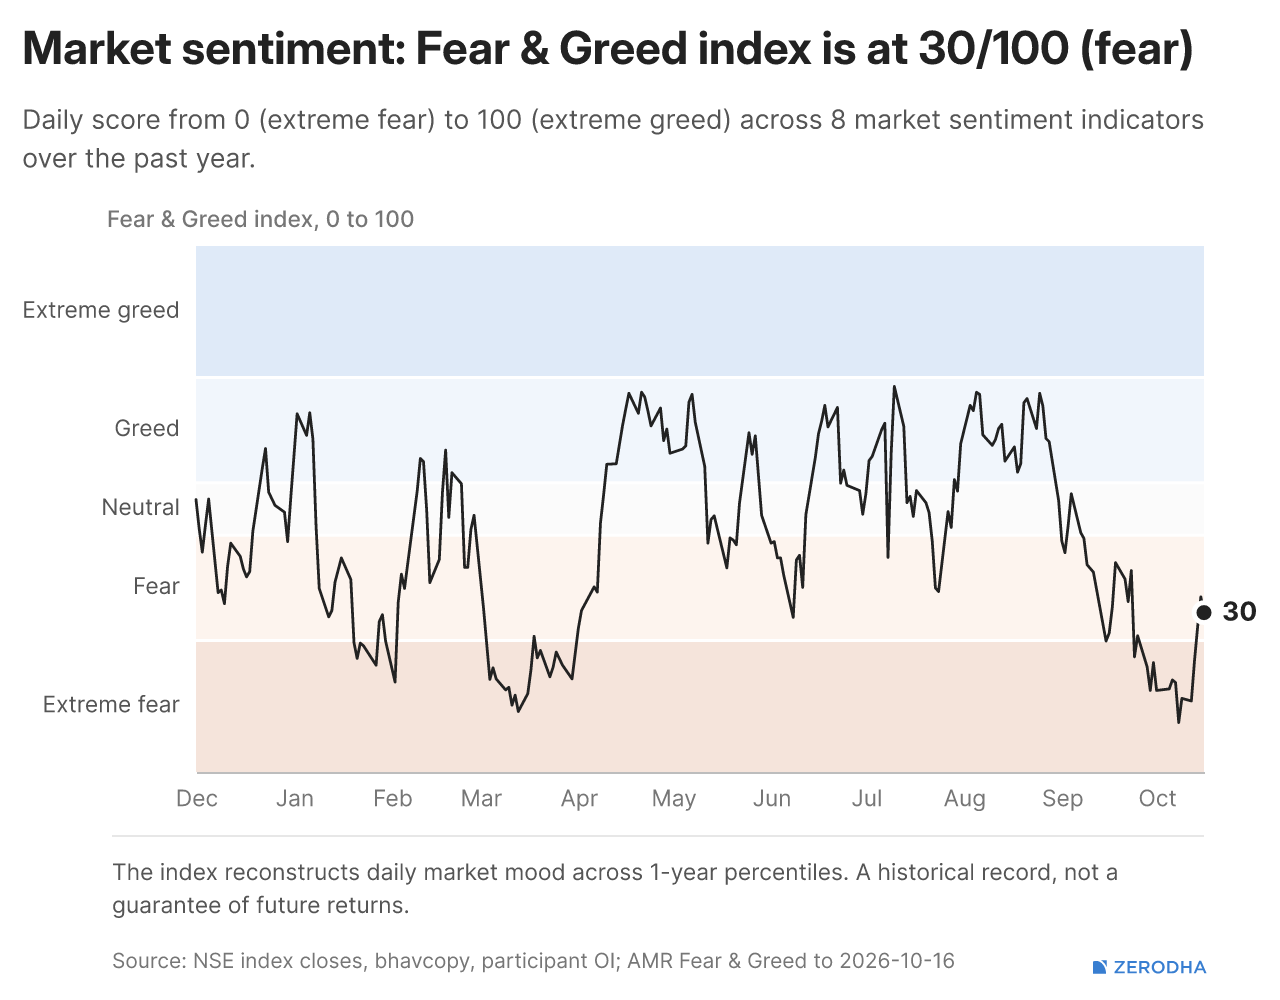
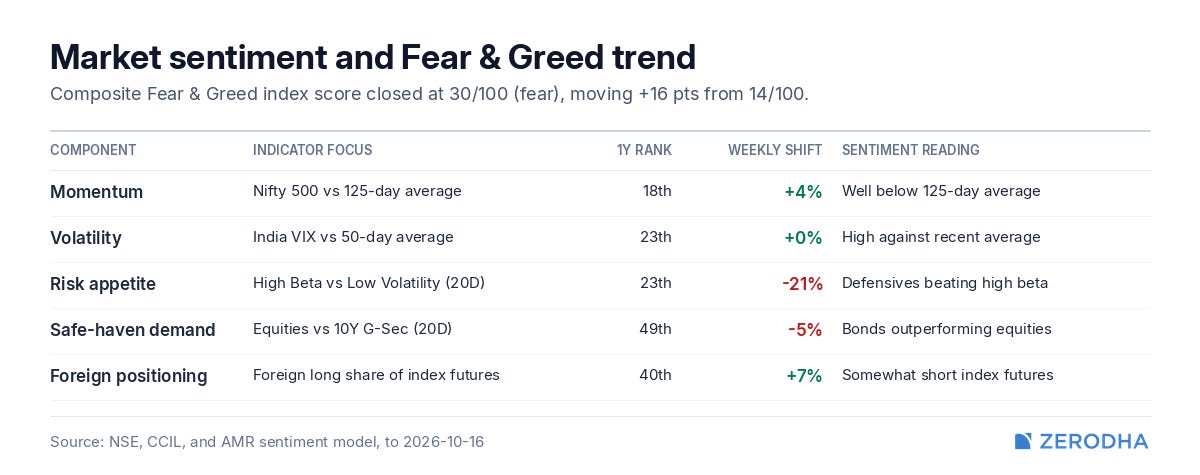
Fear & Greed trend
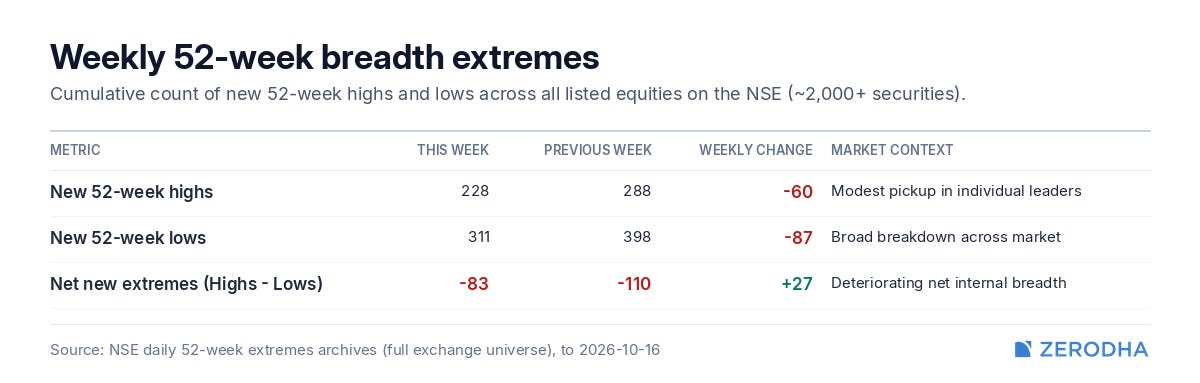
Market Breadth
Valuation Check
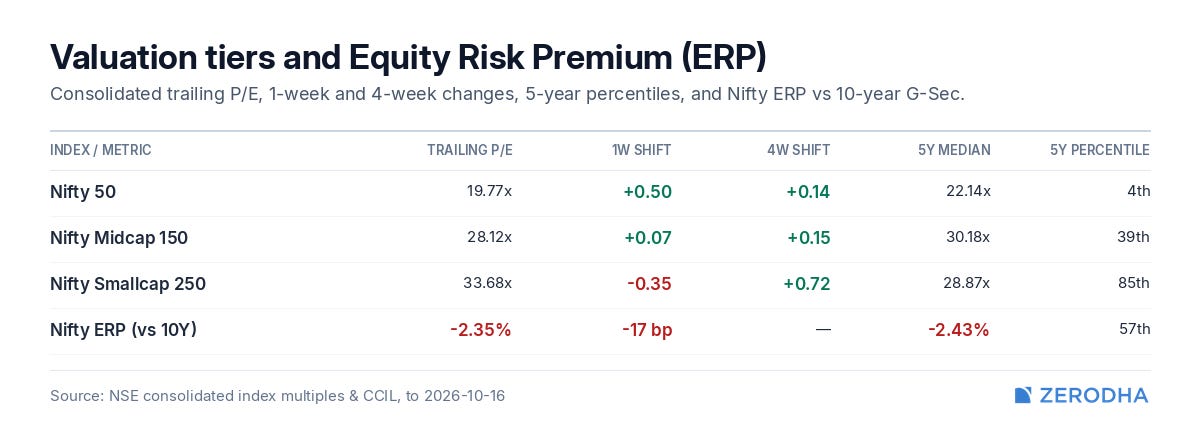
Nifty trades at 19.77× earnings, near its lowest valuation levels in five years, while smallcaps remain expensive at 33.68×. The equity risk premium stood at -2.35%, close to its five-year median of -2.43%, as rising bond yields continued to pressure relative equity valuations.
Sectoral summary
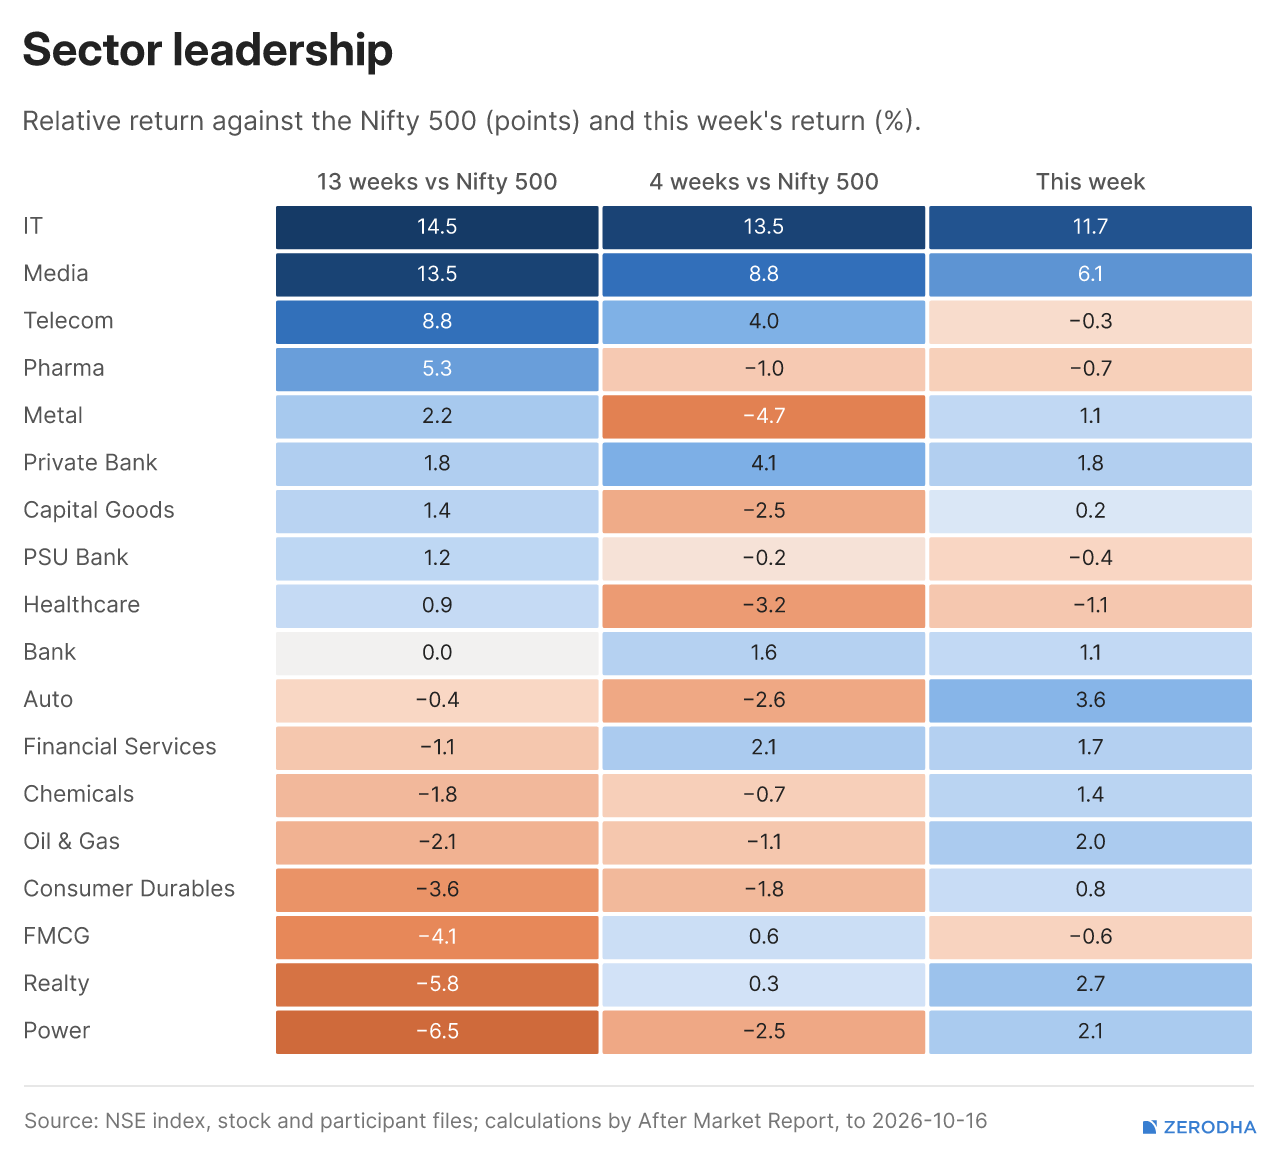
IT, Media, Telecom and Private Banks remain the strongest sectors relative to Nifty 500 over 13 weeks, with IT outperforming by 14.5 percentage points. Banks, Financial Services and FMCG are showing improvement, while Pharma, Metals and Capital Goods are losing momentum.
Selective stock screeners
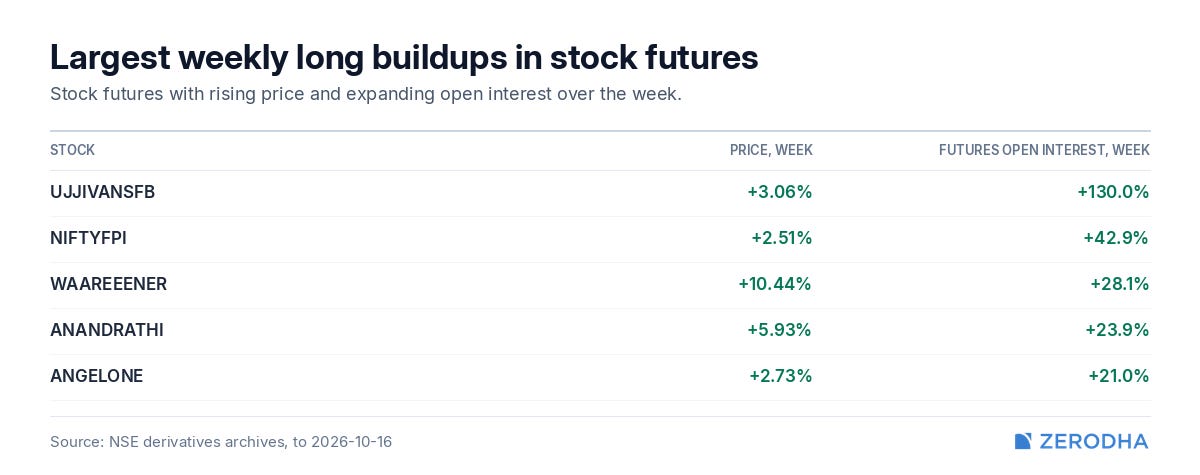
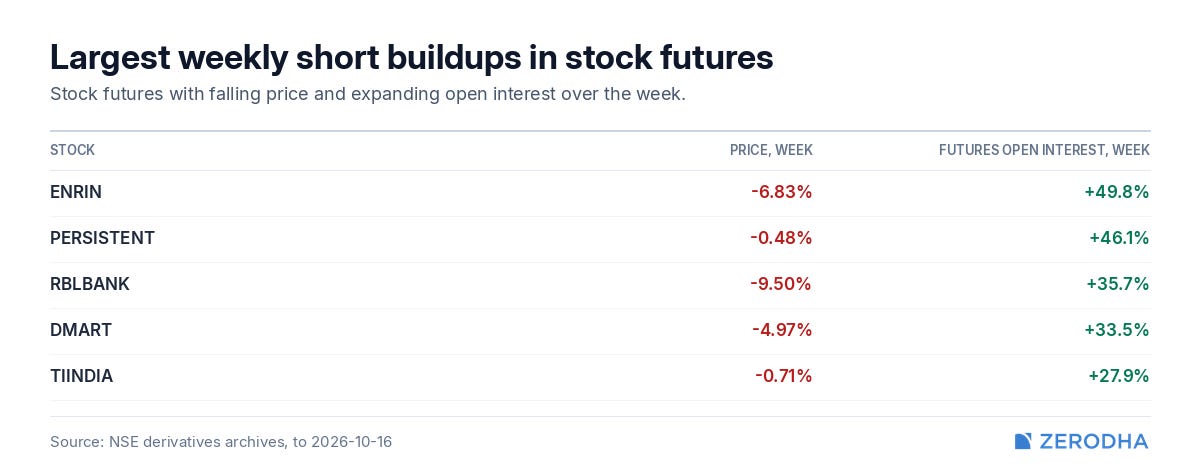
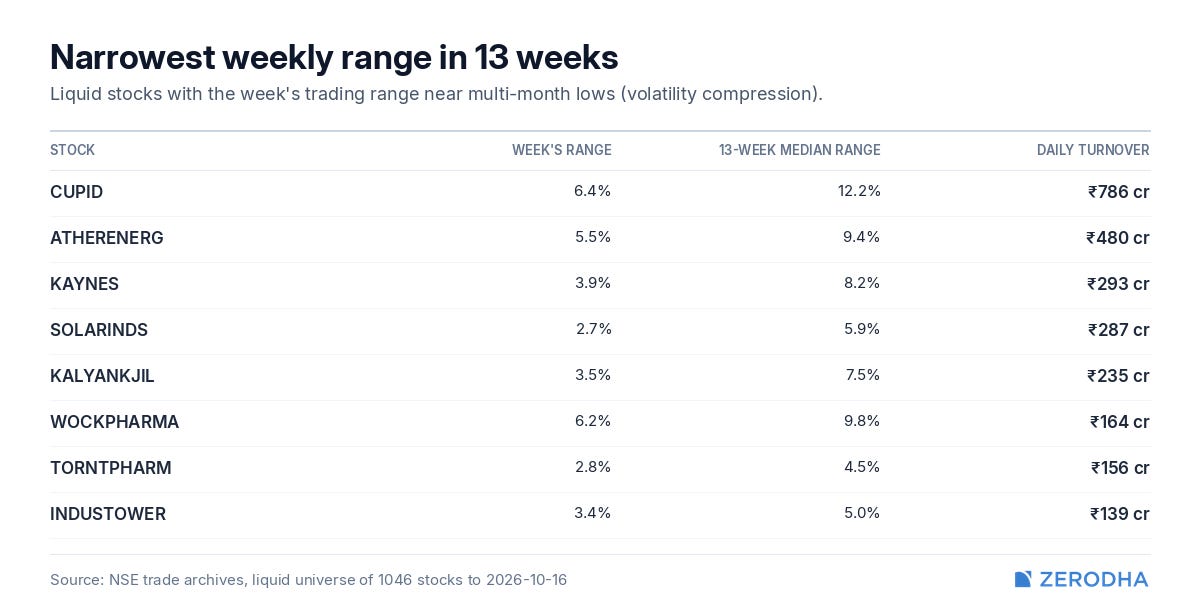
Deals of the week
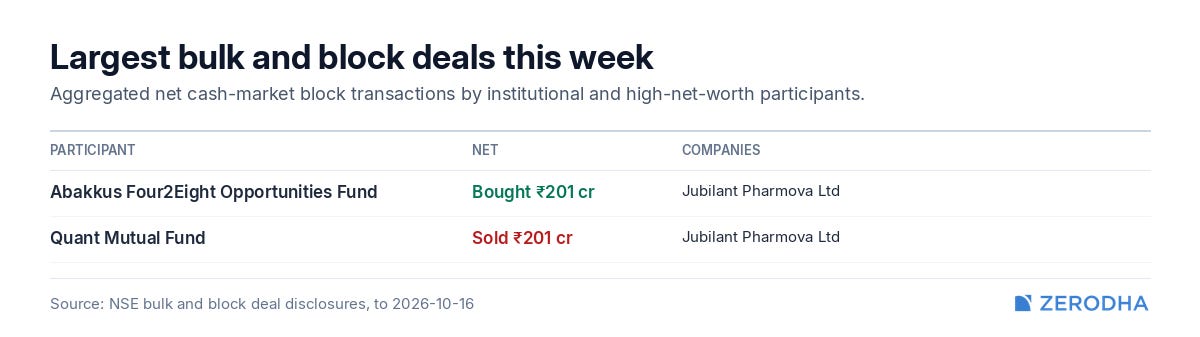
Institutional flows & positioning
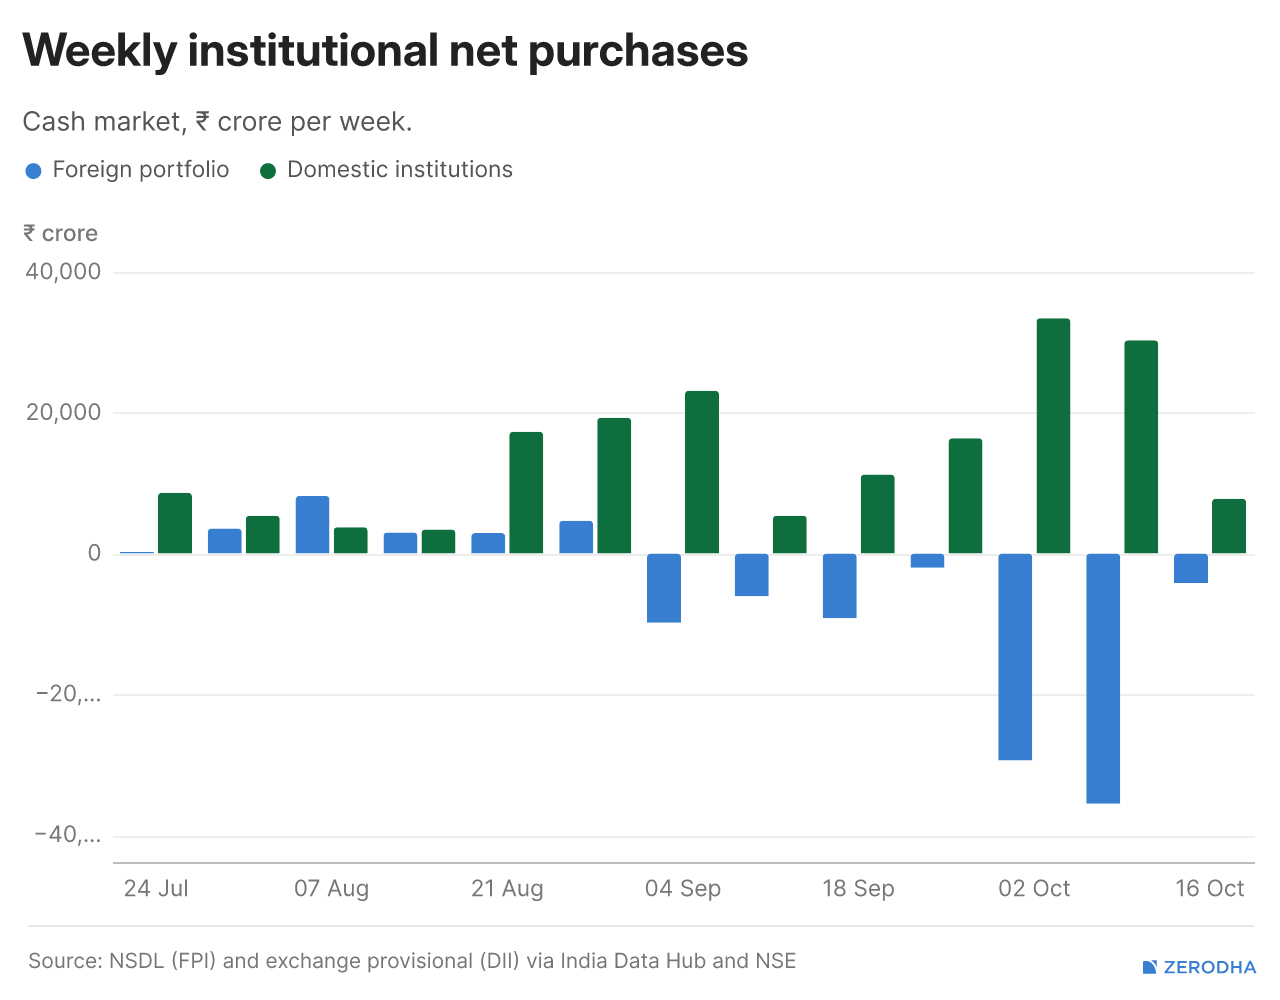
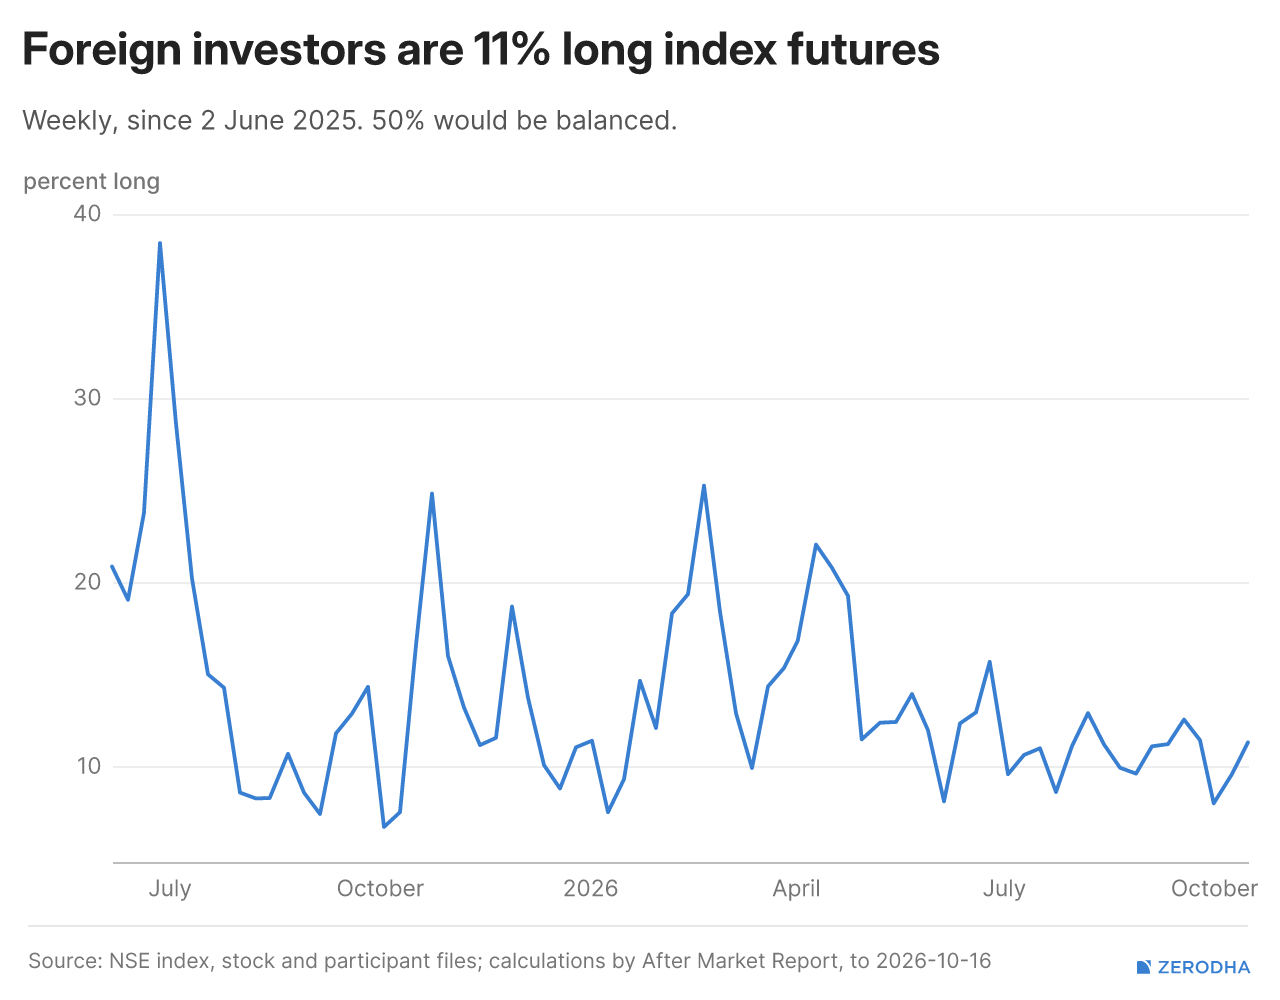
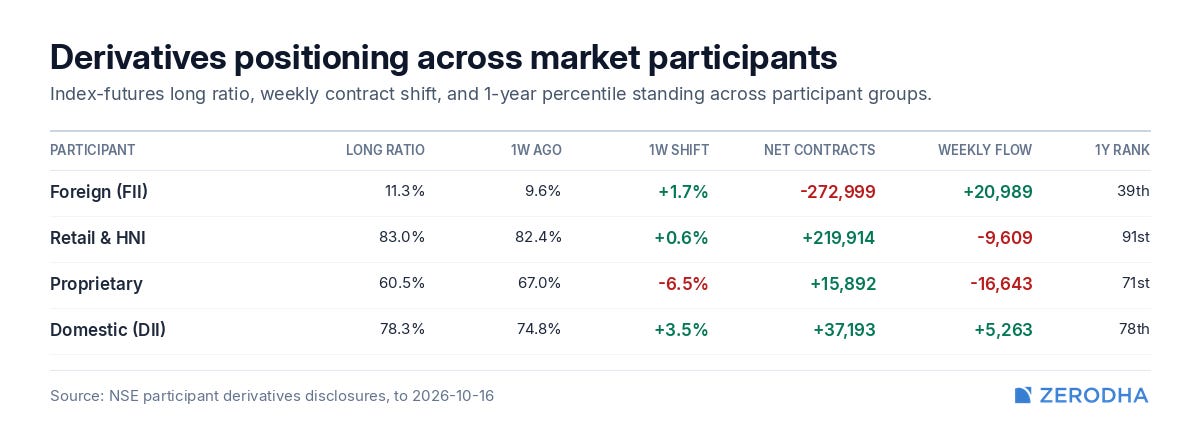
FPIs sold ₹4,187 crore during the week, while DIIs bought ₹7,813 crore, absorbing the foreign selling. Over four weeks, foreign outflows reached ₹71,172 crore against domestic inflows of ₹87,979 crore, highlighting continued dependence on domestic institutional support.
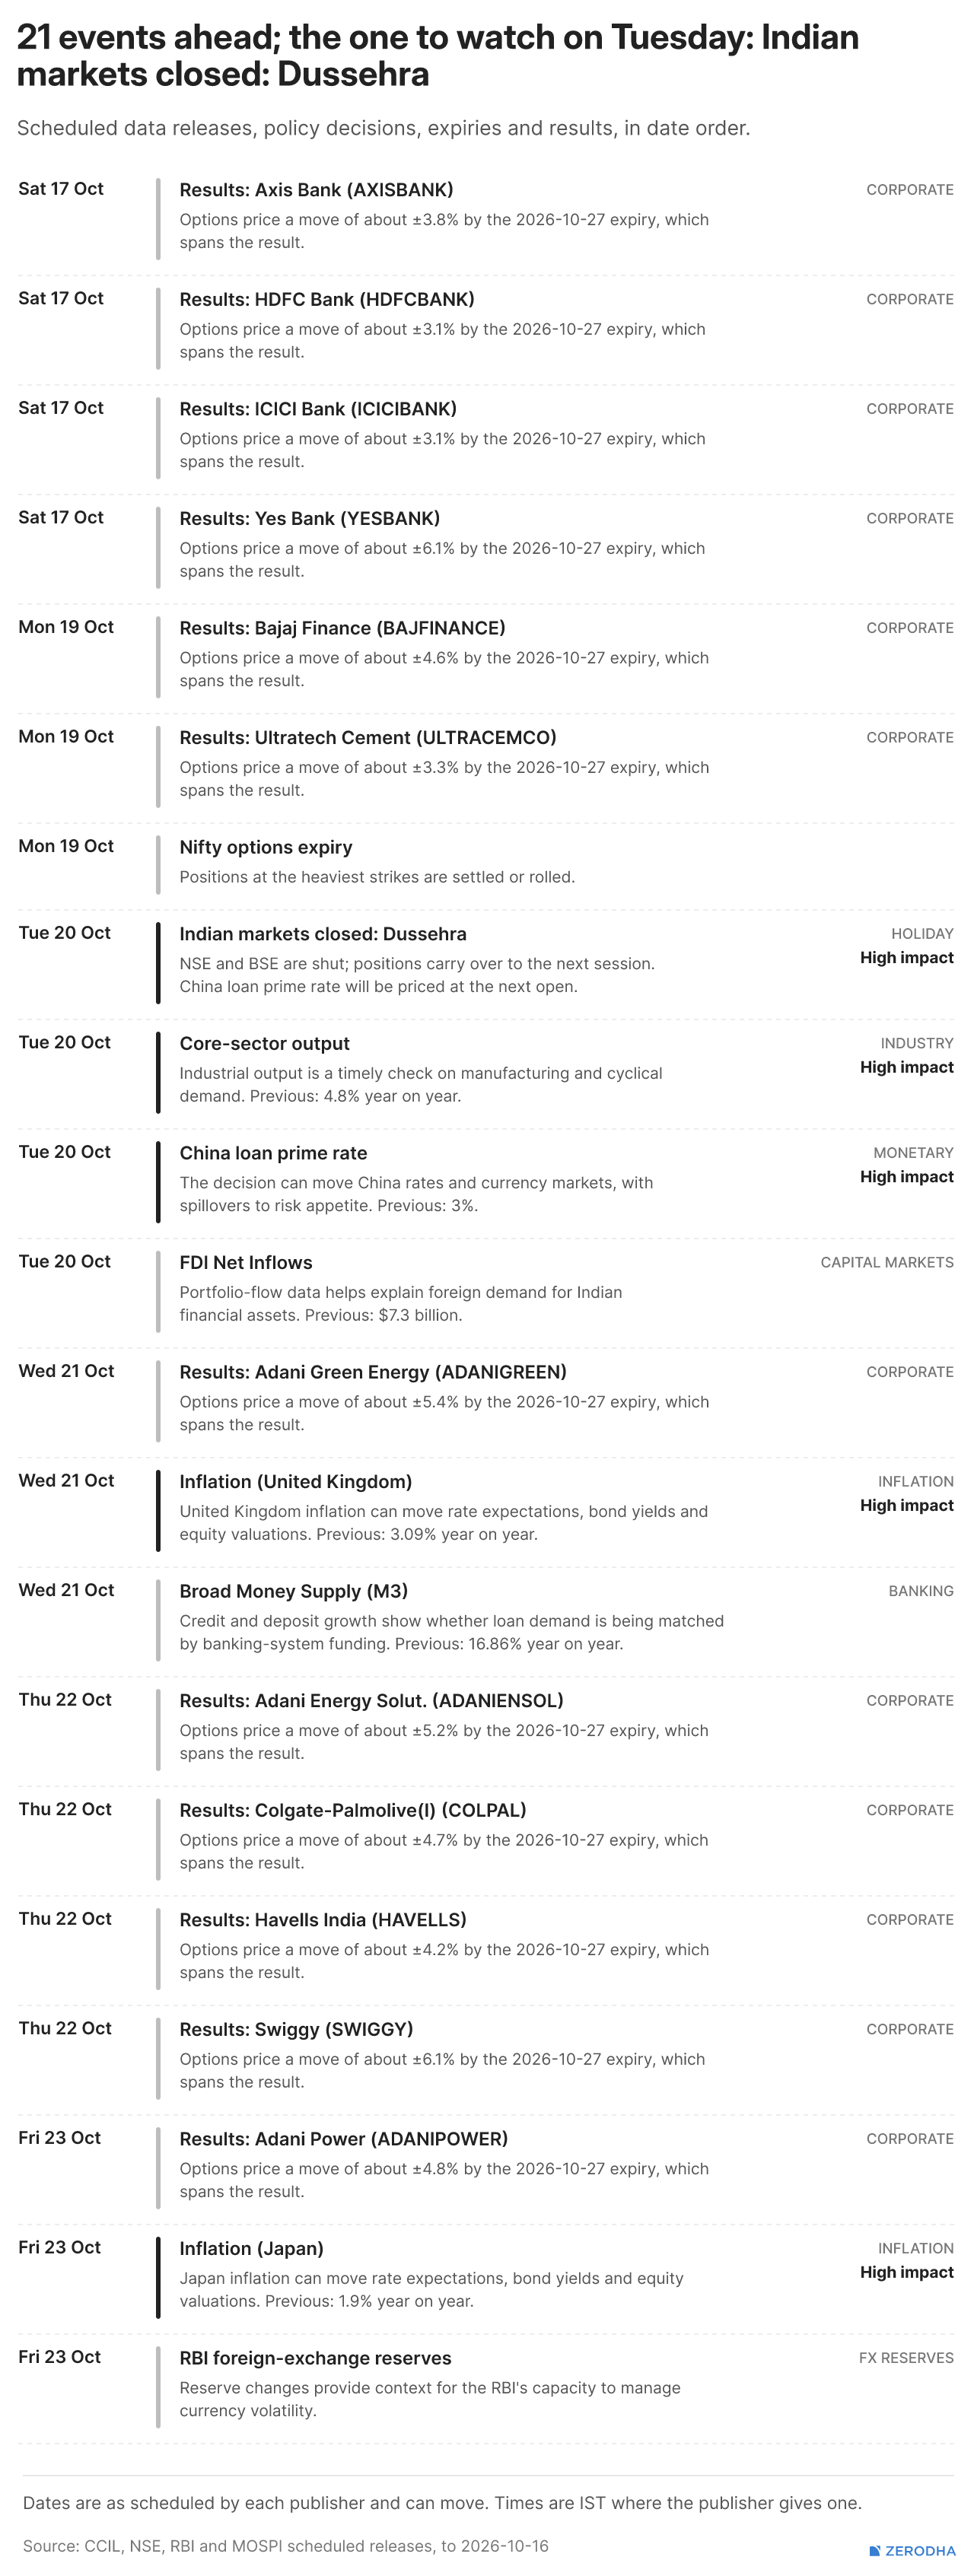
Week ahead
Check out Weekly market metrics
We’re in Week 42 of 2026. After weeks of market weakness, NIFTY staged a sharp recovery, gaining 2.78% to close at 23,146 and moving above the 23,100 resistance level. This week, we also look at SEBI’s decision to move expiry-day derivatives settlement back to the 30-minute VWAP method, continued FII selling despite strong domestic investor participation, and a record-breaking rally in IT stocks.
With NIFTY bouncing sharply from recent lows, the big question is whether we’ve finally seen a market bottom or if this is just another temporary recovery. We also look at the key levels, expiry risks, and major events that could shape the week ahead.
That’s it for this edition. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!