
Welcome to Aftermarket Report, a newsletter where we do a quick daily wrap-up of what happened in the markets, both in India and globally.
What data points and transformations do you want to see?
We’re trying out a new format for the Aftermarket Report, with much more comprehensive coverage of the data that shapes the trading day.
Beyond the headline indices, we’re now tracking market breadth, new highs and lows, sector and thematic performance, delivery data, F&O positioning, global markets, commodities, flows, and more. We’re also looking at ways to transform this raw data into insights that are actually useful for traders and investors.
The idea is simple: bring different datasets together in one place to give you a clearer picture of what’s happening beneath the surface of the market.
This is still a work in progress, and we’d love your feedback. What data points are we missing? What transformations, ratios, comparisons, or indicators would you find useful? Also tell us what worked, what didn’t, and what felt unnecessary.
Your feedback will help shape the Aftermarket Report from here.
Markets Today
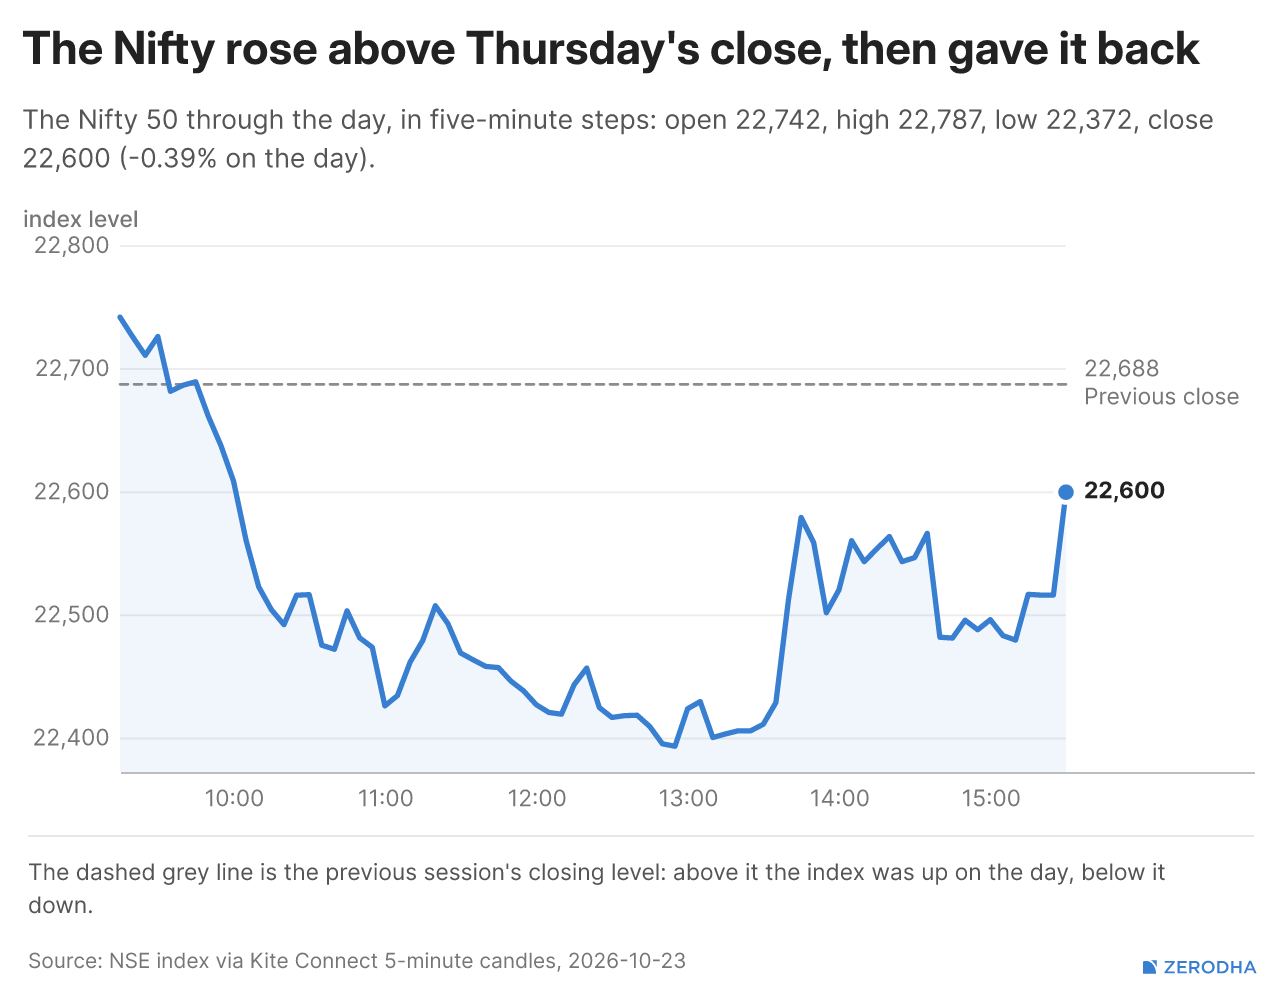
Nifty opened with a 54-point gap up at 22,742, tracking a cooldown in US bond yields, but immediately came under selling pressure as oil prices continued to surge, surpassing their May highs. The index initially hovered near 22,750 before selling intensified, dragging Nifty below 22,700 within the first 20 minutes and towards 22,600 by 10 AM.
The decline continued through the opening hour, with Nifty slipping below 22,500 around 10:15 AM. A brief recovery attempt pushed the index back towards 22,530, but buying momentum remained weak. Selling resumed shortly after, dragging Nifty towards 22,430 around 11 AM. Another recovery attempt lifted the index towards 22,510 by 11:20 AM, but the gains quickly faded, with Nifty drifting lower towards 22,420 by noon.
The second half remained under pressure initially, with Nifty extending its decline towards an intraday low near 22,370 around 12:45 PM. However, buying interest gradually emerged from the lows, helping the index recover towards 22,430 by 1 PM. The recovery gathered momentum after 1:30 PM, with a sharp rebound pushing Nifty above 22,500 and towards 22,590 around 1:40 PM.
However, the rally struggled to sustain at higher levels, with Nifty oscillating between 22,500 and 22,570 through much of the afternoon. Another round of selling around 2:30 PM dragged the index back below 22,500, but buying returned in the final minutes, helping Nifty recover sharply towards 22,600. The index eventually closed at 22,600, around 140 points below its opening level, as the late recovery helped pare a significant portion of the day’s losses, although elevated oil prices and weak domestic sentiment continued to weigh on markets.
Fear & Greed Index
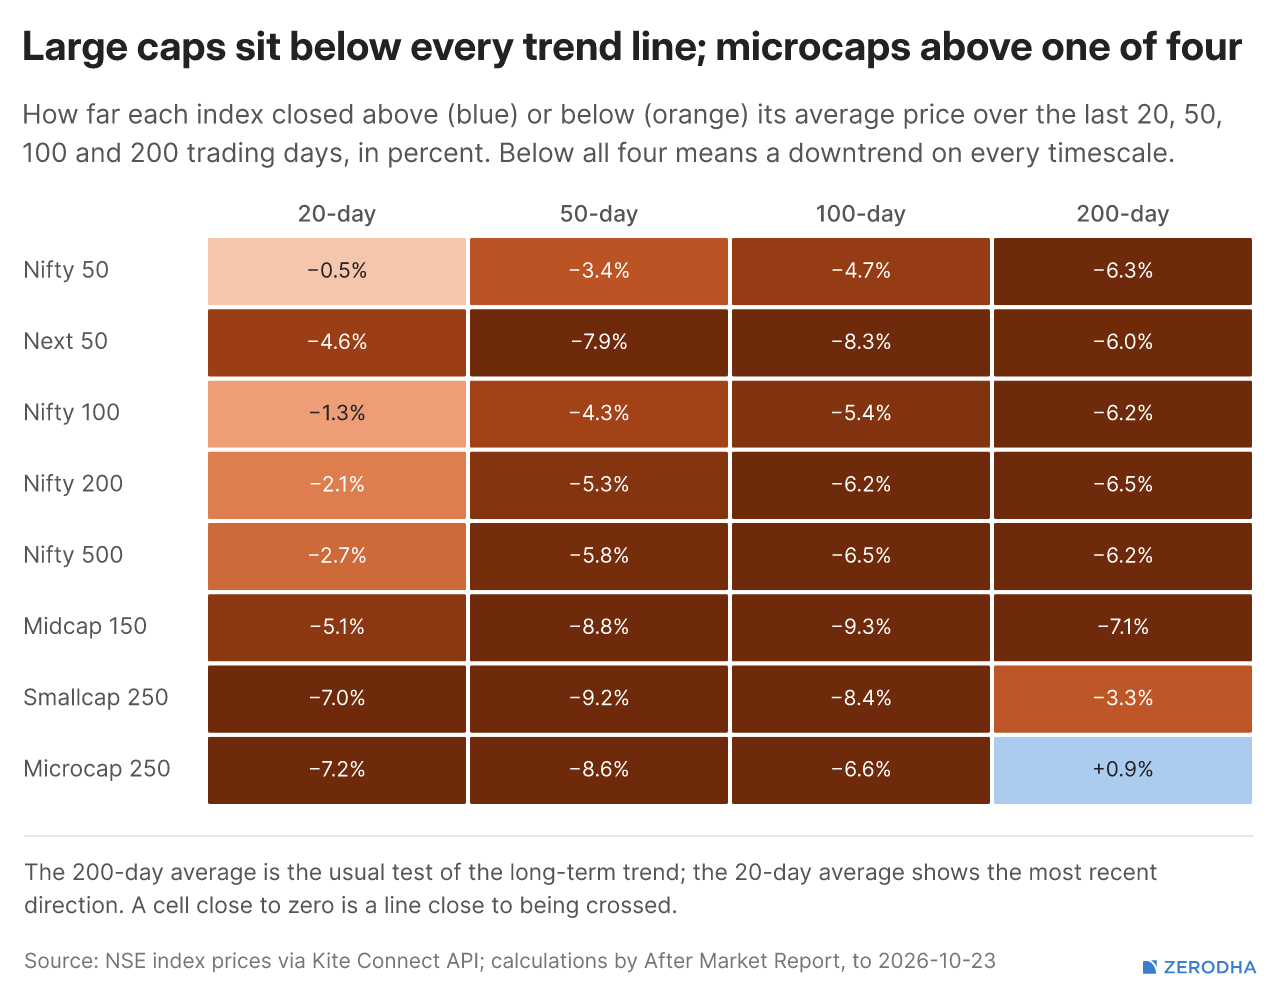
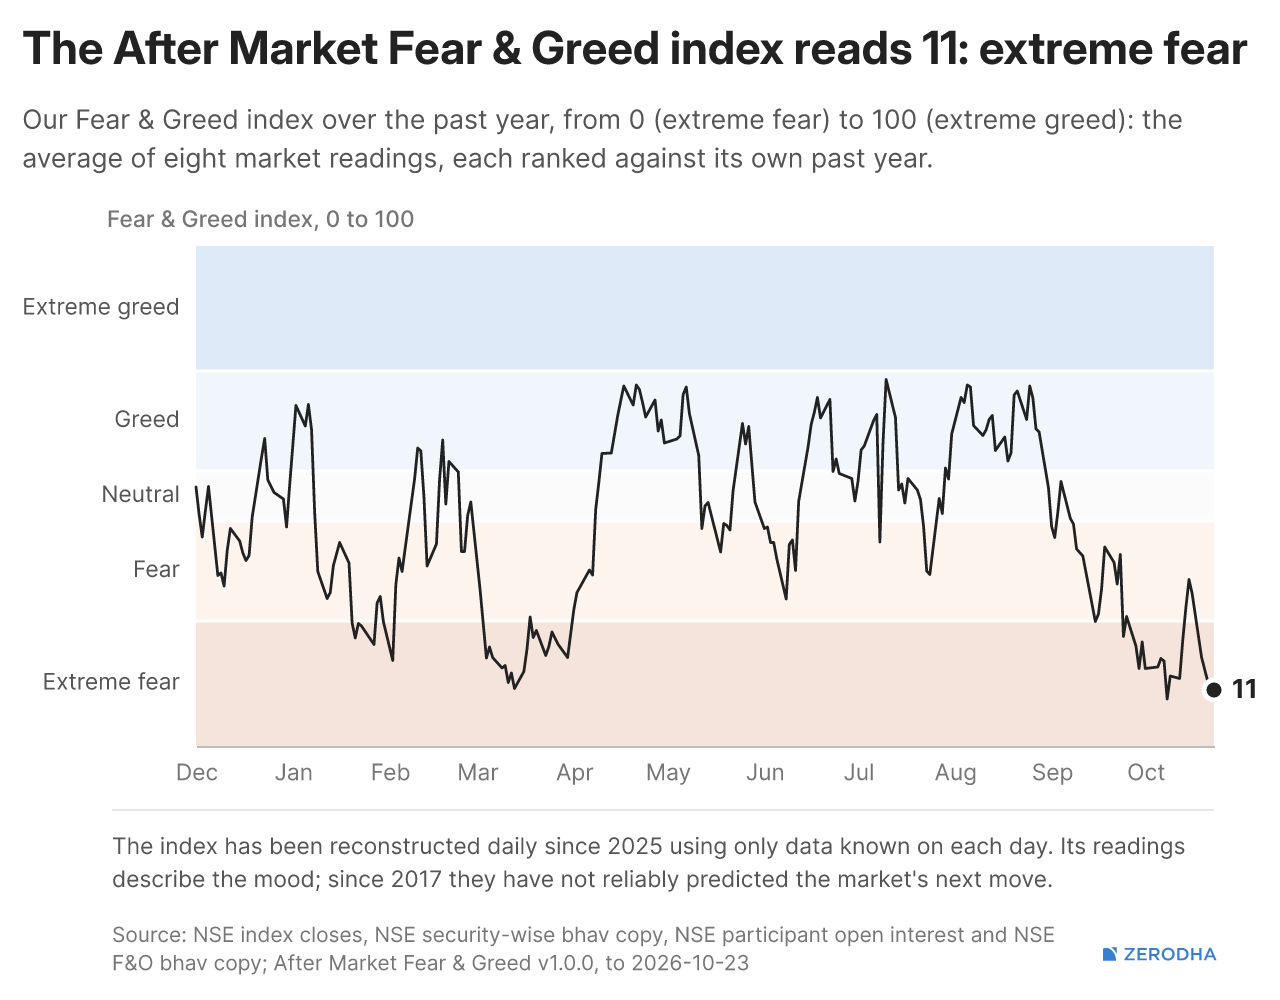
The Fear & Greed Index slipped from 13 to 11, remaining firmly in extreme fear, compared with 33 a week ago. Weak market trends, rising volatility and defensive stocks outperforming high-beta stocks continue to reflect deteriorating sentiment.
Market Breadth
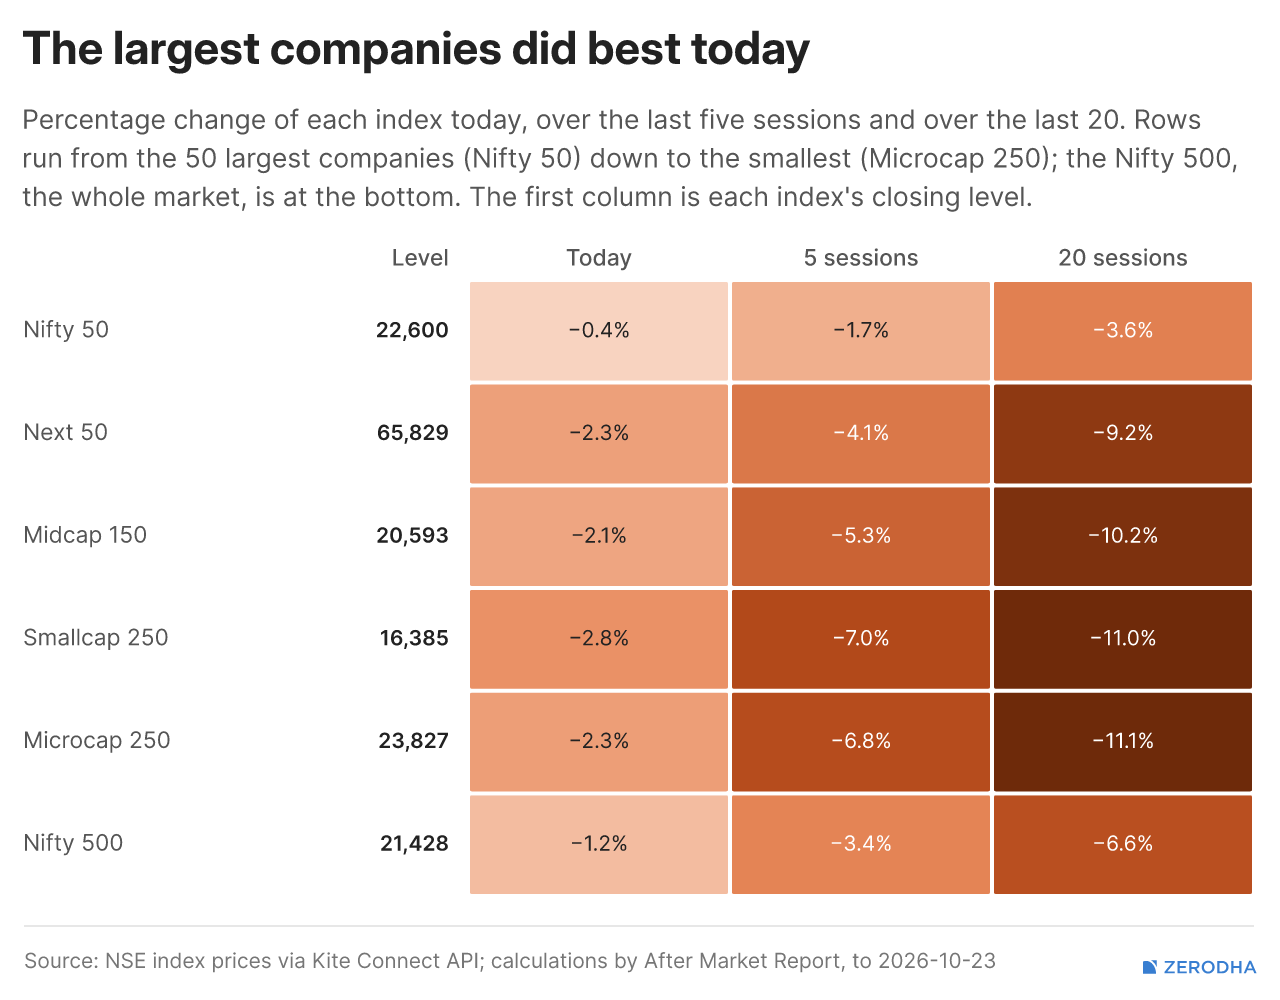
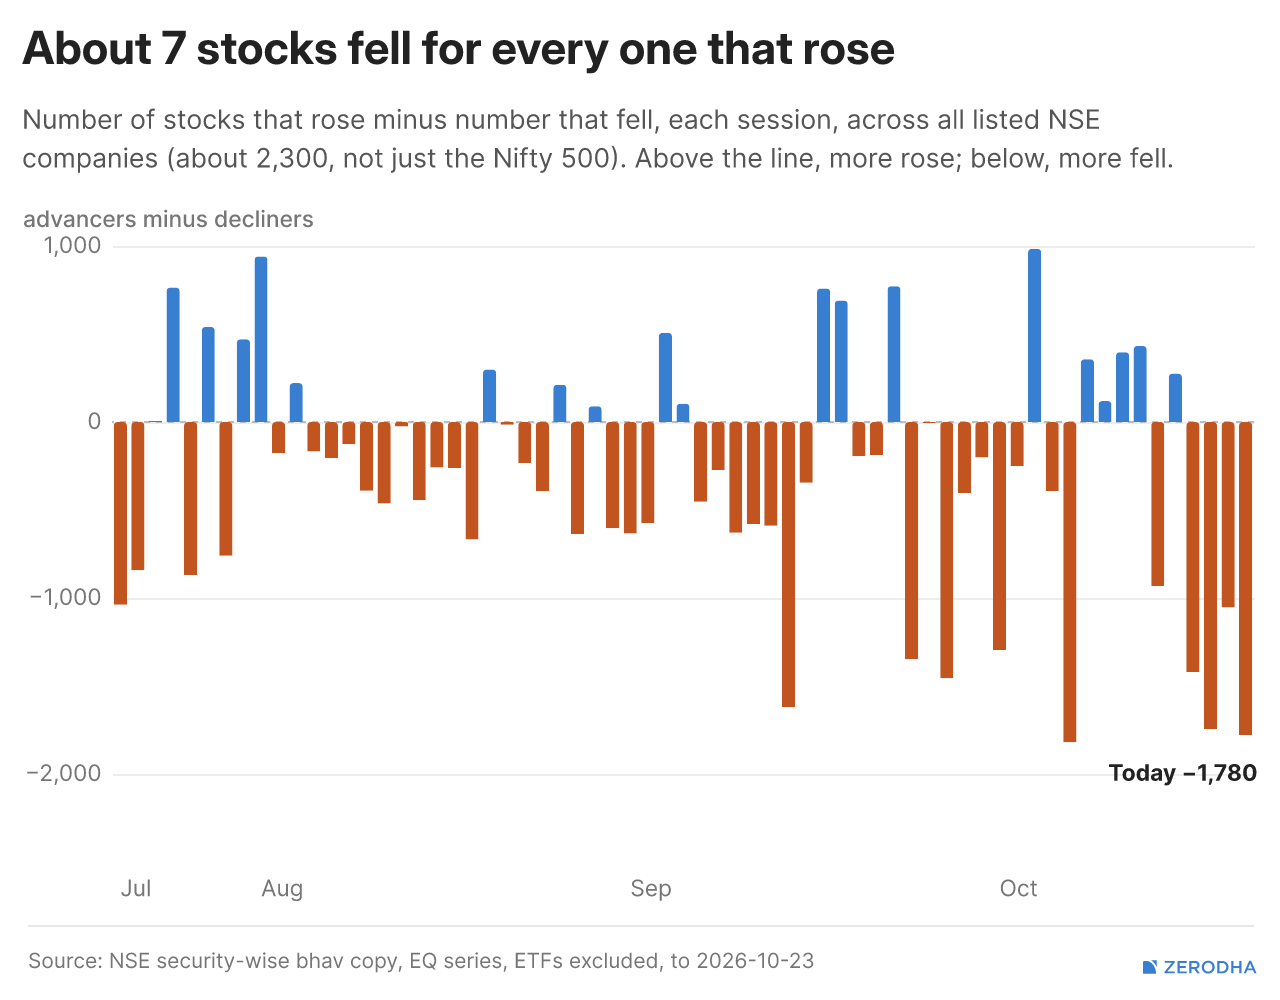
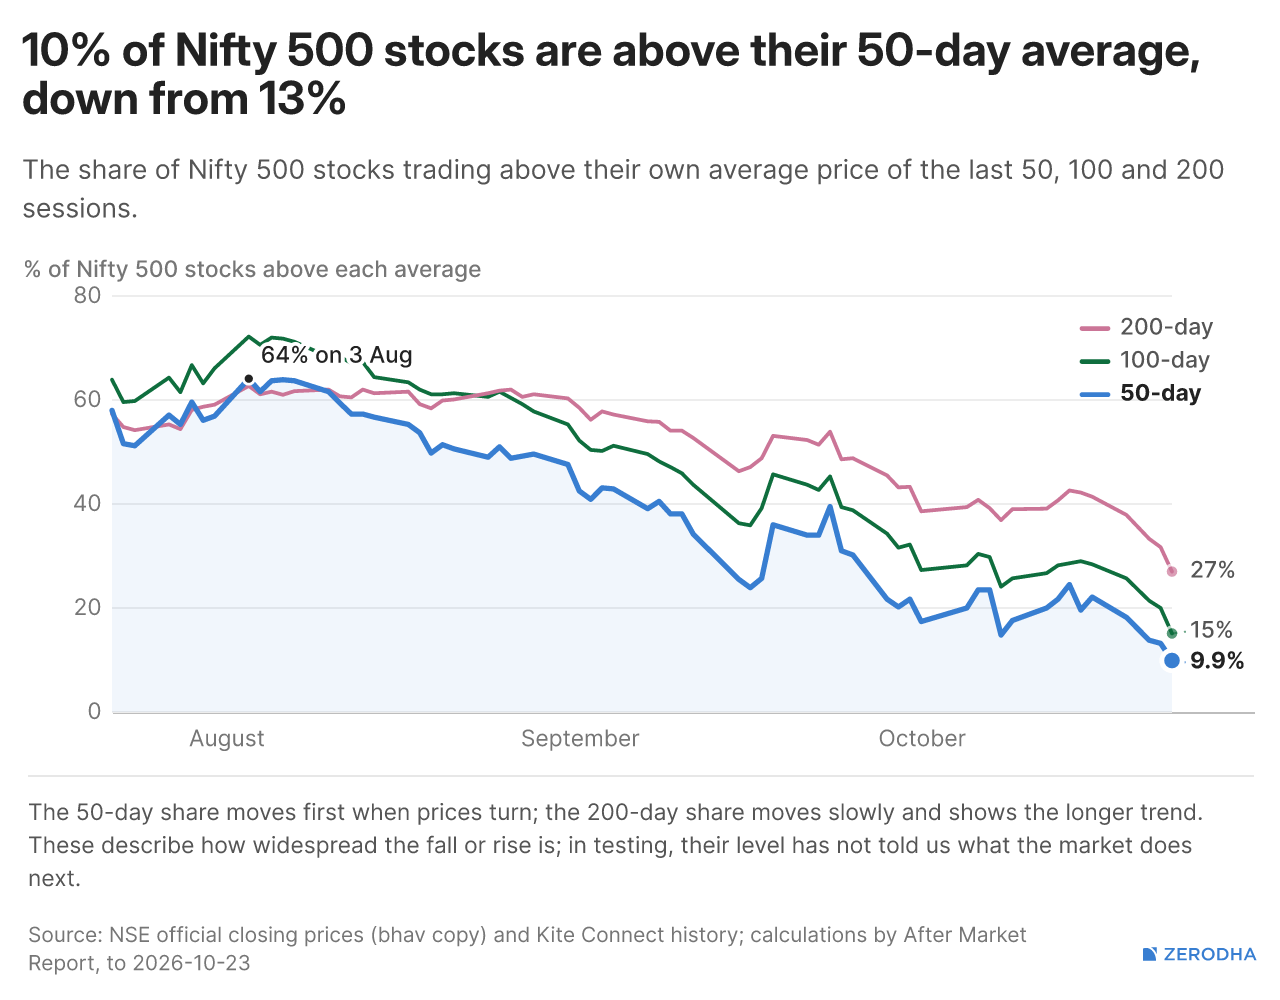
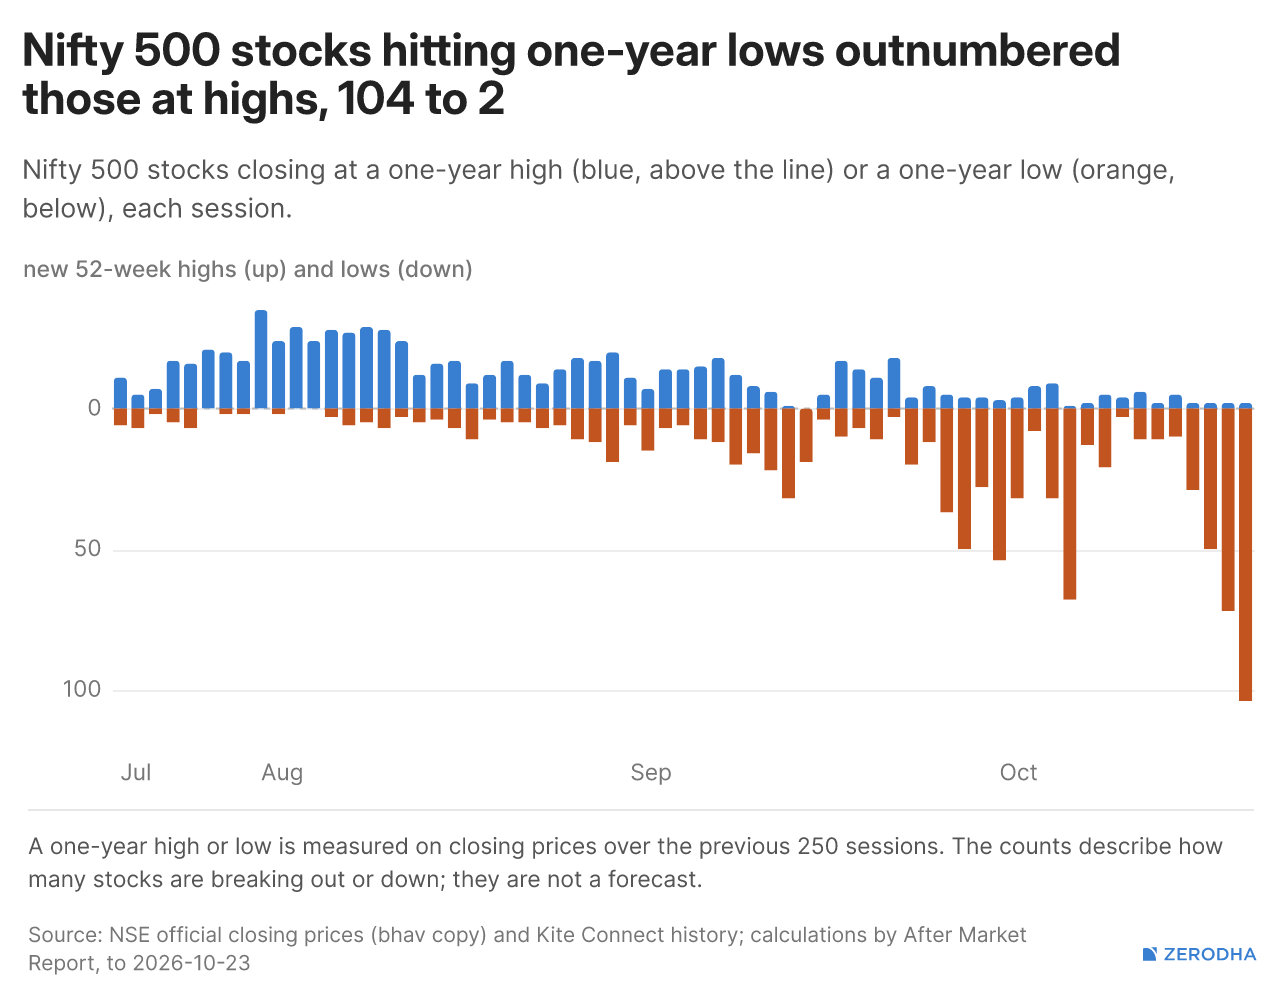
Market breadth was sharply negative, with 2,058 declining stocks against just 278 advancing, or more than seven losers for every gainer. Only 9.9% of Nifty 500 stocks remain above their 50-day average, while 104 stocks hit fresh 52-week lows against just two new highs.
52 Week Highs & Lows
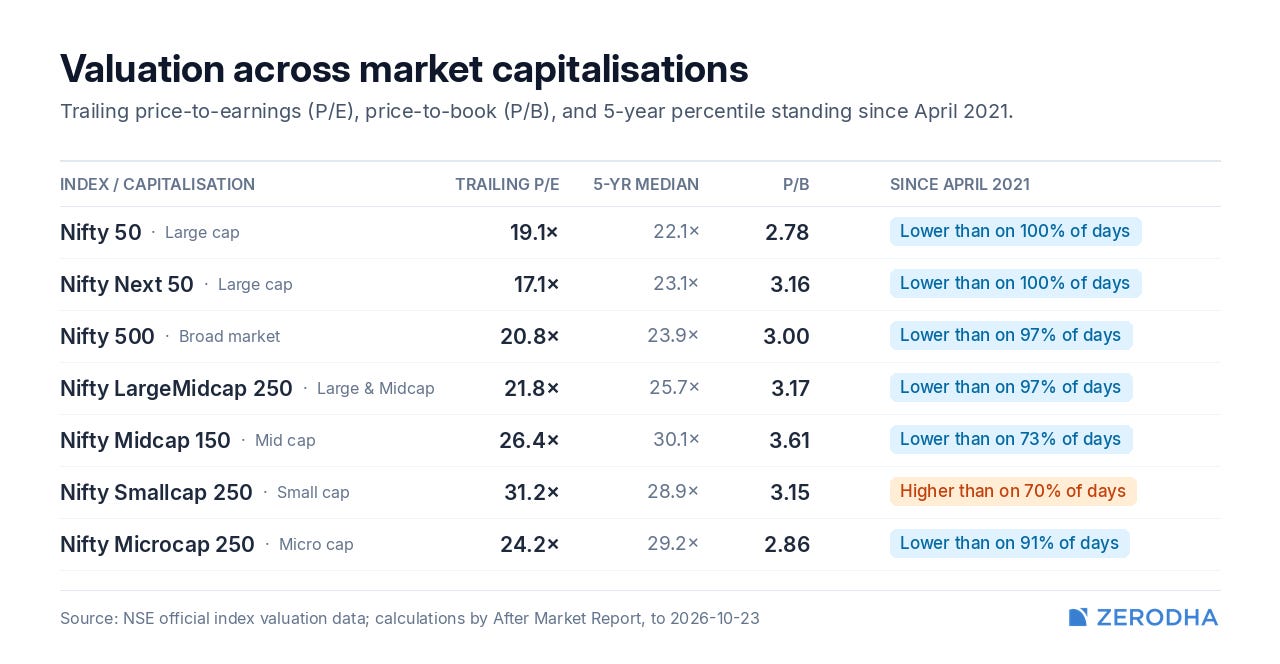
Valuation Check
Sectoral Indices Performance
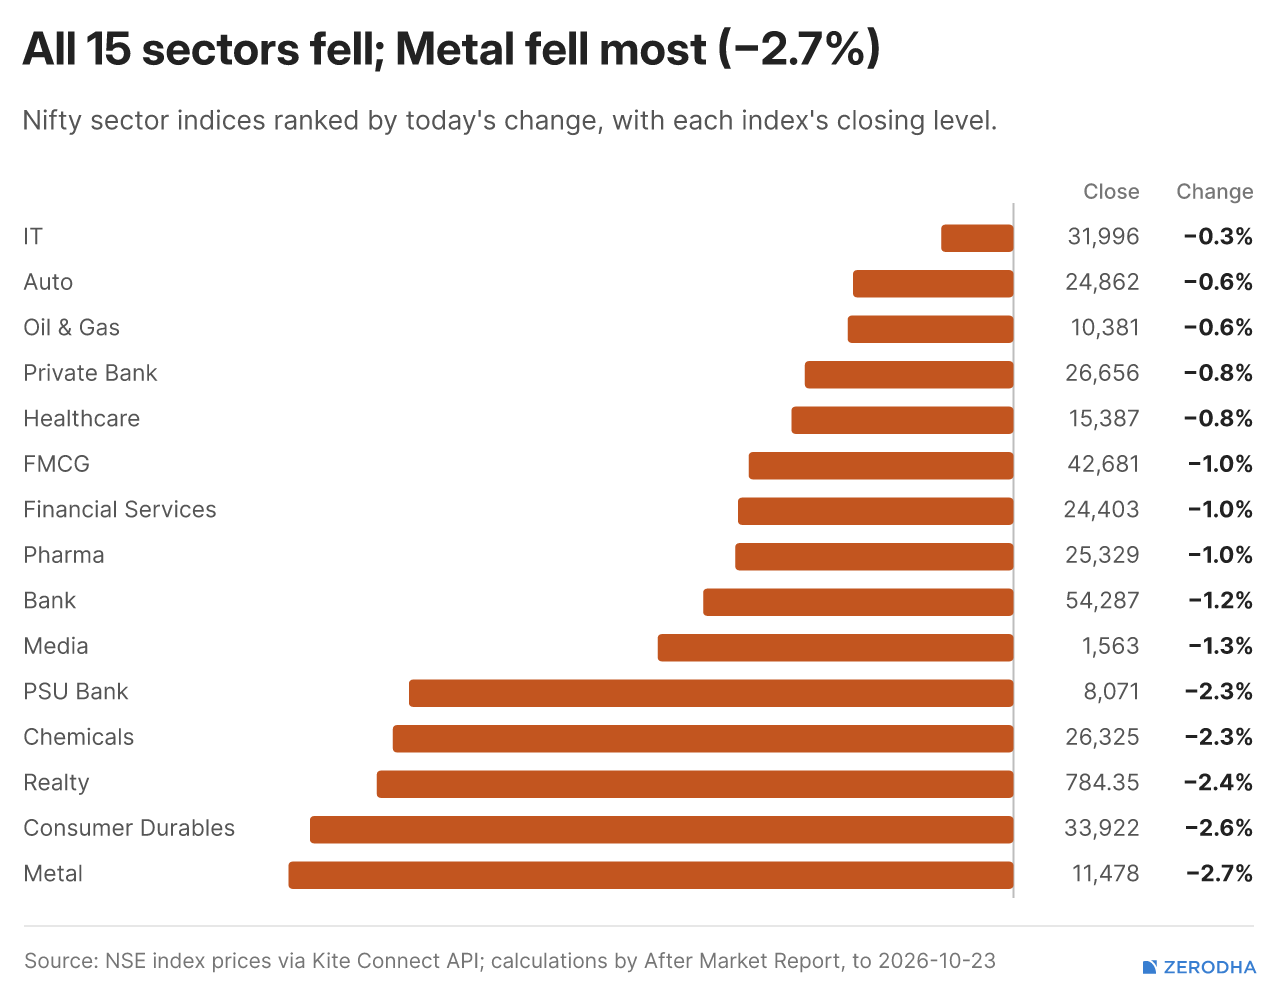
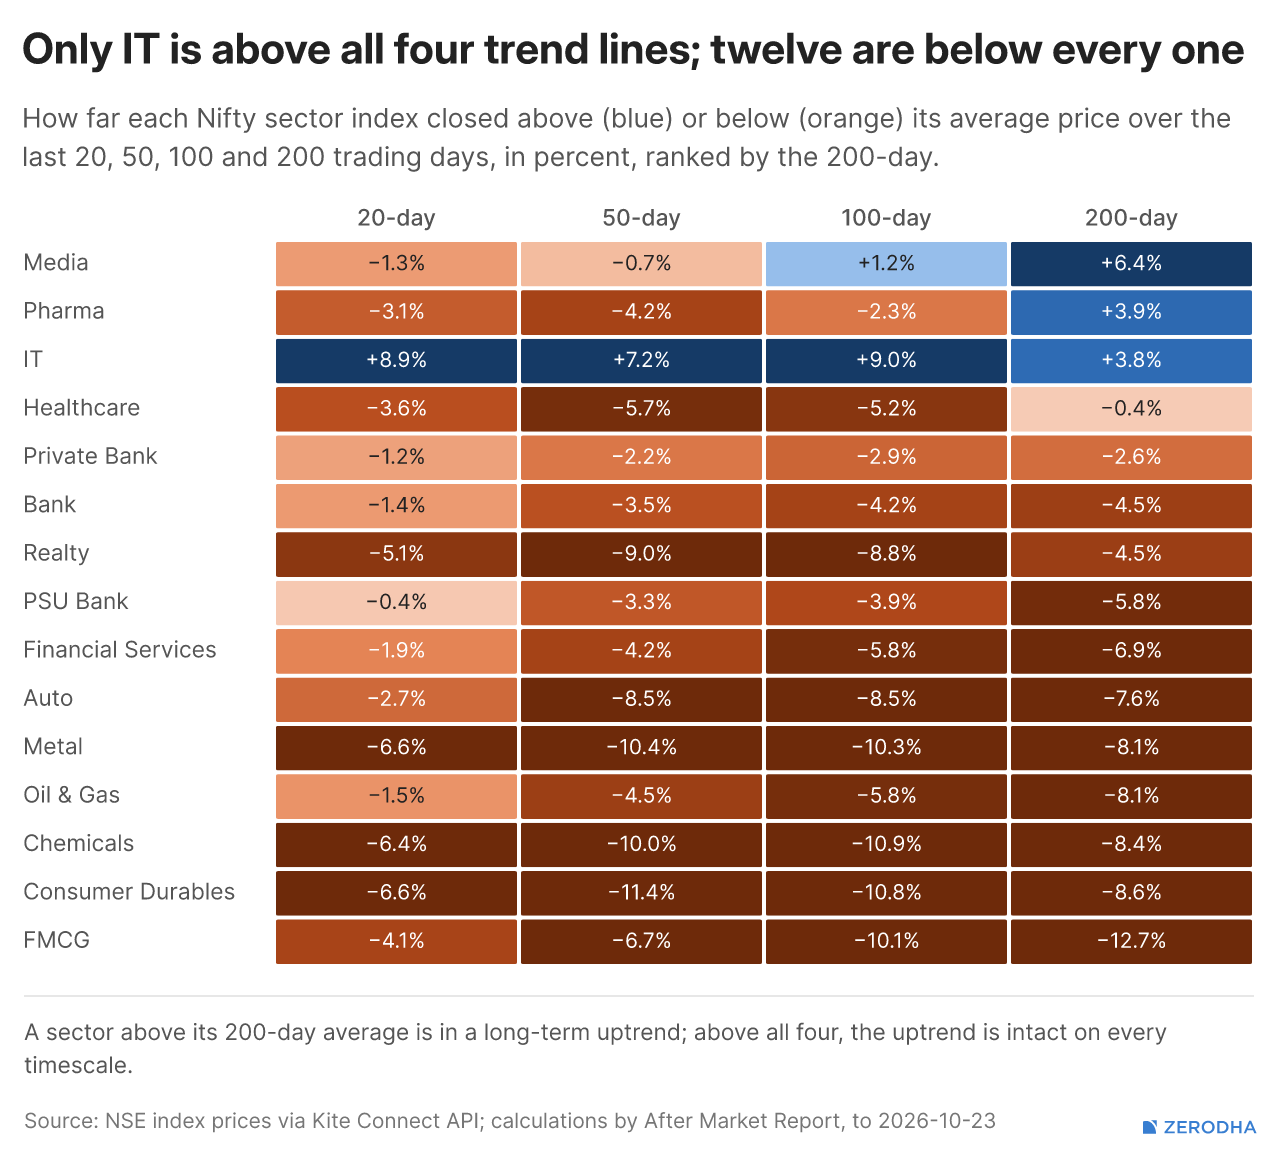
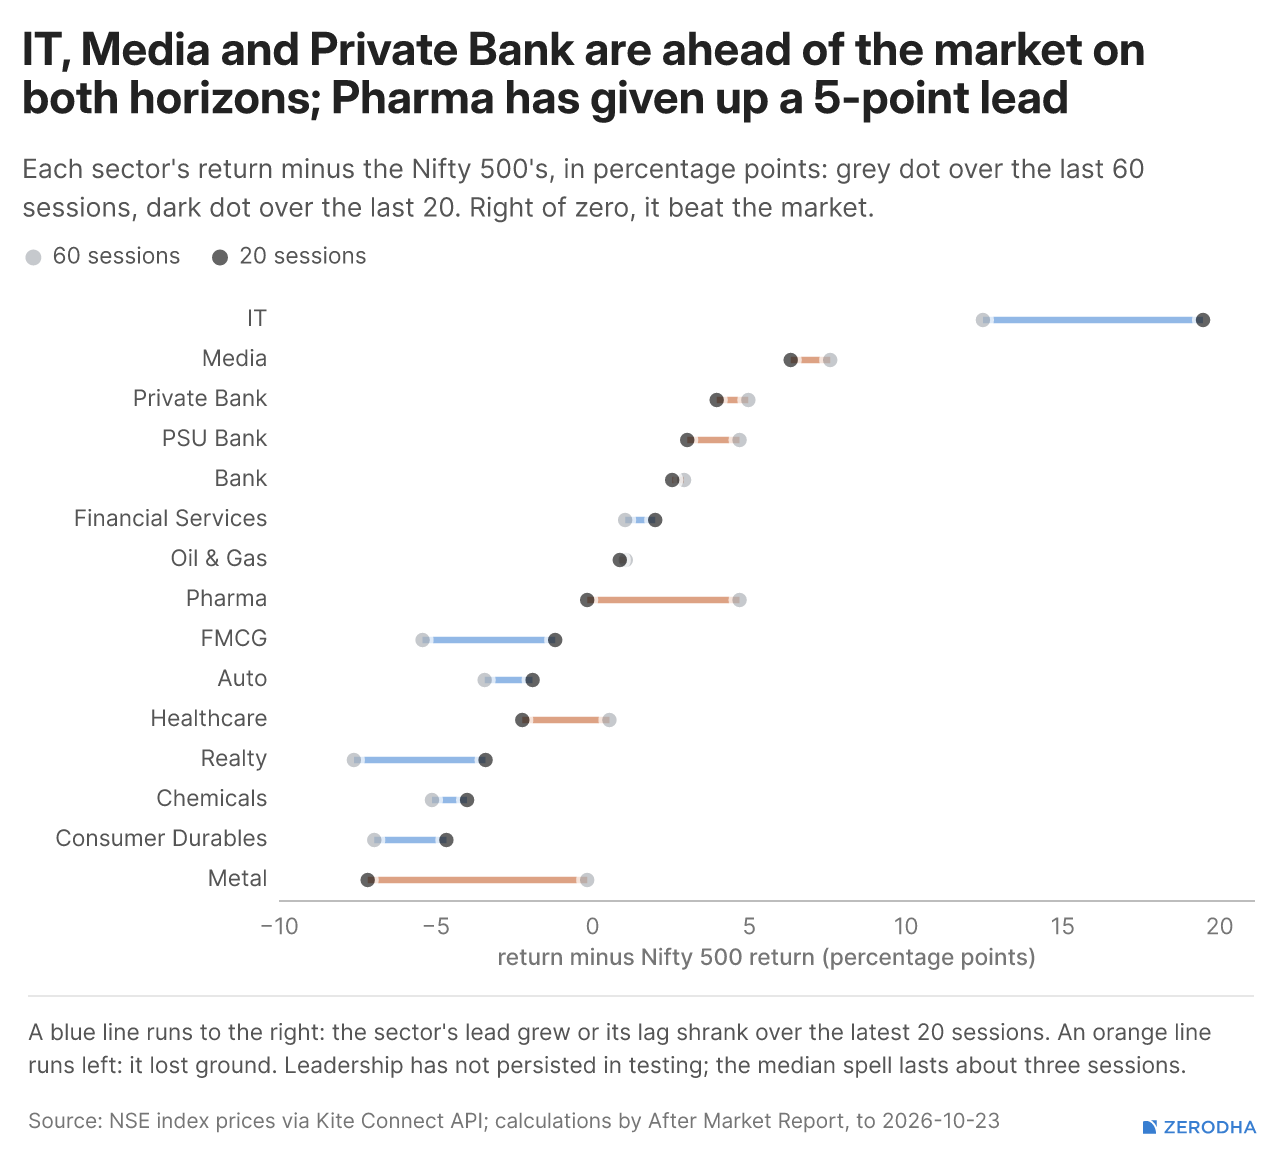
All 15 sectors ended in the red, with IT declining the least at 0.27%, while Metals fell 2.71%. IT, Media and Private Banks remain the relative leaders over 20 and 60 sessions, although IT is the only sector trading above all four key moving averages.
Winners & Losers
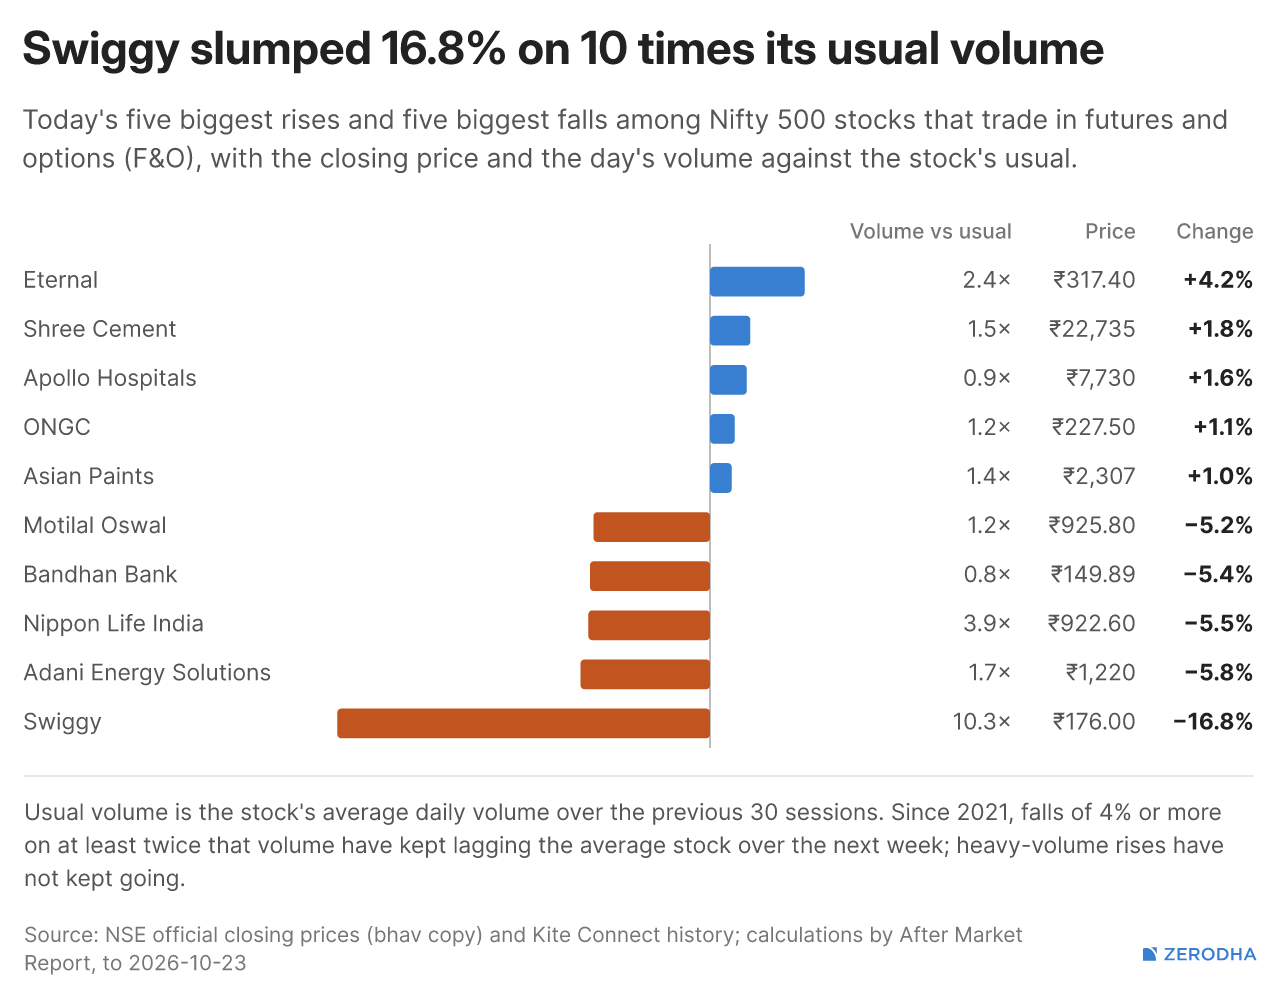
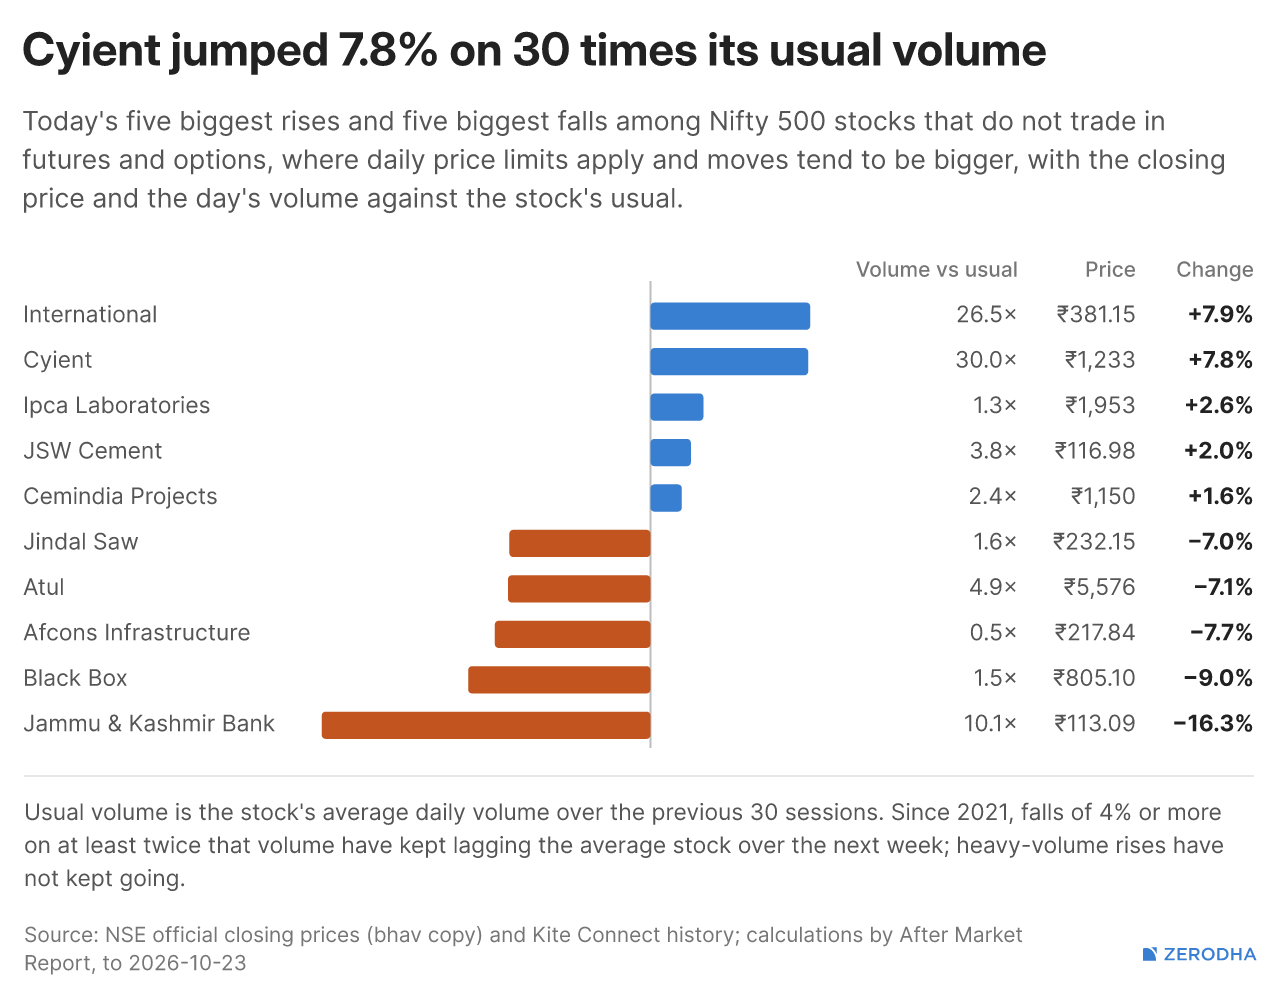
International Gemological jumped 7.91% on 26× usual volume, while Cyient gained 7.81% on 30× volume, with both hitting fresh 52-week highs. Meanwhile, Swiggy plunged 16.75%, and Jammu & Kashmir Bank fell 16.28% on heavy trading volumes.
Delivery Data
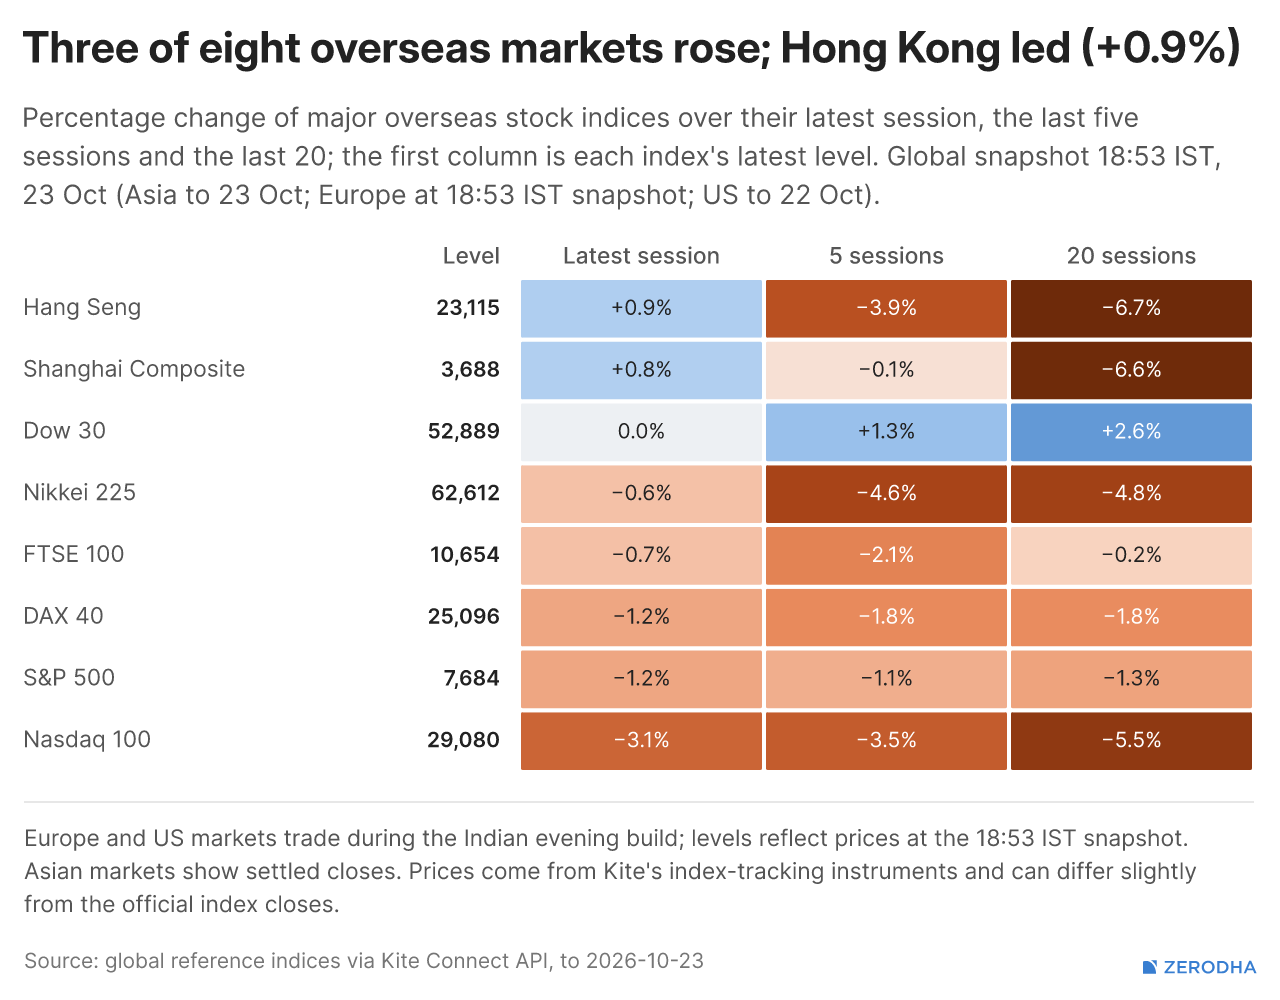
Global Markets
Commodities
Institutional Flows & Participant Positioning
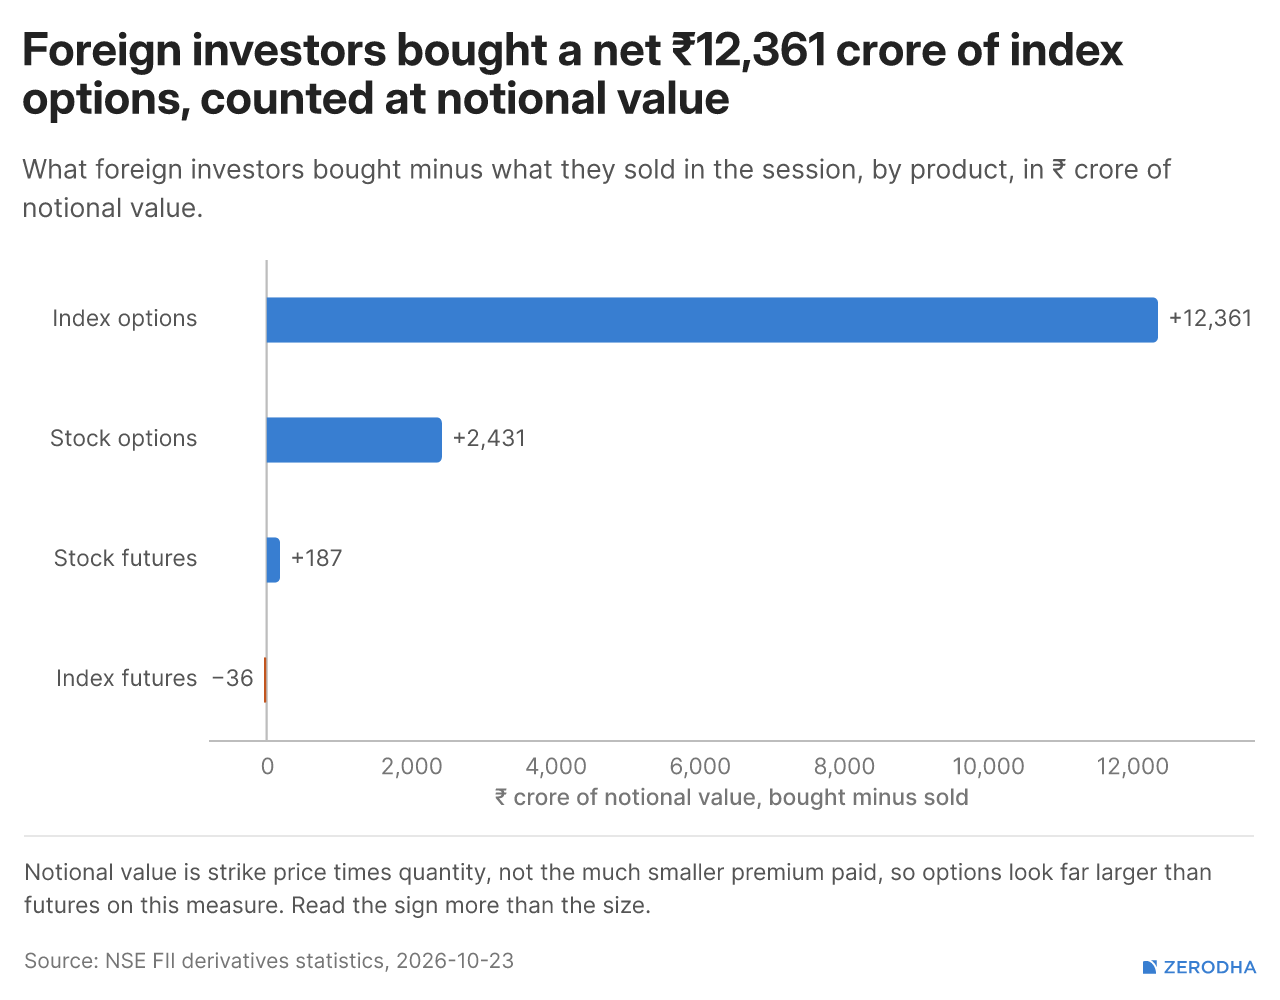
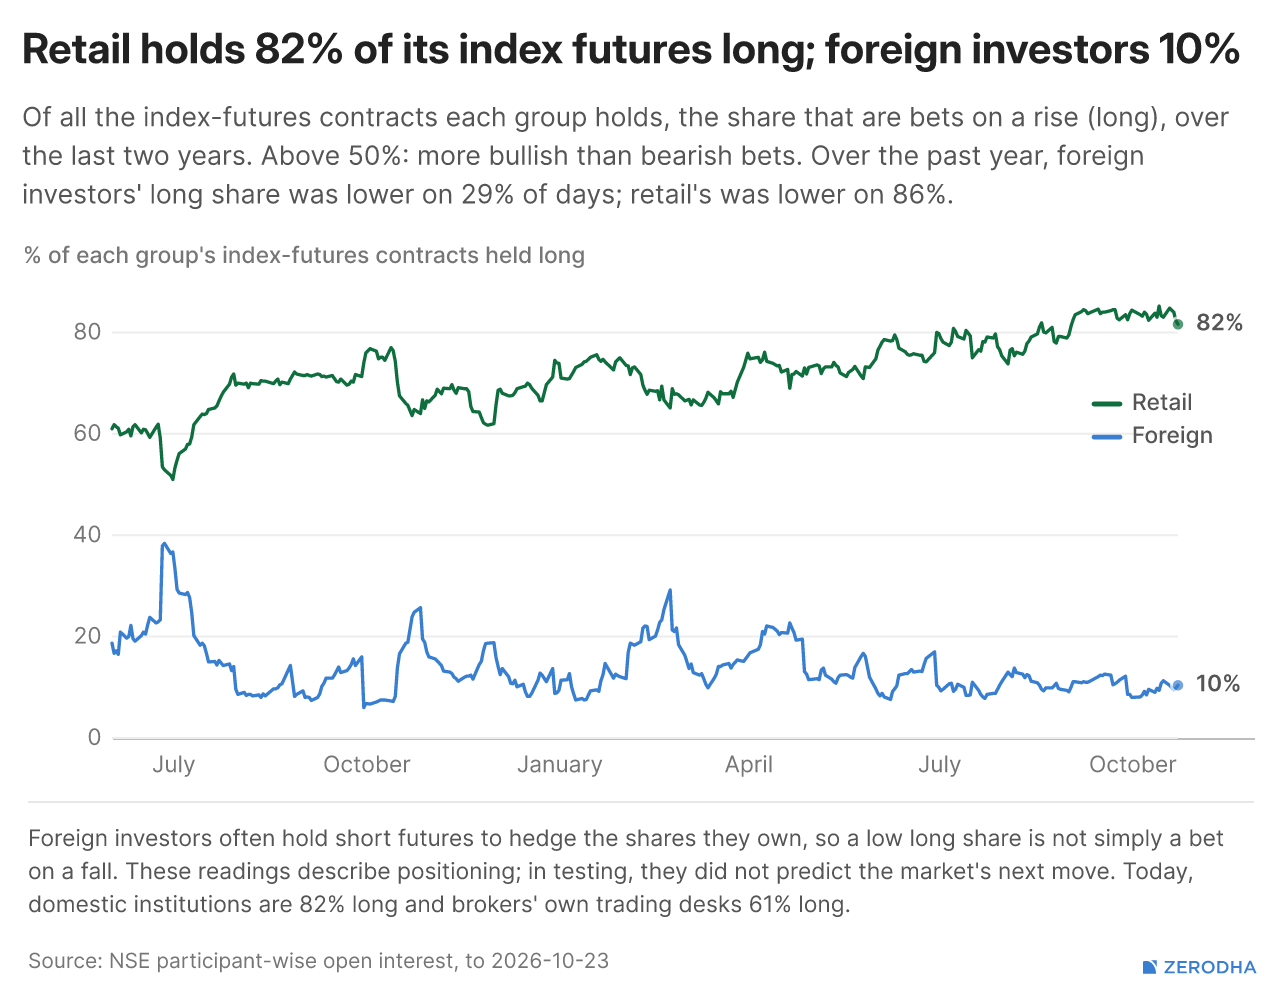
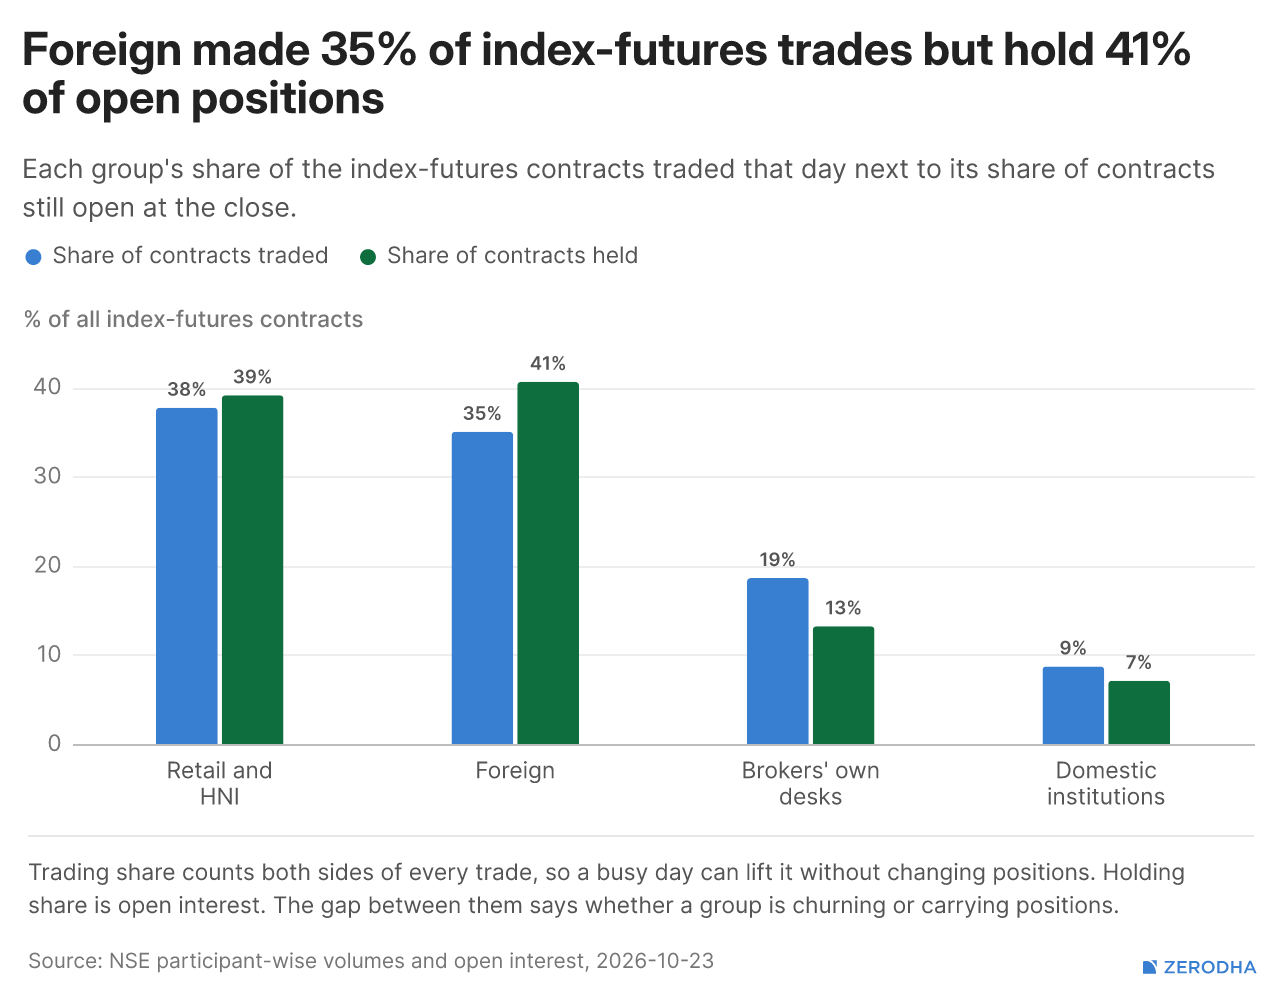
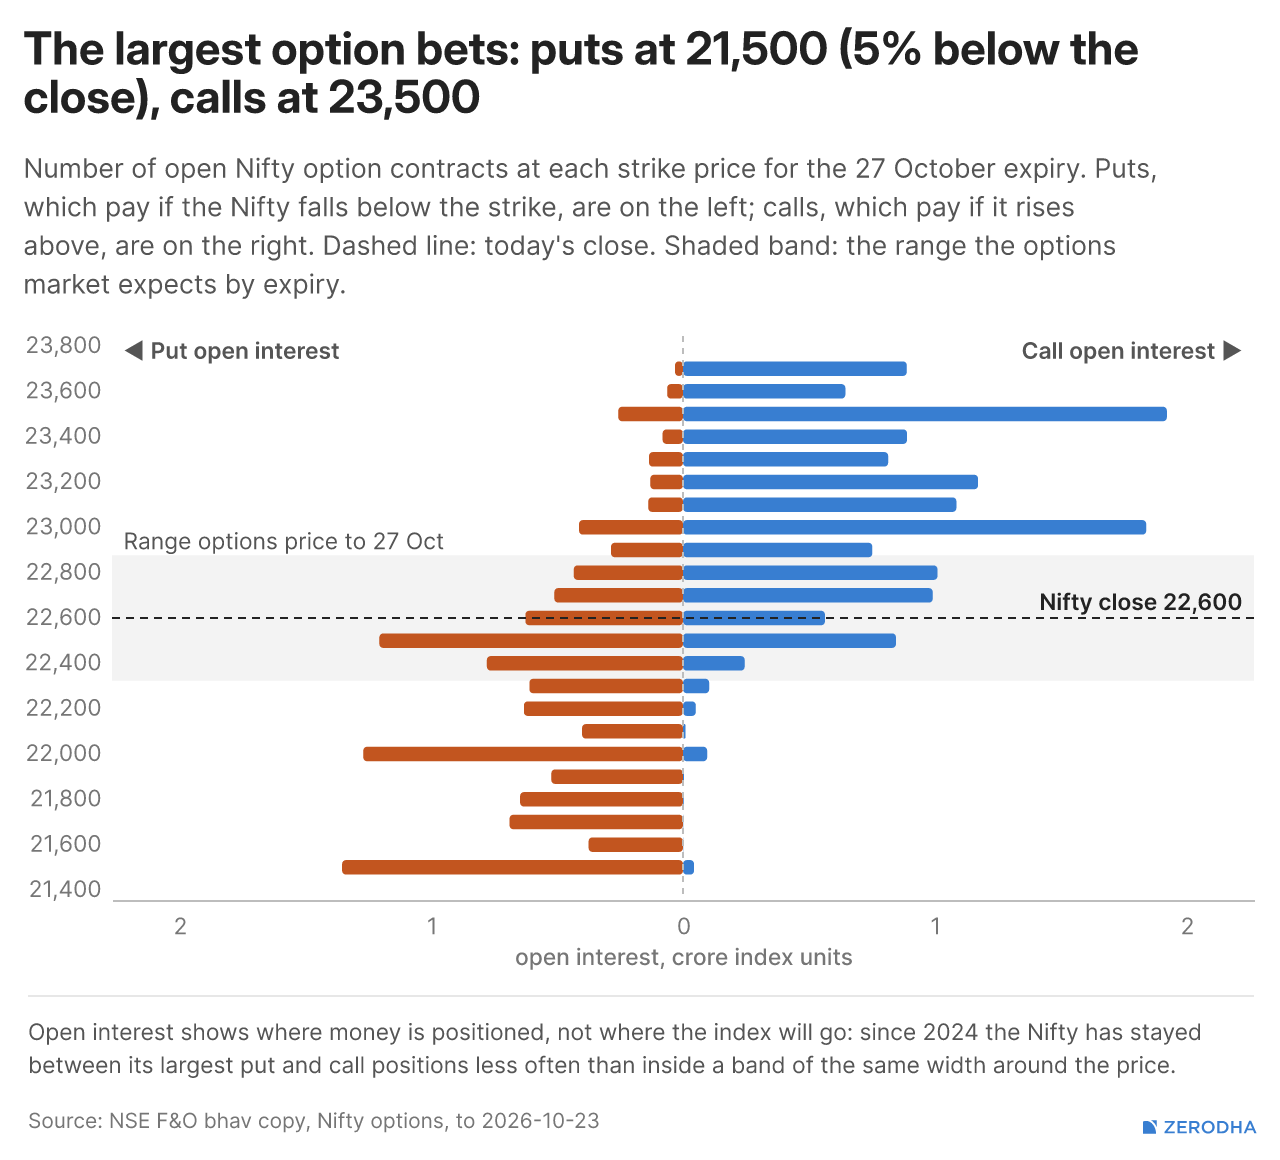
Call writing strengthened, pulling the PCR down from 0.88 to 0.81, while implied volatility rose from 14.2% to 14.7%. FIIs remain heavily bearish with just 10.4% of index-futures positions long, compared with 82% for retail and HNIs.
Options imply a 22,292–22,846 range into October 27 expiry, with the heaviest put OI at 21,500 and call OI at 24,000. The 20-day moving average at 22,714 remains the first major hurdle for Nifty, which closed at 22,600.
Thematic Indices
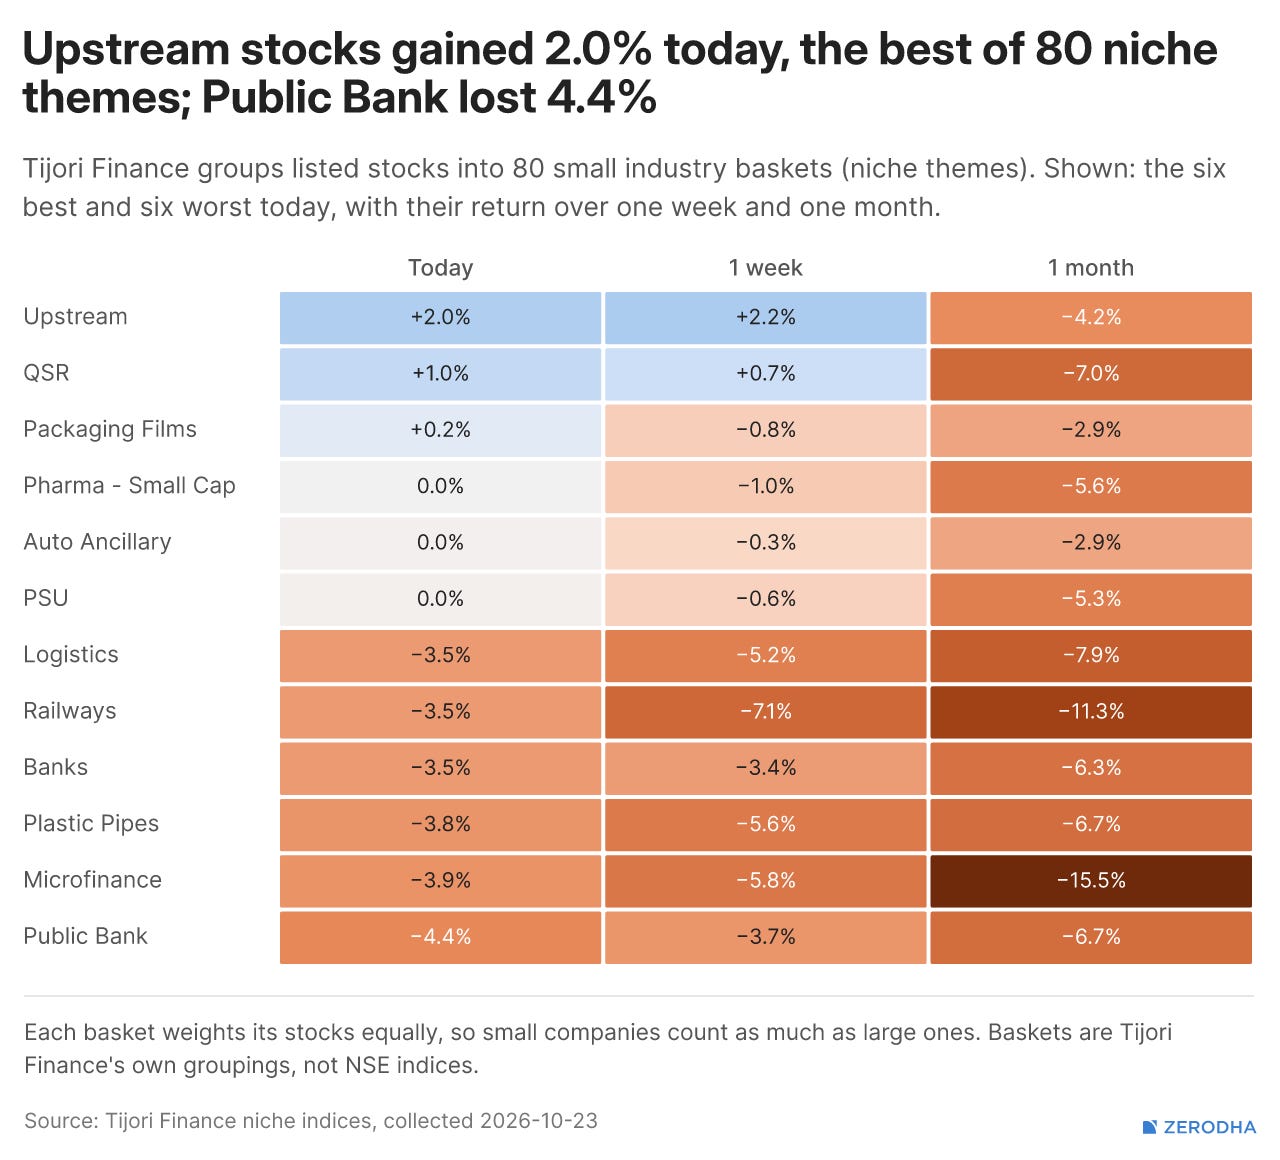
Tijori’s niche indices, where today’s move sorts pockets of the market beyond standard sector baskets. You can also track promoter buying and other interesting stuff, like Capex activity by the companies in the Tijori App’s idea dashboard
F&O Corner

Top Stories in India
Infosys lowered its FY27 revenue growth guidance to 1–2% from 1.5–3%, citing global uncertainty and weak discretionary spending. Q2 net profit rose 6.2% YoY to ₹7,823 crore, while revenue grew 10.7% to ₹49,244 crore, supported by life sciences and energy-related businesses. Dive deeper
Jio Platforms’ IPO received over 1 crore applications with hours of bidding still remaining, setting a reported global record for the highest number of IPO applications. It surpassed the previous record of approximately 97 lakh applications held by Waaree Energies. Dive deeper
Adani Power reported a 142% YoY surge in consolidated net profit to ₹7,019 crore, supported by higher revenue and one-time income. Revenue increased 29.8% to ₹17,014 crore, driven by stronger electricity demand, higher power purchase agreement tariffs and improved merchant realisations. Dive deeper
Tata Motors’ commercial vehicle business reported a consolidated net profit of ₹1,254 crore in Q2 FY27, compared with a loss of ₹867 crore a year earlier. Revenue grew 36% YoY to ₹25,338 crore on higher vehicle volumes, while EBITDA rose 31% to around ₹2,800 crore. Dive deeper
JSW Steel reported a more than threefold YoY jump in consolidated net profit to ₹5,359 crore, while total income rose to ₹54,927 crore. Steel sales reached a record 7.46 million tonnes, up 13% YoY, supported by strong domestic demand and higher sales of value-added products. Dive deeper
Chinese energy storage company Sigenergy plans to invest an initial $250 million to establish inverter and battery energy storage manufacturing facilities in India. Its inverter plant is expected to begin operations by Q2 2027, followed by a battery storage facility within six to eight months. Dive deeper
India’s Business Confidence Index rose to 107.8 in Q2 FY27 from 99.8 in the previous quarter, ending four consecutive quarters of moderation, according to NCAER. However, sentiment remained below the 142.6 recorded in the corresponding quarter last year, reflecting continued global uncertainty. Dive deeper
India’s foreign exchange reserves fell by $5 billion to $721.02 billion in the week ended October 16, following an $8.58 billion decline in the previous week. Reserves have been falling since reaching a record $785.71 billion in early September, which was supported by substantial inflows through a special diaspora deposit swap scheme. Dive deeper
Top Stories Globally
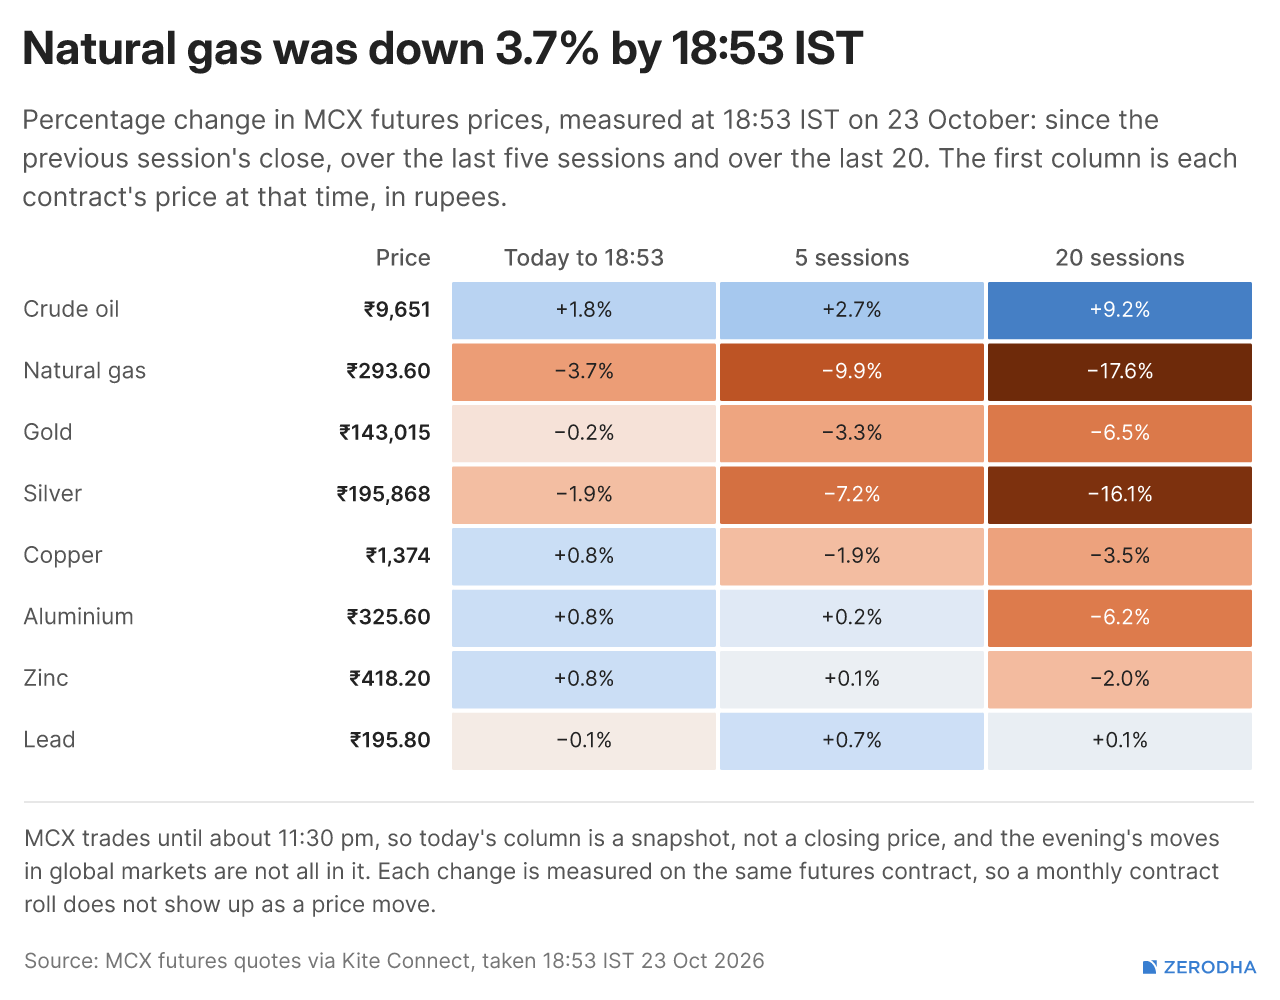
Brent crude climbed to $115 per barrel, its highest level since May 4, following Houthi attacks in Saudi Arabia that raised concerns over Middle Eastern energy supplies. Brent futures gained 1.2% to $114.57, while US WTI crude rose 1.5% to $100.95 per barrel. Dive deeper
The US 10-year Treasury yield climbed to 5% on Friday, recovering after a 17-basis-point decline in the previous session, its largest single-day fall in over a year. Rising oil prices, escalating Middle East tensions and uncertainty ahead of the US midterm elections continued to weigh on investor sentiment. Dive deeper
Chinese AI developers DeepSeek and MiniMax have reportedly received government approval for the global use of their artificial intelligence models. The development marks a step towards expanding the international presence of Chinese AI technologies. Dive deeper
Tesla shares declined 2% after the company reduced its 2026 capital expenditure forecast to approximately $20 billion from over $25 billion. Lower-than-expected spending on AI and robotics helped generate positive free cash flow in Q3 but raised investor concerns about the pace of Elon Musk’s AI and robotics ambitions. Dive deeper
Management Chatter
In this section, we highlight interesting comments from management at major companies and from policymakers in the Indian and Global Economies.
Puneet Chhatwal, MD and CEO of Indian Hotels on massive shortage of branded hotel rooms in India:
“The Indian hospitality sector is insulated primarily because domestic demand continues to outpace available supply. India currently has roughly 200,000 branded hotel rooms, with the industry on track to add another 200,000 rooms over the next few years to reach 400,000. However, the country requires approximately one million branded hotel rooms to support its long-term economic expansion. That structural undersupply provides a durable buffer against external global volatility. Furthermore, domestic tourism has expanded at an 11% CAGR over the last decade. While foreign tourist arrivals currently grow at sub-4%, hosting the World Travel and Tourism Council Global Summit in India next year will serve as an international catalyst to accelerate foreign inbound travel over the next twelve months.” - Link
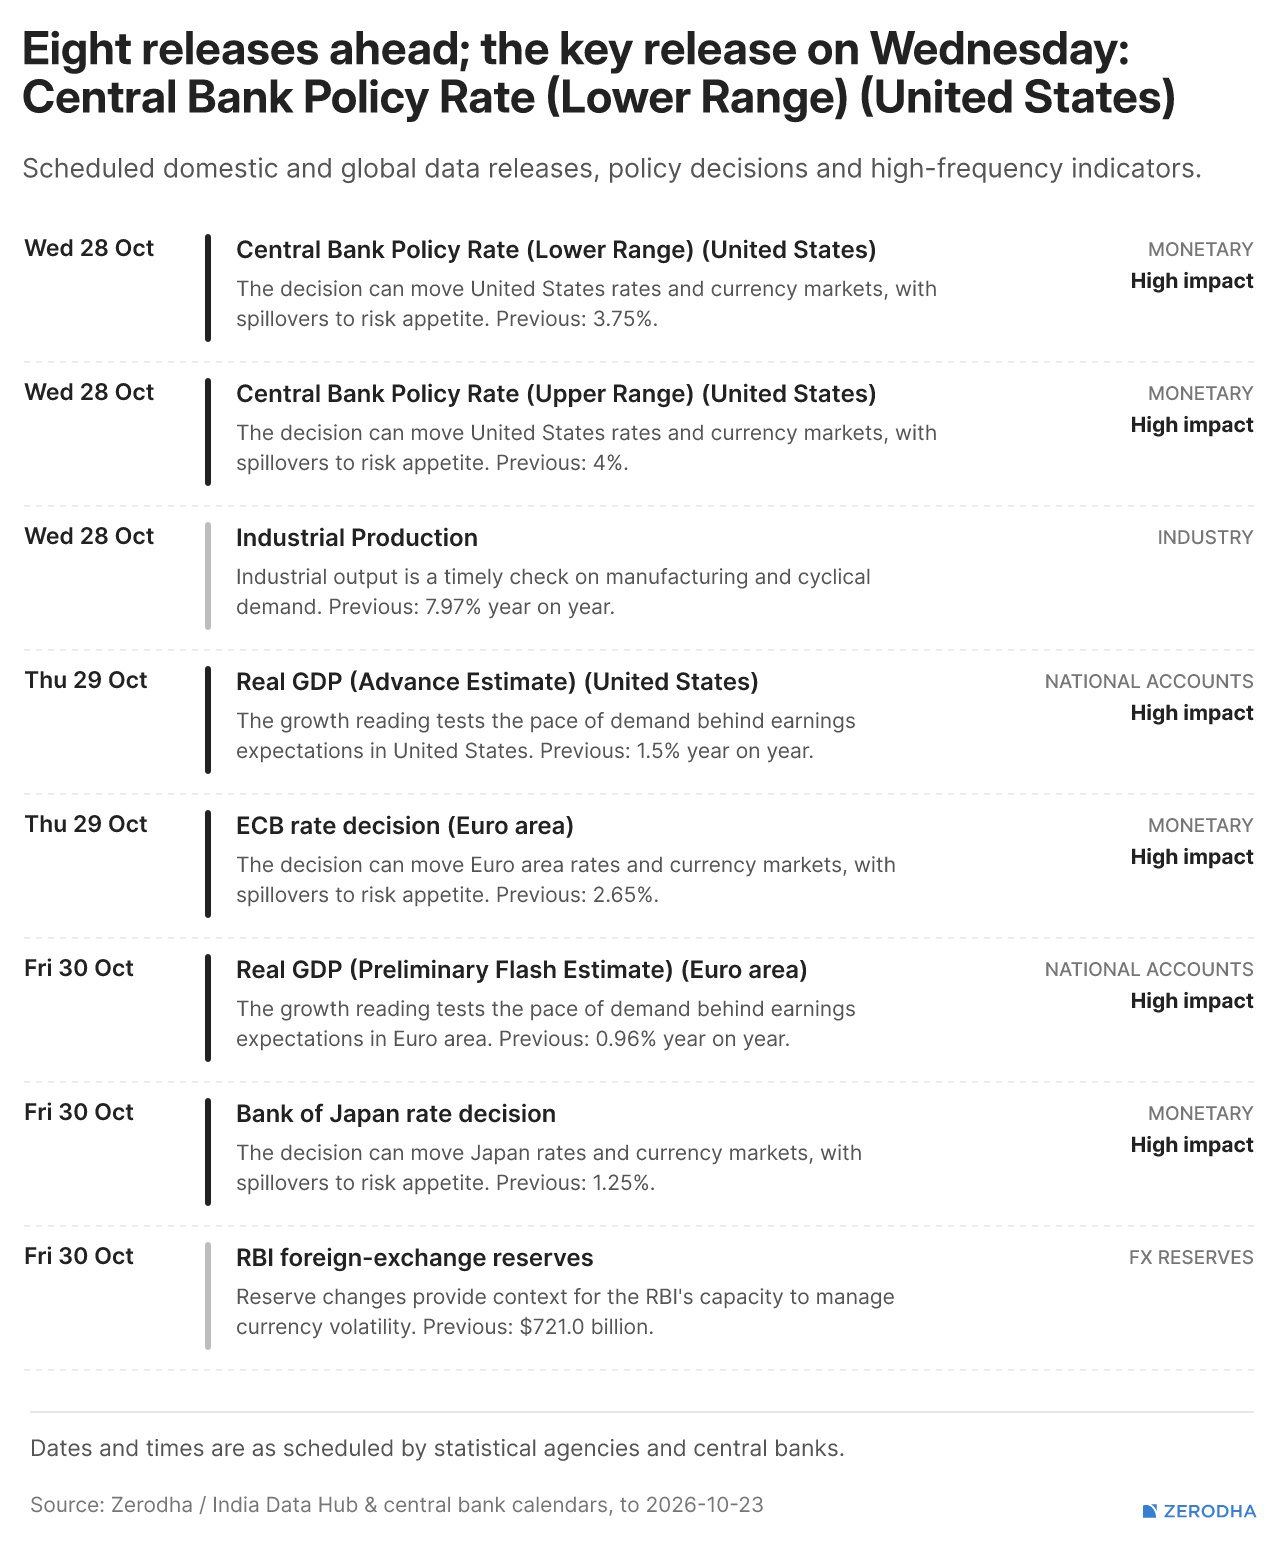
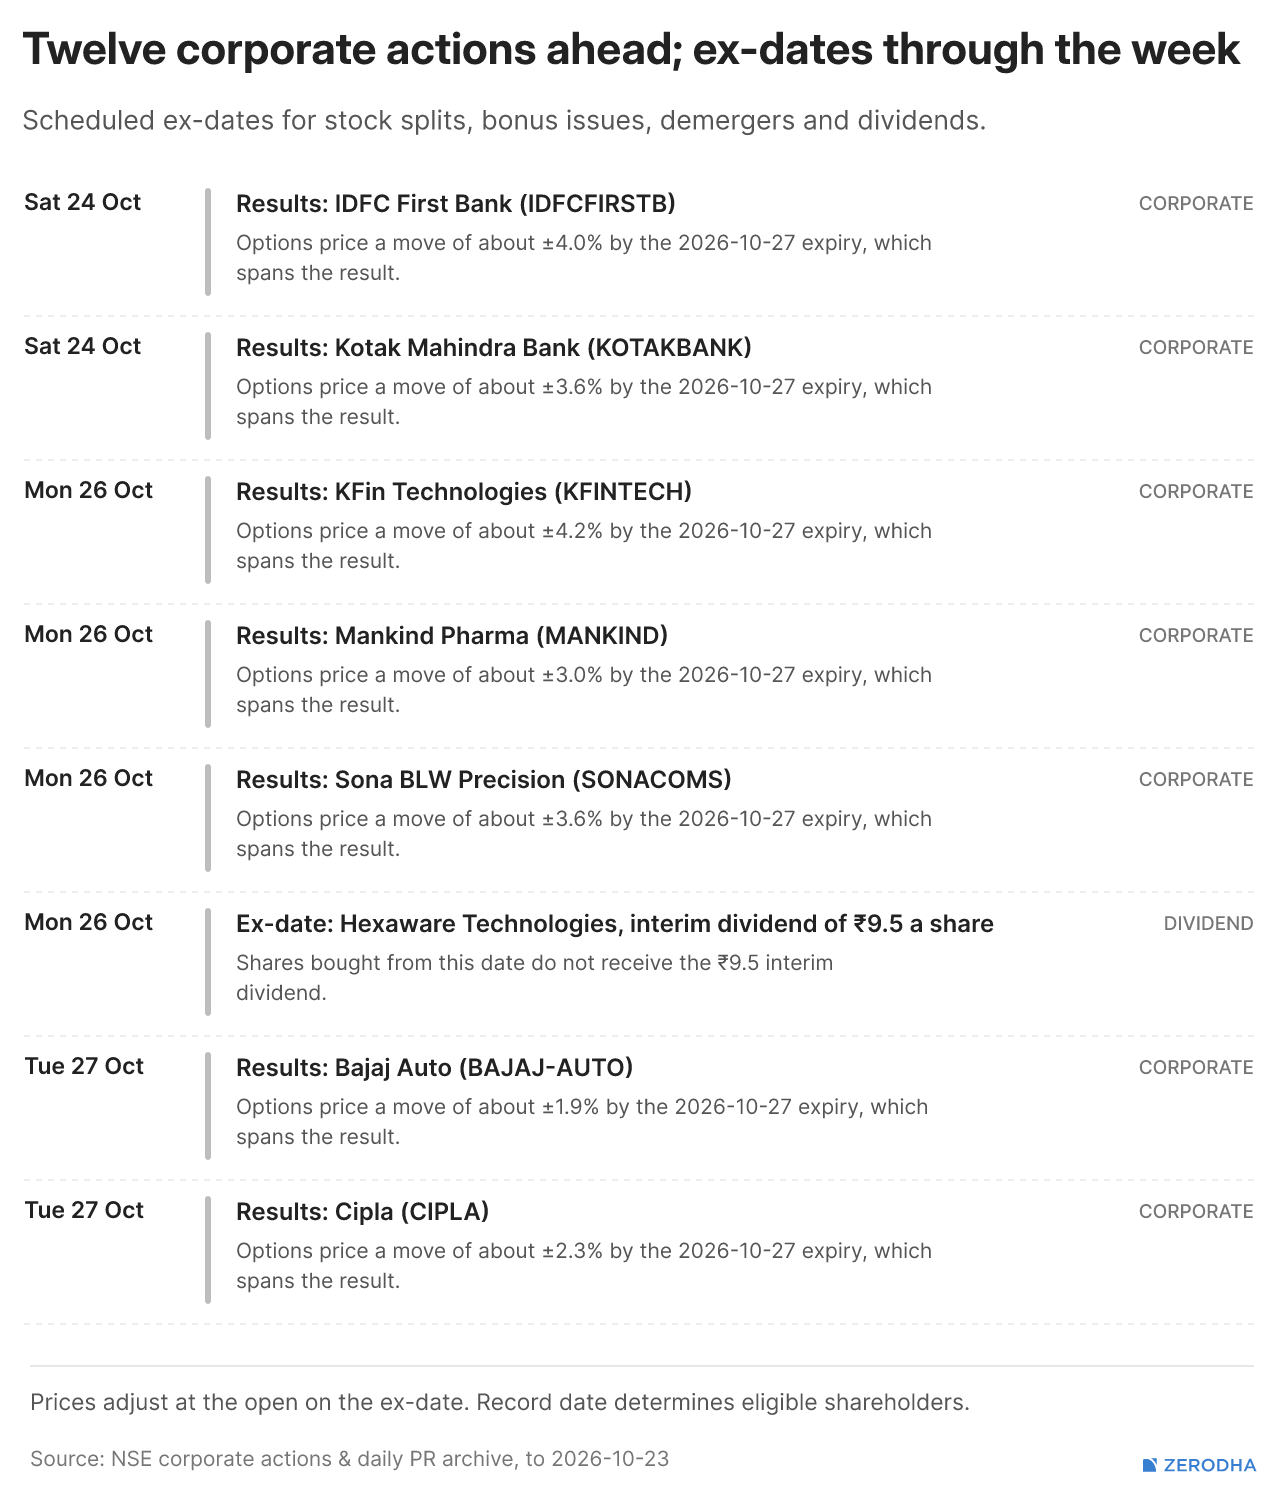
The week ahead & Corporate Actions
Corporate Actions
Published by Zerodha. Not investment advice. Data from NSE, BSE, and MCX.
In our latest episode of In The Money by Zerodha, we kick off The Fortnightly Show, a new series where market experts come together every two weeks to discuss markets, the economy, geopolitics, technicals, and more.
In this episode, host Sandeep Rao is joined by Amit Kumar Gupta and Nooresh Merani to discuss India’s evolving equity markets, the Nifty 50, the outlook for IT stocks, and the impact of interest rates and monsoons on consumption. We also explore the upcoming Jio Platforms IPO, foreign investor flows, and what drives global capital into and out of India. Finally, we look at the key events, index levels, and sectors to watch over the next two weeks.
That’s it from us for today. We’d love to hear your feedback in the comments, and feel free to share this with your friends to spread the word!